



PW Consulting Report: Prosthetic Foot Market Hits $830M in 2025, Projecting 6.4% CAGR to 2032

Navigating the Next Wave: Strategic Intelligence for the Prosthetic Foot Market (2026–2032)
The prosthetic foot market stands at a critical inflection point. Beyond the first prosthetic foot enabling basic ambulation, modern solutions are now engineered to restore high-impact mobility, adapt to variable terrains, and seamlessly integrate with the user’s biomechanical profile. As healthcare systems evolve, reimbursement frameworks tighten, and demographic shifts accelerate demand, stakeholders require more than surface-level market summaries. They need a precise, forward-looking intelligence framework that translates macro trends into actionable commercial and clinical strategies. The forthcoming Prosthetic Foot Market research delivers exactly that: a rigorous, evidence-based roadmap designed to inform capital allocation, product portfolio decisions, and go-to-market positioning through 2032.
Macro Trajectory: How Structural Shifts Are Reshaping the Market
Over the past half-decade, the prosthetic foot sector has demonstrated steady, compounding growth, recovering strongly from pandemic-era supply and demand disruptions and entering a phase of sustained expansion. From a baseline established in 2020, the market has tracked a consistent upward curve, crossing the 700-million threshold by 2023 and accelerating toward an estimated 830 million in 2025. Forward projections indicate that this momentum will carry the market well past the one-billion milestone during the late 2020s, ultimately approaching a valuation near 1.27 billion by 2032. The compound annual growth rate underpinning this trajectory sits at 6.4 percent, a figure that reflects not only rising prevalence of limb loss conditions but also the broadening adoption of advanced prosthetic technologies, improved reimbursement accessibility, and an expanding pipeline of active, mobility-focused end users.
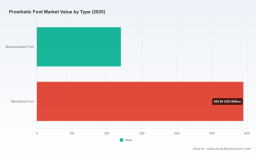
This growth is not uniform across product categories or patient demographics, and that uneven distribution holds vital strategic implications. Advanced microprocessor-controlled prosthetic feet are capturing an increasing share of clinical preference, driven by superior gait symmetry, fatigue reduction, and adaptability to complex environments. Yet mechanical feet remain foundational, sustaining broad volume across diverse payer environments and activity-level classifications. Meanwhile, the demand base is bifurcating: adult users continue to anchor core volume, while pediatric and adolescent segments are growing as early-intervention protocols mature and long-term mobility outcomes gain prominence in clinical guidelines. Understanding how these demand streams interact—and where margin pools actually concentrate—requires granular, segment-level analysis that goes far beyond headline numbers.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Makers
This study is built for practitioners who must make time-sensitive, resource-intensive decisions in a highly regulated, technology-intensive market. Rather than offering retrospective summaries, the report anchors its analysis in a structured forecast architecture covering the 2026–2032 horizon, calibrated against a transparent historical baseline spanning 2020 through 2025. The methodology is intentionally designed to support scenario planning, portfolio rationalization, and competitive positioning with precision.
Readers will find a multidimensional dissection of demand drivers, sales channels, and end-use adoption patterns, with particular attention to how activity-level classifications shape product-mix economics. The analysis unpacks the interplay between rehabilitation trajectories, payer policies, and prosthetic design requirements, enabling manufacturers, distributors, and service providers to anticipate where volume and value will shift next. Pricing architectures, reimbursement sensitivity, and component-level substitution dynamics are examined to clarify which product formats carry durable margin resilience and which face structural compression under evolving payer scrutiny.
Equally important, the research supplies the operational scaffolding needed to translate market signals into execution. Demand forecasts are mapped against realistic penetration ceilings, capacity considerations, and regional procurement behaviors. Strategic questions—such as whether to prioritize modular design ecosystems, where to concentrate advanced-technology commercialization efforts, and how to align clinical education campaigns with payer-aligned prescribing patterns—are addressed through a lens of commercial realism rather than theoretical optimism.
Competitive Arena: Where Leaders Are Winning—and Where the Gaps Remain
The competitive landscape is defined by a concentrated set of established players, each leveraging differentiated engineering philosophies, clinical relationships, and geographic footprints. Market concentration underscores this reality, with the top three firms collectively representing a substantial share of total revenue, and the top five extending that dominance even further. This structure rewards companies that can combine product reliability, clinical validation, and responsive commercialization while penalizing those that rely on undifferentiated volume plays.
Ottobock SE & Co. KGaA continues to reinforce its position through a dual-track portfolio that pairs mechanical strength with intelligent adaptation. Its Taleo and Evanto mechanical prosthetic feet target active users who demand durability and predictable energy transfer, while its microprocessor-controlled offerings extend the company’s reach into higher-complexity mobility scenarios. This balance allows Ottobock to serve both cost-sensitive and performance-oriented procurement pathways without diluting brand coherence.
Össur hf has built its reputation on dynamic, terrain-responsive design, and its current lineup reflects that philosophy with precision. The Proprio Foot, Pro-Flex family, Balance Foot, and Cheetah series are engineered to address variable walking conditions and high-activity demands. By emphasizing gait adaptability and user confidence across uneven surfaces, Össur positions itself squarely in the performance segment where functional outcomes often dictate purchasing decisions.
Blatchford Limited takes a different route, focusing on high-impact resilience and modular engineering. Its BladeXT e-carbon foot and Echelon series are oriented toward users who push beyond routine ambulation, requiring robust load handling and responsive energy return. The emphasis on active and high-demand user profiles gives Blatchford a clear niche in markets where clinical protocols prioritize return-to-activity outcomes.
College Park Industries contributes to the competitive mix with a focus on biomechanically tuned dynamic feet. The Soleus and Trustep lines highlight energy return and hydraulic modeling, meeting the needs of users who require smoother gait transitions and durable daily-use performance. This orientation appeals to clinicians seeking reliable, functionally versatile options across a broad activity spectrum.
Fillauer LLC strengthens the field with performance-oriented modular solutions. Its Aeris Performance line, alongside bio-attributed PVC shell designs, speaks to an expanding appetite for customizable, modular foot systems that can be adapted to individual residual limb characteristics and activity requirements. This modularity-centric approach aligns with broader industry trends favoring adaptability and component-level servicing.
WillowWood Global LLC has moved to deepen its market relevance through both product engineering and partnership strategy. Its MetaShock dynamic feet and modular component sets are designed for users operating at K3 and K4 activity levels, while its December 2025 strategic partnership with Click Medical signals a clear push toward user-specific prosthetic solutions. Such collaborations reflect a wider industry shift toward personalized fitting workflows and integrated care models.
Worldwide 3D Printed Prosthetic Hands Market
Streefedered KG rounds out the competitive picture with modular systems built for customization. Its Vari-Flex line and modular foot configurations cater to practitioners who value flexible component selection and patient-specific tuning, reinforcing the market’s ongoing emphasis on individualized mobility solutions. Endolite adds further depth with its broad portfolio of components and feet engineered for varied amputation levels, supporting clinical teams that require scalable, level-appropriate solutions across diverse patient populations.
The strategic implication for stakeholders is clear: pricing power, channel access, and clinical adoption will increasingly favor companies that can integrate product differentiation with reimbursement alignment and service scalability. Firms that treat these dimensions as separate workstreams will find themselves outmaneuvered by competitors who treat them as a unified commercial architecture.
2026 Reimbursement Realities: Why Policy Is Now a Product Strategy Variable
One of the most consequential developments shaping near-term decision-making is the reconfiguration of payer coding and reimbursement pathways. In March 2026, the Centers for Medicare & Medicaid Services announced final determinations for lower extremity prosthetics, including the introduction of a new HCPCS code, L5992. Effective April 1, 2026, this code is designated for replacement of foot shells in modular or non-solid ankle cushion heel prosthetic feet and is separately payable at a rate of 127.11 dollars. The same determinations clarify that foot covers remain included within base foot component codes and are not separately payable.
For manufacturers, distributors, and prosthetic service providers, this is not merely a compliance update. It is a structural input into product economics, service-model design, and portfolio prioritization. Separately payable foot-shell replacement creates a distinct revenue touchpoint that can influence how modular systems are positioned, how service contracts are structured, and how clinical teams approach long-term component maintenance. At the same time, the explicit exclusion of foot covers from separate reimbursement reinforces the importance of base-component pricing discipline and value communication.
These reimbursement dynamics interact directly with broader market concentration and product-mix trends. In a market where a limited number of firms already command the majority of revenue, reimbursement shifts can accelerate consolidation advantages, reward companies with clearer modular articulation, and pressure players whose economics depend on blended, less-transparent pricing. Companies that fail to map reimbursement changes onto their product architecture risk mispricing innovation, misaligning sales incentives, or under-serving the maintenance needs that drive long-term patient retention.
Where Strategic Focus Should Land in 2026
As the market advances toward the 2032 horizon, the most successful organizations will be those that treat product development, reimbursement intelligence, and commercial execution as tightly coupled systems. Several strategic priorities stand out.
First, segmentation precision must move from retrospective reporting to forward-looking portfolio design. Volume concentration across adult and pediatric populations, and across mechanical and microprocessor-controlled categories, will shape where R&D dollars produce the strongest commercial returns. Companies that can identify the highest-value intersection of activity level, reimbursement compatibility, and clinical preference will deploy capital more efficiently than those pursuing blanket expansion.
Second, reimbursement navigation is now a core competitive capability. The L5992 pathway, along with broader payer scrutiny on component-level billing, demands that commercial teams understand not just price points but the operational logic of claims, coverage rules, and service cycles. Alignment between clinical messaging, product documentation, and reimbursement architecture will differentiate firms that can secure consistent procurement from those that face repeated reimbursement friction.
Third, partnership and modularity strategies will increasingly determine market agility. The recent WillowWood–Click Medical collaboration illustrates a broader pattern: the market is moving toward more individualized fitting, integrated service delivery, and component ecosystems that reduce friction across the patient journey. Firms that can embed themselves in these workflows—through engineering compatibility, distribution relationships, or joint solution design—will be better positioned to capture sustained demand.
Prosthetic Foot Market
Finally, competitive positioning will hinge on the ability to communicate differentiated clinical value without overpromising on outcomes that payers and clinicians will scrutinize. High-impact designs, terrain-adaptive mechanics, and microprocessor intelligence each solve real user problems, but their commercial success depends on clear reimbursement alignment, credible clinical evidence, and service models that sustain performance over time. In a concentrated market, reputation and reliability can be as decisive as feature sets.
Why the Full Report Matters Now
The prosthetic foot market is no longer defined solely by volume growth. It is being reshaped by reimbursement architecture, product modularity, competitive concentration, and the accelerating expectation that prosthetic solutions should support high-function, real-world mobility. The 6.4 percent CAGR and multi-year revenue trajectory signal opportunity, but opportunity without segmentation insight, reimbursement literacy, and competitive clarity can easily translate into misallocated investment or missed positioning windows.
This research was designed to close that gap. It provides the analytical depth required to evaluate where demand is genuinely expanding, which product and service architectures are most resilient under current payer conditions, and how leading players are structuring their portfolios to defend or extend market share. The macro numbers offer direction; the segment-level dynamics, competitive profiles, and reimbursement-sensitive economics offer the precision needed to act.
Organizations preparing product launches, portfolio reviews, capacity planning, or regional market entry in 2026 will find the full report essential for stress-testing assumptions and prioritizing moves with the highest strategic payoff. Complete segmentation breakdowns, forward scenario analysis, and detailed competitive benchmarking are available in the full study. Readers seeking the complete intelligence framework, including the granular data necessary to translate these market signals into execution-ready plans, are encouraged to access the full report through the source page.
For detailed analysis of this topic, please visit the official page: Prosthetic Foot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


