



PW Consulting Report: Healthcare Furniture Market Hits $708M in 2025, Projects 5.41% CAGR Through 2032

Strategic Horizons in Healthcare Furniture: Navigating Growth, Compliance, and Competitive Shifts Through 2032
The global healthcare furniture market stands at a critical inflection point. As care delivery models evolve, facility design standards tighten, and capital allocation decisions grow increasingly scrutinized, the physical environment of healthcare spaces is no longer a secondary consideration. It has become a strategic lever that influences patient outcomes, staff retention, operational efficiency, and long-term asset depreciation. Our latest market intelligence assessment, covering historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast horizon, provides executives, procurement leaders, and product strategists with a structured framework to navigate this complex landscape.
The research is engineered not as an abstract macro exercise, but as an operational decision-support tool. It translates trajectory signals, regulatory shifts, and competitive realignments into actionable intelligence that can inform product roadmaps, facility investment phasing, supply chain positioning, and market entry or expansion strategies. For organizations preparing capital deployments, specification portfolios, or manufacturing capacity adjustments in 2026, the report functions as a calibrated compass rather than a static snapshot.
Macro Trajectory and the Strategic Imperative for 2026 Decision-Making
Over the past half-decade, the sector has demonstrated steady expansion, reflecting sustained investment in care infrastructure, aging facility fleets, and the ongoing modernization of clinical and support environments. Historical revenue progression from the early 2020s through the base year of 2025 illustrates a market that has consistently advanced despite episodic supply chain friction, labor cost pressures, and procurement recalibration. That momentum carries directly into the forecast window, where the trajectory points toward sustained growth at a compound annual rate of 5.41 percent across the 2026 to 2032 period.
Healthcare Flooring Market
For executives planning multi-year commitments, this growth rate is not merely a directional indicator. It signals the pace at which demand will compound across product categories, care settings, and geographies, influencing everything from raw material procurement and manufacturing capacity planning to channel partnerships and specification cycles. The forecast period also captures a structural transition: as healthcare systems balance clinical modernization against constrained operating budgets, furniture procurement is increasingly evaluated through total cost of ownership, lifecycle durability, infection-control compatibility, and staff workflow optimization rather than upfront unit cost alone.
The research unpacks these trajectory dynamics in a way that supports scenario planning. Readers will find forward-looking revenue pathways mapped across the full forecast horizon, alongside the contextual drivers that shape demand elasticity, specification lead times, and replacement cycles. By anchoring 2026 planning decisions to a rigorously constructed outlook, organizations can reduce blind spots around capacity timing, regional allocation, and product mix optimization.
Beyond Headline Numbers: The Operational Depth of the Report
The intelligence architecture within this study is designed to move decisively beyond top-line metrics. While the report captures the full historical arc from 2020 and projects performance through 2032, its core value lies in the granular analytical layers that translate market movement into operational guidance. The study systematically evaluates how demand is distributed across product categories, care environments, and regional markets, providing a clear picture of where volume concentrates, where growth is accelerating, and where substitution or consolidation dynamics are reshaping procurement behavior.
Specifiers and manufacturers will find particular utility in the product-type and application analyses, which illuminate shifting priorities in patient room configuration, caregiver support environments, diagnostic adjacencies, and ambulatory or homecare-adjacent settings. Rather than presenting truncated category snapshots, the report contextualizes each segment within broader operational realities: throughput demands, cleaning and disinfection protocols, ergonomic requirements, footprint constraints, and the growing expectation that furniture actively supports infection-prevention workflows and staff resilience.
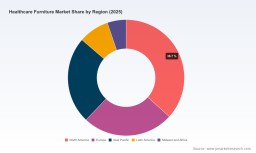
Regional demand patterns are examined with equal rigor. The analysis captures how mature markets with entrenched facility renewal cycles compare against emerging demand centers where infrastructure expansion, capacity additions, and modernization investments are reconfiguring procurement pipelines. This regional layering is essential for organizations evaluating export strategies, local assembly or sourcing decisions, specification influence, and channel partnerships. The report deliberately avoids superficial share comparisons, instead focusing on the underlying drivers that determine where sustained revenue opportunity is likely to materialize and where competitive intensity will require differentiated positioning.
Competitive Landscape: Incumbents, Positioning, and Strategic Realignment
The competitive environment in healthcare furniture is defined by a mix of established workplace and healthcare-focused manufacturers, category specialists, and full-facility solution providers. Several players shape the structural dynamics of the market, each with distinct design philosophies, manufacturing footprints, and end-user value propositions.
Steelcase continues to anchor its healthcare offerings around patient seating, waiting environments, examination spaces, and modular casegoods engineered for care settings. Its portfolio reflects a strong emphasis on environmental psychology, flexibility, and specification-grade design that aligns clinical function with patient and visitor experience. Haworth approaches the category with a pronounced focus on caregiver ergonomics, mobile cart ecosystems, height-adjustable workstations, and modular spatial solutions that support both patient-facing and staff-oriented areas. This caregiver-centric lens positions the company well within facilities prioritizing workflow efficiency and staff sustainability.
Hillrom contributes a diversified hospital furniture lineup spanning overbed tables, patient room casegoods, sleeper sofas, and recliners tailored to care environments. Its product architecture aligns closely with the practical demands of inpatient settings, where durability, adjustability, and infection-compatible surfaces are paramount. Spec Furniture has built its reputation on durable seating, overbed tables, patient room casegoods, and cafeteria tables serving hospitals and broader facilities, giving it a strong operational-fit profile for high-use care environments. Carolina extends its reach across patient rooms, staff areas, and full-facility environments, constructing product systems intended to support both healing environments and operational throughput. Trinity Furniture rounds out the competitive set with traditional and transitional wood furniture solutions, including seating and tables designed for patient rooms, behavioral health contexts, and general care facilities.
The market structure reflects meaningful concentration at the top tier, with the three largest players collectively accounting for a substantial share of industry revenue and the top five expanding that footprint further. This concentration matters for procurement strategy, specification influence, pricing expectations, and negotiation leverage. At the same time, the presence of specialized and regional manufacturers sustains competitive pressure in high-use categories and facility-specific applications, ensuring that incumbents must continually justify differentiation through design, service, delivery reliability, and lifecycle performance.
Recent corporate and standards developments further reshape the landscape. The acquisition of Spec Furniture by Flokk in April 2026 signals an intentional expansion of presence in the U.S. healthcare market for seating and tables, consolidating capability and distribution reach at a moment when facility demand remains robust. Simultaneously, the publication of BIFMA G8.1-2026 in February 2026 introduces updated guidance on furniture surface design and durability for cleaning, sanitizing, and disinfecting. For manufacturers and specifiers alike, this standard reframes performance expectations and creates a new reference point for product development, materials selection, and specification documentation.
Healthcare Furniture Market
Market Dynamics Shaping Capital Allocation and Specification Decisions
The operational environment for healthcare furniture is being reshaped by intersecting forces that directly impact procurement timing, specification criteria, and investment prioritization. Regulatory and standards evolution is one of the most consequential. The February 2026 BIFMA guideline on furniture surfaces, cleaning durability, and disinfection compatibility raises the bar for how products must perform in active care environments. This development matters not only for product design teams, but also for purchasing leaders who must validate that specified furniture meets evolving infection-control expectations without compromising aesthetics, flexibility, or lifecycle economics.
Reimbursement and procurement policy dynamics add another layer of complexity. The American Hospital Association has pushed for exemptions from CMS-approved vendor requirements for non-clinical items, including office furniture, signaling that healthcare systems are actively seeking relief from administrative and supply-chain constraints that elevate cost and slow acquisition cycles. This advocacy underscores a broader tension: facility leaders need to upgrade and replace furniture to support care quality and staff retention, yet many operate under procurement frameworks and budget pressures that complicate long-planned capital projects.
Labor economics further complicate the investment equation. The American Hospital Association’s 2025 Health Care Workforce Scan highlighted that hospitals contended with high labor expenses exceeding $42.5 billion during the 2021 to 2023 period, constraining discretionary investment in facility upgrades, including furniture. When operating costs surge, facility modernization can be deferred, but deferral carries its own risk: aging furnishings, workflow friction, and environmental wear can compound operational strain and negatively affect staff experience. The report examines how this cost-pressure environment influences replacement cycles, specification trade-offs, and the growing preference for solutions that demonstrate measurable support for staff efficiency and durability under heavy use.
Taken together, these dynamics create a market where differentiation is increasingly tied to performance evidence, compliance alignment, total cost of ownership, and the ability to support both patient-centered design and caregiver workflow. Organizations that anticipate these shifts and align product development, specification support, and procurement messaging accordingly will be better positioned to capture demand as budgets normalize and facility renewal accelerates.
Why This Research Matters for 2026 Strategy Execution
The strategic value of this report lies in its translation of market trajectory, competitive positioning, and environmental dynamics into practical decision inputs. For manufacturing and product leaders, the research supports portfolio rationalization, material and surface engineering priorities, and category focus decisions in the context of updated durability and cleaning-performance expectations. For commercial and channel teams, it clarifies where specification influence is strongest, which applications are expanding fastest, and how regional demand patterns should inform capacity allocation and market-entry sequencing. For procurement and facilities executives, it provides a structured basis for evaluating replacement timing, total cost of ownership, compliance alignment, and supplier diversification strategies.
The analysis also serves as a strategic alignment tool for organizations evaluating partnerships, acquisitions, or capability expansion. By mapping concentration patterns, category leadership dynamics, and recent corporate activity such as the Flokk-Spec Furniture transaction, the report helps decision-makers assess where consolidation pressure may intensify and where differentiated positioning can create durable advantage. Similarly, the inclusion of regulatory and reimbursement developments ensures that strategic plans account for the policy environment that will shape specification behavior and procurement feasibility across the forecast period.
Most importantly, the research is structured to support executive decision-making under uncertainty. The 2026 to 2032 forecast window captures a period in which healthcare systems are likely to continue balancing modernization goals against operational cost realities. Organizations that approach this environment with rigorous demand visibility, a clear understanding of competitive and standards-driven shifts, and a disciplined view of where value will be captured will be better equipped to make capital, product, and market decisions that hold up over multiple planning cycles.
Accessing the Full Intelligence Framework
This overview has outlined the strategic contours of the healthcare furniture market and the analytical approach underpinning our latest research. It has also highlighted the competitive, regulatory, and cost-environment dynamics that will shape procurement and product strategy in 2026 and beyond. Yet the full decision-support value of the study resides in the comprehensive segmentation depth, forecast continuity, competitive profiles, and scenario-ready datasets that extend well beyond the macro narrative.
Organizations seeking to translate these insights into concrete product, procurement, and growth decisions can access the complete report, which delivers detailed segmentation coverage, forward revenue pathways, competitive benchmarking, and the supporting analytical architecture required for operational planning. For teams responsible for capital allocation, specification strategy, manufacturing planning, or market positioning, the full research provides the granularity needed to move from directional confidence to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Healthcare Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


