



PW Consulting: Medication Adherence Packaging Market Hits $212.78M in 2025, Projects 5.54% CAGR to 2032

Navigating the Next Wave: Strategic Imperatives in the Medication Adherence Packaging Systems Market
The global pharmaceutical supply chain is undergoing a quiet but profound transformation. As healthcare systems worldwide grapple with rising chronic disease burdens, aging demographics, and the escalating cost of non-adherence, the packaging that delivers medication has evolved from a passive container into an active therapeutic intervention. For executives, investors, and product strategists, understanding the trajectory of the Medication Adherence Packaging Systems Market is no longer a niche curiosity. It is a strategic necessity. Our latest research release maps this evolution with precision, offering a decision-grade lens into how the sector will perform from 2026 through 2032.
The market has demonstrated consistent momentum over the past five years, driven by a convergence of regulatory pressure, reimbursement realignment, and technological maturation. Historical performance data reveals a sector that has navigated supply chain volatility, shifting care delivery models, and early-stage digital integration without losing its growth trajectory. As organizations prepare their 2026 capital allocation and product roadmaps, this research provides the structural clarity required to separate signal from noise.
Market Trajectory and Structural Growth Drivers
The Medication Adherence Packaging Systems Market has expanded from a baseline of roughly 163 million USD in 2020 to approximately 212 million USD by 2025, reflecting a compound annual growth rate that underscores steady, secular demand rather than speculative hype. Forecasts project the market will reach approximately 222 million USD in 2026, with continued expansion toward the 313 million USD range by 2032. This growth is not merely a function of volume; it is rooted in fundamental shifts in how medications are prescribed, dispensed, and monitored.
Several structural forces are accelerating this trajectory. First, healthcare payers and providers are increasingly recognizing that adherence failures represent a hidden tax on clinical outcomes and budget efficiency. Specialty medications, which command premium pricing and complex administration protocols, have claimed a disproportionate share of total drug expenditures in recent years, intensifying the need for packaging systems that reduce dosing errors, simplify refill cycles, and enable remote monitoring. Second, the decentralization of care is reshaping distribution endpoints. As more patients receive chronic therapy outside traditional hospital walls, packaging solutions must bridge the gap between clinical oversight and home-based self-management. Third, digital integration is transitioning from experimental add-on to core architecture. Packaging systems that couple physical dose organization with connectivity, data capture, and clinician-facing dashboards are rapidly becoming the expected baseline rather than the premium tier.
These dynamics create a market environment where growth is both broad and uneven. The research dissects how revenue generation is distributed across packaging formats, care settings, and geographic corridors, revealing where demand is most concentrated and where whitespace opportunities persist. Crucially, the analysis isolates the operational and regulatory factors that determine which manufacturers can scale efficiently and which face margin compression or compliance friction.
Segmentation Architecture and Application Realities
Understanding how the market fragments is essential for product positioning, pricing strategy, and channel selection. The research breaks down the landscape across three primary dimensions: packaging type, end-use application, and regional deployment. Each dimension carries distinct commercial implications.
Packaging Typology and Format Economics
The market is anchored by two broad packaging philosophies: unit-dose systems and multi-dose systems. Unit-dose formats continue to dominate in environments where dose-level precision, traceability, and dispensing control are paramount. These systems are closely aligned with institutional workflows, automated pharmacy line operations, and clinical protocols that require individual dose accountability. Multi-dose formats, by contrast, address convenience, patient experience, and longitudinal adherence tracking. They are increasingly favored in ambulatory care, retail pharmacy fulfillment, and home-based regimens where reducing pill burden and simplifying refill synchronization drive compliance.
The research examines how these formats compete, complement, and increasingly converge through hybrid designs. It also evaluates the capital intensity, throughput requirements, and software dependencies that differentiate the two categories, enabling stakeholders to assess which format aligns with their target customer economics and service models.
Care Settings and End-Use Demand Profiles
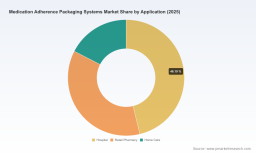
Demand is not uniform across points of care. Hospitals represent a substantial and process-driven segment, where adherence packaging is integrated into medication administration workflows, barcoded verification systems, and closed-loop dispensing environments. Retail pharmacies function as a critical distribution node, translating prescription volume into patient-facing compliance tools while navigating space constraints, workforce limitations, and margin pressures. Home care constitutes a rapidly expanding frontier, fueled by remote patient monitoring programs, aging-in-place initiatives, and the shift of chronic therapy management away from acute settings.
Each application segment presents distinct purchasing criteria. Institutional buyers prioritize integration, validation, workflow efficiency, and regulatory alignment. Retail and community pharmacy buyers focus on throughput, packaging flexibility, and patient retention value. Home care stakeholders increasingly emphasize usability, connectivity, and support for caregivers. The report maps these demand profiles to product capabilities, helping manufacturers and investors calibrate feature roadmaps and go-to-market strategies.
Regional Corridors and Deployment Patterns
Geographically, the market reflects uneven maturity, differing reimbursement environments, and localized pharmacy infrastructure. North America remains a dominant demand center, supported by established pharmacy networks, chronic disease prevalence, and early adoption of connected adherence tools. Europe exhibits strong institutional and community pharmacy demand, shaped by national health system structures and evolving digital health frameworks. Asia Pacific represents a high-potential corridor where expanding pharmaceutical access, urbanization, and growing awareness of adherence-linked outcomes are creating new deployment opportunities. Latin America and the Middle East and Africa contribute additional growth vectors, often driven by specific public health programs, private pharmacy expansion, and targeted chronic care initiatives.
Worldwide Medicine Packaging Adhesive Market
Rather than presenting a flat regional snapshot, the research evaluates how local regulatory regimes, distribution density, reimbursement pathways, and care delivery norms shape adoption velocity. This allows clients to prioritize market entry, partnership models, and localization investments with a realistic view of where traction is achievable and what friction points must be addressed.
Competitive Landscape and Strategic Positioning
The Medication Adherence Packaging Systems Market is characterized by a concentrated but dynamically evolving player base. Market concentration metrics indicate that leading participants command meaningful share, yet the space remains open to innovation-driven entrants, especially where digital adherence, automation, and software-enabled workflows create differentiation. Understanding the strategic posture of key incumbents is critical for assessing partnership opportunities, acquisition targets, and competitive threats.
Established Players and Capability Profiles
Medicine-On-Time LLC has built a reputation around multi-dose compliance packaging and customizable adherence workflows for pharmacies and care settings. Its offering centers on structured compliance packaging and software-enabled configuration, positioning it as a partner for organizations seeking to standardize adherence interventions while preserving flexibility across patient populations.
Parata Systems LLC operates at the intersection of automation and packaging format versatility. Its automated blister card and pouch packaging systems are designed to support both single-dose and multi-dose regimens, appealing to pharmacy operations that need throughput, consistency, and scalable deployment across varying prescription volumes.
Omnicell, Inc. brings a broader institutional footprint, combining medication blister card packaging, cup-style adherence formats, and automated dispensing systems tailored to patient-specific multi-dose regimens. Its strength lies in environments where adherence packaging must integrate tightly with dispensing control, inventory management, and clinical workflow oversight.
AARDEX Group represents a distinct digital adherence angle. Its MEMS-enabled packaging and monitoring devices span oral, injectable, and other routes, supported by software platforms intended for clinical trial and patient monitoring contexts. This positions the company at the convergence of packaging, adherence measurement, and data-rich oversight, an increasingly important axis as outcomes-based reimbursement and decentralized trials gain traction.
Recent Developments and Innovation Signals
The competitive field is not static. Recent product launches demonstrate how manufacturers are layering connectivity and cloud-enabled intelligence into adherence tools. In April 2025, Centor Inc. and Gerresheimer AG introduced a smart weekly pill organizer built on LTE and cloud technology, designed to support real-time medication intake monitoring without requiring patient app pairing. This type of development signals a broader shift toward low-friction connectivity, where adherence data can be captured and transmitted without imposing additional burden on patients. For competitors, such moves raise the bar on usability and data accessibility while also reshaping expectations among pharmacy buyers, care providers, and payer-aligned programs.
Medication Adherence Packaging Systems Market
Regulatory and Reimbursement Dynamics
No strategic assessment of this market is complete without addressing the regulatory and reimbursement scaffolding that shapes commercialization. Certain medication adherence packaging systems and blister cards require FDA 510(k) clearance prior to commercialization, meaning time-to-market, validation pathways, and regulatory strategy are integral to competitive positioning. At the same time, digital adherence packaging and devices are increasingly expected to align with frameworks such as FDA 21 CFR Part 11 and ICH GCP compliance, particularly in clinical trial and monitoring contexts where data integrity and auditability are non-negotiable.
Reimbursement dynamics further influence adoption economics. Specialty medications have accounted for a substantial share of total drug expenditures in recent years, reinforcing the financial case for adherence interventions that reduce waste, improve persistence, and support better outcome tracking. However, reimbursement structures vary widely by region, payer type, and care setting. The research analyzes how these reimbursement pressures interact with packaging investment decisions, highlighting where value demonstration, health economics evidence, and integration with care programs can accelerate adoption.
What the Research Delivers
This market research is designed as an operating document for strategic planning, not a static summary. It synthesizes historical performance, forward forecasts, segmentation detail, competitive intelligence, and regulatory context into a coherent decision framework. Stakeholders will find practical value across several dimensions.
- Forecasted market size and growth trajectory across the 2026 to 2032 horizon, anchored in historical baselines and trend analysis
- Segment-level breakdowns by packaging type, application setting, and regional deployment that reveal where demand concentrates and where differentiation matters most
- Competitive profiles that map incumbent capabilities, technology orientations, and strategic focus areas
- Regulatory and reimbursement context that clarifies clearance requirements, compliance expectations, and economic adoption drivers
- Recent product and technology developments that indicate where innovation is heading and how customer expectations are shifting
- Analytical frameworks to support market entry, portfolio prioritization, partnership evaluation, and investment timing
Importantly, the report is structured to support specific business questions: which packaging formats align with target segments, how care setting economics shape purchasing behavior, where regional deployment is most viable, and how digital adherence capabilities are reshaping competitive advantage. The objective is to give executives and analysts a credible foundation for 2026 planning without resorting to generic market commentary.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment will reward organizations that can align packaging strategy with care delivery realities, regulatory readiness, and digital adoption curves. Companies that treat adherence packaging as a purely mechanical category risk underpricing the strategic value of workflow integration, data capture, and patient experience. Organizations that over-index on connectivity without addressing clearance timelines, reimbursement proof points, or pharmacy workflow constraints will struggle to convert innovation into commercial traction.
This research helps bridge that gap. It provides the macro context needed to set portfolio direction, the segmentation insight required to target the right customers, and the competitive understanding necessary to anticipate moves by entrenched players and emerging challengers. For manufacturers, it informs feature prioritization and capacity planning. For investors, it clarifies where growth is durable versus cyclical. For healthcare and pharmacy stakeholders, it offers a benchmark for evaluating vendor claims and adoption readiness.
Ultimately, the Medication Adherence Packaging Systems Market is entering a phase where scale, precision, and intelligence must coexist. The organizations that succeed will be those that understand not only how large the opportunity is, but how it is constructed, where value is created, and what evidence is required to convert potential into adoption.
Access the Full Intelligence
The excerpts above provide a strategic preview of the market landscape and the analytical depth available in the full report. To move from high-level direction to actionable planning, stakeholders need the complete segmentation values, forecast tables, competitive benchmarks, regional deployment analysis, and regulatory context contained in the full study. The complete research package delivers the granular data and structured conclusions necessary to support investment memos, product roadmaps, partnership evaluations, and market-entry strategies.
For decision-makers preparing for 2026 and beyond, this report offers a disciplined view of where adherence packaging is headed and how to position for the opportunities that follow. Access the full report to retrieve the detailed market size trajectories, segmentation splits, competitive assessments, and scenario-ready insights needed to make informed, evidence-based decisions.
For detailed analysis of this topic, please visit the official page: Medication Adherence Packaging Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


