



PW Consulting: Digital Pathology Market Hits $1.13B in 2025, Projected to Reach $2B by 2032

Digital Pathology Market 2026: Strategic Intelligence for the Next Wave of Diagnostic Transformation
The global digital pathology market is entering a defining inflection point. As laboratories, health systems, and life science organizations navigate shifting regulatory frameworks, evolving reimbursement pathways, and the maturation of artificial intelligence in histopathology, strategic decision-making requires more than surface-level trend spotting. PW Consulting’s newest Digital Pathology Market research delivers the structured intelligence that executives, investors, and product leaders need to position themselves ahead of the 2026–2032 cycle.
This market has demonstrated consistent expansion over the past half-decade, driven by the migration from conventional glass-slide workflows to digitized imaging ecosystems, the integration of computational pathology tools, and growing institutional demand for telepathology and collaborative diagnostics. The market’s trajectory reflects both long-term secular adoption and short-term catalyst events that reshape competitive positioning. Our latest analysis quantifies that momentum, maps the structural forces shaping commercialization, and isolates the operational levers that will determine market share in the years ahead.
For leadership teams making capital allocation, partnership, or market-entry decisions in 2026, the window to act on validated intelligence is narrow. The research is designed not as a retrospective snapshot, but as a forward-looking strategic instrument—connecting macro trajectory, competitive dynamics, regulatory inflection points, and segment-level deployment patterns into a single decision-ready framework.
Growth Trajectory and the 2026–2032 Outlook
The market’s historical expansion provides a clear baseline for understanding where adoption is accelerating and where friction persists. Between 2020 and 2025, the global digital pathology market progressed from approximately 760.0 million USD to 1130.0 million USD, reflecting sustained demand for whole-slide imaging scanners, digital image management infrastructure, and workflow optimization tools. The forecast period from 2026 through 2032 projects continued expansion, with the market expected to reach roughly 2001.0 million USD by the end of the forecast horizon. The compound annual growth rate during this forecast window is estimated at 8.6 percent, signaling durable, above-trend growth rather than a temporary adoption spike.
This trajectory matters because it shapes the timing of competitive moves. A market expanding at this pace over a seven-year forecast window rewards early architecture decisions—platform interoperability, integration with laboratory information systems, and alignment with clinical workflow. Organizations that treat digital pathology as a discrete product purchase rather than a fused operational system risk ceding the efficiency gains that drive long-term adoption. Our research quantifies the scale of this opportunity while deliberately leaving the detailed segment-level breakdowns for the full report, where regional deployment patterns, type-specific revenue structures, and application-level demand concentrations are mapped in operational detail.
What the Research Covers: Operational Depth for Decision-Makers
A market study becomes strategically valuable only when it translates numbers into action. Our Digital Pathology Market research is built around the practical needs of executives who must evaluate investment timing, competitive vulnerability, regulatory exposure, and commercial execution risks. The report combines macro-level market quantification with structured analyses that support near-term planning.
The research framework includes comprehensive assessment of the following dimensions, each presented with enough granularity to inform real operational decisions:
- Market size and growth modeling across historical and forecast periods, with explicit treatment of base-year anchoring and forward trajectory assumptions
- Structural analysis of demand drivers, adoption barriers, and the interplay between technology readiness and institutional procurement cycles
- Competitive benchmarking of leading instrumentation, software, and AI-enabled diagnostic platforms, including product positioning, workflow integration, and cleared indications
- Regulatory and reimbursement context, with focus on classification pathways, clearance activity, and payer monitoring that will affect commercialization cadence
- Workflow and deployment considerations that distinguish research-use setups from diagnostic-grade implementation requirements
- Strategic scenario discussion for manufacturers, laboratory operators, and technology providers evaluating partnership, expansion, or differentiation plays
The overarching goal is to give leadership teams a shared factual foundation. Too often, strategic discussions around digital pathology are fragmented by incomplete data, outdated regulatory assumptions, or anecdotal adoption stories. This report consolidates the relevant evidence into a decision-oriented structure so that strategy sessions can move faster and with greater confidence.
Competitive Landscape: Leaders, Platforms, and Strategic Posture
The digital pathology market is shaped by a mix of established medical technology companies, specialized imaging manufacturers, and emerging AI-centric platforms. Competitive intensity is rising as organizations race to secure cleared workflows, expand integration capabilities, and lock in laboratory customers through platform stickiness. Our research profiles the companies that are setting the pace in 2026 and explains how their strategic postures influence market structure.
Several incumbents are competing around end-to-end diagnostic ecosystems. Koninklijke Philips N.V. continues to emphasize its IntelliSite Pathology Solution as a connected offering spanning scanners, image management, and AI-driven workflow tools intended to support primary diagnosis and telepathology. Leica Biosystems Nussloch GmbH, operating under Danaher Corporation, positions its Aperio GT series scanners alongside integrated digital pathology management software designed for anatomic pathology workflows. Hamamatsu Photonics K.K. maintains a strong footprint through its NanoZoomer series slide scanners and complementary image management solutions, reinforcing the importance of hardware-to-software continuity in laboratory adoption. F. Hoffmann-La Roche Ltd. advances its VENTANA DP series scanners and the Roche Digital Pathology Dx system with a specific focus on in-vitro diagnostic use, highlighting the increasing significance of cleared diagnostic intent in commercial messaging.
Alongside these hardware-centric leaders, platform and AI-focused companies are reshaping how laboratories think about computational pathology. Proscia Inc. provides the Concentriq enterprise platform with AI-powered tools oriented toward cancer diagnostics and workflow optimization, positioning software orchestration as a core value driver. PathAI Inc. offers the AISight Dx cloud-native image management and AI platform, which has been cleared for primary diagnosis, reflecting the broader push toward cloud-native infrastructure and regulatory-validated decision support. Indica Labs advances its HALO AP Dx enterprise digital pathology platform alongside AI tools cleared for primary diagnosis, reinforcing the trend toward consolidated enterprise deployments. Other notable participants include Sectra AB with digital pathology imaging and management solutions integrated with scanners for clinical workflows, Tribun Health with its CaloPix image management system and web-based platform incorporating AI applications, Epredia through its digital pathology scanners and image management software, and INFINITT Healthcare Co., Ltd. with its web-based INFINITT DPS viewing and management system cleared for primary diagnosis.
Strategic analysis in the report goes beyond company descriptions. It examines how product portfolios map to workflow requirements, where integration risk sits across scanner-to-platform combinations, how cleared indications affect competitive positioning, and which organizational capabilities are becoming table stakes. The research also captures recent market-moving events, including multiple FDA 510(k) clearances during 2025 across platforms such as PathAI’s AISight Dx, PathPresenter’s clinical viewer, Indica Labs’ HALO AP Dx paired with Leica’s Aperio GT 450 DX scanner, Roche’s VENTANA DP 600 scanner clearance, and INFINITT’s integration of the Hamamatsu NanoZoomer S360MD scanner in North America. These events are not isolated headlines; they signal how quickly cleared diagnostic workflows are accumulating and how that accumulation influences purchasing confidence.
Regulatory, Reimbursement, and Adoption Dynamics
Market growth in digital pathology is inseparable from the regulatory and reimbursement environment. The distinction between research use and diagnostic use remains a defining commercial boundary. According to Digital Pathology Association regulatory guidance, manufacturers may market digital pathology technology for research use only unless the FDA has issued a clearance or approval for a specific intended use. At the same time, several manufacturers have obtained FDA 510(k) clearances for digital pathology systems, scanners, and software as medical devices under product codes QKQ and PSY. Importantly, as of the most recent industry reporting referenced in our research, no manufacturer has yet received FDA approval of digital pathology technology for primary diagnosis, even as more than 1200 AI-enabled medical devices have received FDA clearance overall, with only a very small number authorized for primary histopathology use. This regulatory asymmetry creates both opportunity and risk: it accelerates monitored adoption while demanding careful product positioning and compliance discipline.
Whole Slide Scanner Market
Reimbursement dynamics are equally consequential. The College of American Pathologists reports that new digital pathology codes were added to the CPT manual effective January 1, 2024, with continued payer monitoring extending into 2026. For organizations evaluating adoption or expansion, the practical implication is that the financial case depends not only on workflow efficiency and diagnostic confidence, but also on the stability and evolution of coding and payment frameworks. The report addresses these dynamics as active variables rather than fixed assumptions, because reimbursement maturation can materially change the rate of institutional investment.
These dynamics shape the pace of adoption in three ways. First, they influence procurement timelines, since clinical-grade deployment requires clearer regulatory and reimbursement confidence than research-only setups. Second, they affect vendor selection criteria, as laboratories favor platforms that align with intended-use clarity and demonstrate compatibility with emerging coding structures. Third, they inform partnership strategy, because collaboration between scanner manufacturers, software vendors, and AI developers can shorten the path to integrated diagnostic workflows. Our analysis treats these factors as interconnected drivers, not isolated background noise.
Strategic Priority Areas for 2026
As the market moves deeper into the forecast period, the strategic questions facing organizations become more specific. Growth is no longer a matter of whether digital pathology will expand, but how value will be captured across hardware, software, AI-enabled workflow tools, and service models. The following areas merit close attention when formulating 2026 decisions:
- Platform interoperability and data continuity, because fragmented image management and incompatible scanner ecosystems slow adoption and increase total cost of ownership
- Regulatory positioning, since cleared indications and intended-use language increasingly influence procurement eligibility and competitive differentiation
- Workflow integration, particularly the alignment of digital pathology infrastructure with existing laboratory operations, information systems, and clinical decision pathways
- AI commercialization strategy, given the widening gap between AI device clearances in general and the limited number of authorizations applicable to primary histopathology use
- Regional and segment-specific deployment planning, as adoption rates, procurement structures, and reimbursement conditions differ materially across environments
- Capital timing, because the forecast period’s growth trajectory rewards early platform decisions while penalizing reactive or narrowly scoped investments
The report is designed to support these decisions with evidence rather than conjecture. It provides the market scale, structural analysis, and competitive intelligence that executives need to evaluate where to invest, what to prioritize, and how to interpret market signals as they evolve.
Digital Pathology Market
Why the Full Report Matters Now
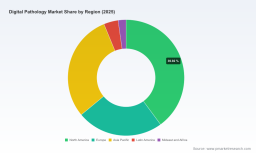
Executive summaries and high-level forecasts can establish direction, but they do not give organizations the segment-level clarity required for concrete planning. The complete PW Consulting Digital Pathology Market research goes further. It details regional market distribution, type-based demand splits between human and veterinary pathology, and application-level concentration across disease diagnosis, drug discovery, and training and education. It also quantifies market concentration dynamics, providing context on how competitive share is distributed among leading participants. These details are intentionally reserved for the full report because they directly inform budget allocation, geographic prioritization, product focus, and partnership evaluation.
For 2026 decision-making, that level of precision is not optional. A general growth narrative cannot tell a manufacturer whether its strongest opportunity lies in scanner adoption versus software-led workflow transformation. It cannot tell a laboratory operator whether to accelerate diagnostic-grade deployment or phase adoption around reimbursement maturation. It cannot tell an investor whether competitive advantage will come from platform consolidation, AI-enabled workflow differentiation, or regional execution speed. The full research is built to answer those questions with disciplined analysis and actionable structure.
Conclusion: Acting on Evidence in a Fast-Moving Market
The digital pathology market is expanding on the strength of durable clinical, technological, and operational forces, but the path to capture value is becoming more complex. Regulatory nuance, reimbursement evolution, AI clearance constraints, and platform integration requirements all influence who gains share and how quickly. PW Consulting’s latest market research provides the comprehensive view that leadership teams need to make informed decisions in 2026 and beyond.
If your organization is planning investments, evaluating competitive positioning, or preparing for the next phase of diagnostic digitalization, the full report offers the intelligence required to move from direction to execution. Detailed segmentation data, competitive profiling, regulatory context, and forward market sizing are available in the complete study. Access the full research to obtain the segmentation-level intelligence, company-level benchmarking, and strategic analysis needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Digital Pathology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


