



PW Consulting: Hollow Fiber Dialyzer Market to Reach $10.71M by 2032, Driven by 5.7% CAGR

Strategic Horizons: The Hollow Fiber Dialyzer Market Outlook 2026–2032
The global renal care landscape is entering a phase of disciplined expansion, driven by aging demographics, the rising prevalence of chronic kidney disease, and continuous innovation in extracorporeal purification technologies. For healthcare executives, supply chain strategists, and investment professionals, understanding the trajectory of the hollow fiber dialyzer market is no longer optional—it is a strategic imperative. Our latest market research provides a rigorous, multi-dimensional analysis of the sector, mapping historical performance against a forward-looking forecast window that extends through 2032. This article outlines the strategic architecture of the report, highlights the operational intelligence embedded within, and explains why these insights are essential for enterprise decision-making in 2026 and beyond.
Market Trajectory: Navigating a Mid-Growth Expansion Cycle
Over the past half-decade, the hollow fiber dialyzer sector has demonstrated steady, resilient revenue growth. Historical data from 2020 through 2025 reveals a consistent upward curve, with total market value advancing from approximately 5.5 billion USD to 7.26 billion USD. This historical run reflects stable procurement patterns, sustained clinical adoption, and incremental improvements in manufacturing efficiency. Looking ahead, our forecast model projects the market to reach 7.56 billion USD in 2026, with growth compounding steadily toward 8.54 billion USD by 2028 and continuing to 10.71 billion USD by 2032.
The forecast period is anchored by a compound annual growth rate of 5.7 percent, a trajectory that balances realistic demand expansion with structural headwinds and tailwinds. This rate is neither aggressive nor stagnant; rather, it reflects a market that is maturing but still capable of meaningful volume and value expansion. For strategic planners, this mid-growth profile suggests a landscape where competitive differentiation, operational scalability, and product-grade positioning will determine market capture more than broad macroeconomic swings. The report dissects this trajectory across multiple analytical lenses, ensuring that readers can separate cyclical fluctuations from structural shifts and calibrate their roadmaps accordingly.
Structural Segmentation: Where Value Accrues and How to Capture It
Segment-level analysis forms the analytical backbone of the report. The market is examined through three primary dimensions—product type, application setting, and geographic distribution—each offering distinct implications for pricing strategy, capacity planning, and channel development. Within the product architecture, the analysis contrasts low-flux and high-flux hollow fiber configurations, highlighting how membrane permeability, biocompatibility, and clearance performance shape clinical preference and procurement behavior. High-flux variants continue to command a larger share of the value pool, reflecting their alignment with contemporary dialysis protocols that prioritize middle-molecule removal and long-term patient outcomes.
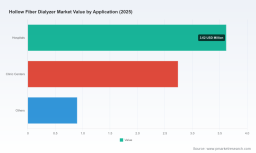
Application segmentation examines how procurement flows across hospital networks, dedicated clinic centers, and other care environments. The report maps the operational characteristics of each setting, from volume throughput and sterilization logistics to procurement cycle lengths and reimbursement alignment. Geographic analysis, meanwhile, provides a regional snapshot of demand intensity and growth readiness. North America and Europe maintain substantial demand footprints, supported by established reimbursement pathways and mature clinical infrastructure. Asia Pacific represents a high-potential corridor where expanding healthcare access, rising treatment volumes, and localized manufacturing are reshaping competitive dynamics. Latin America and the Middle East and Africa contribute complementary demand streams, with growth trajectories closely tied to capacity building and import-dependent supply chains.
Importantly, the report does not reduce these segments to static percentages. Instead, it frames them as strategic zones where pricing elasticity, channel access, and product-grade positioning can be optimized. Readers will gain a clear understanding of which segment characteristics create margin opportunities, which require volume-driven playbooks, and where cross-segment synergies can be engineered through portfolio architecture and supply chain design.
Competitive Architecture: The Tenacity of an Oligopolistic Core and the Rise of Contenders
The hollow fiber dialyzer market exhibits a concentrated competitive structure. Our analysis captures a combined market share for the leading three participants at approximately 68.5 percent, with the top five entities collectively accounting for around 75 percent of total revenue. This concentration underscores the importance of scale, regulatory navigation, and sustained R&D investment in maintaining market positioning. At the same time, the remaining share dispersion leaves meaningful room for specialized entrants, regional manufacturers, and technology-focused innovators to capture niche demand or differentiated product niches.
The report profiles the core competitive set in detail. Nipro Corporation continues to advance its high-flux polysulfone and cellulose triacetate portfolios, including the ELISIO™-HX and Cellentia™-H families, which are engineered for both chronic and acute hemodialysis applications. Baxter International Inc. reinforces its presence through polyethersulfone high-flux configurations such as the HiF series and Revaclear, emphasizing consistency and broad compatibility across dialysis platforms. Fresenius Medical Care AG & Co. KGaA maintains a widely deployed polysulfone-based Optiflux series, serving hospital and home hemodialysis environments with established clinical familiarity. Toray Medical Co., Ltd. contributes the Filtryzer series, combining PMMA and polysulfone materials with advanced biocompatibility and adsorption characteristics. B. Braun Melsungen AG focuses on polysulfone hollow fiber designs that emphasize reduced blood cell trauma and strong biocompatibility for extracorporeal procedures. Asahi Kasei Medical Co., Ltd. develops advanced polysulfone and related high-flux configurations targeting improved clearance performance. Nikkiso Co., Ltd. integrates high-flux hollow fiber dialyzers with its broader dialysis systems, supporting chronic kidney disease therapy workflows. On the regional supply frontier, Jiangxi Sanxin Medtec Co., Ltd. produces disposable polysulfone and PC high-flux options, including PC High Flux series and PES membranes, while LEPU Medical Technology Co., Ltd. expands its PP series and OCI-HD line across low-flux to high-flux polysulfone configurations. Althin Medical AB rounds out the competitive landscape with capillary hollow fiber designs such as the A-15 HEMODIALYZER, cleared for hemodialysis use.
This competitive profile is not presented as a static roster. The report evaluates each entity’s strategic posture, product-grade positioning, regional reach, and innovation cadence, enabling readers to assess where incumbency advantages are strongest and where disruption is most plausible. Strategic planners will find actionable guidance on partnership opportunities, competitive response playbooks, and whitespace identification.
Industry Dynamics and Regulatory Tailwinds Shaping 2026 Strategy
Market outcomes are ultimately governed by the interaction of technology, regulation, reimbursement, and supply economics. The report integrates these forces into a cohesive dynamics framework, drawing on current regulatory standards, reimbursement behavior, raw material trends, and sterilization requirements. ISO 8637-1 continues to define essential performance expectations for hollow fiber haemodialysers, including blood area integrity testing, establishing a baseline for compliance and quality assurance across manufacturers. At the same time, FDA 510(k) clearance pathways require demonstrable substantial equivalence for new dialyzer designs, encompassing both membrane and potting materials. This regulatory architecture rewards manufacturers that can streamline design verification, maintain robust documentation, and align innovation with established equivalence frameworks.
Reimbursement conditions remain a critical enabler of adoption. Medicare and commercial insurance programs provide adequate coverage for single-use hollow fiber dialyzers, reinforcing procurement stability and enabling growth in home hemodialysis settings. This reimbursement backdrop supports service expansion strategies and encourages manufacturers to design products that fit both facility-based and decentralized care models. On the supply side, polysulfone and polyethersulfone raw material costs have declined between 8 and 12 percent over the past five years, reflecting expanded production capacity and improved procurement economics. These cost dynamics improve margin potential and lower barriers to product-grade upgrades, allowing companies to invest in higher-performance membranes without proportionally escalating cost structures.
Sterilization and shelf-life considerations also shape product design and logistics planning. High-flux hollow fiber dialyzers are typically gamma or moist heat sterilized for single-use application, with standard shelf-life expectations around three years to preserve non-pyrogenic status. This parameter influences inventory strategy, distribution planning, and packaging decisions, especially for manufacturers operating across multiple regions with differing cold-chain and storage norms. The report translates these technical and regulatory variables into operational implications, helping readers evaluate where process optimization can yield cost advantages and where compliance requirements may constrain speed-to-market.
Hollow Fiber Dialyzer Market
Recent Developments Illuminating Competitive Velocity
Recent corporate activity underscores how quickly the competitive tempo is shifting. In early 2026, Outset Medical, Inc. secured FDA clearance for its next-generation Tablo hemodialysis system, the first to incorporate the strictest cybersecurity guidance, supporting the use of hollow fiber dialyzers within connected systems. This milestone signals a broader convergence between device hardware and digital integration, a trend with direct implications for product compatibility, data workflows, and downstream service models. In mid-2025, Byonyks received FDA clearance for its X1 automated peritoneal dialysis cycler, enabling integration with hollow fiber dialyzers in home therapy settings and reinforcing the push toward decentralized care.
On the incumbent side, Fresenius Medical Care obtained FDA approval in 2024 for expanded high-flux membrane production capacity and next-generation disposable dialyzers with markedly reduced toxin retention. Nipro Corporation introduced enhanced polysulfone hollow fiber structures that improved ultrafiltration consistency and increased compatibility with a significant share of automated dialysis systems. Baxter International advanced biocompatible membrane dialyzers that reduced inflammatory response indicators and improved efficiency in extended treatment sessions. These developments illustrate how competitive advantage is increasingly tied to membrane engineering, workflow compatibility, and clinical outcome differentiation. The report situates each milestone within a broader competitive narrative, helping readers distinguish between isolated product announcements and structural shifts in capability and positioning.
Inside the Report: Content Architecture Built for Decision-Makers
The full market research is designed to translate complex data into executable strategy. It opens with a comprehensive market overview that establishes baseline definitions, scope boundaries, and methodological transparency. From there, the analysis moves into historical performance mapping, showing how the market evolved through 2025 and what that evolution reveals about underlying demand drivers. The forecast section projects revenue pathways through 2032, accompanied by scenario commentary that helps leadership test vulnerability to input cost changes, regulatory adjustments, and demand shocks.
Dialyzer Market
Segment chapters provide granular views of type, application, and regional dynamics without overwhelming readers with noise. Each chapter connects segment behavior to strategic choices—where to invest in capacity, how to structure pricing, and which customer segments warrant tailored product configurations. The competitive landscape section delivers company profiles, positioning maps, and development timelines, enabling benchmarking and response planning. A dedicated dynamics chapter synthesizes regulatory, reimbursement, raw material, and sterilization factors into an integrated framework, showing how each variable influences cost, speed, and market access.
The report also incorporates recent corporate developments, FDA clearances, product launches, and production expansions, tying them back to market-level implications. For executives who need to brief cross-functional teams, the structure supports quick extraction of relevant insights, while for analysts who require depth, the underlying segmentation logic and trend framing provide a reliable foundation for further modeling. Visitors to the source page will find the complete dataset, detailed segmentation charts, and the full competitive intelligence suite that cannot be summarized in a single overview.
Strategic Implications for 2026 Enterprise Decision-Making
For organizations operating in or adjacent to the renal care sector, the 2026 decision environment demands clarity on three fronts: demand durability, competitive exposure, and operational leverage. The market’s projected growth path suggests durable demand, but durability alone does not guarantee capture. The concentrated competitive structure means that incumbents will continue to defend share through scale, regulatory compliance, and incremental product enhancements. At the same time, the raw material cost environment and reimbursement stability create conditions where well-executed entrants and regional players can expand footprint through differentiated membrane technology, application-specific configurations, and channel partnerships.
Enterprise leaders should use the report to stress-test portfolio mix, assess where high-flux demand is most resilient, and determine whether home therapy and clinic-center expansion represent authentic growth vectors in their target geographies. Supply chain and procurement teams can use the segmentation and dynamics analysis to align inventory planning with sterilization requirements, shelf-life parameters, and regional distribution realities. Commercial teams can leverage competitive profiles to refine positioning, anticipate competitor moves, and identify customer segments where compatibility, clearance performance, or biocompatibility offer tangible purchase advantages.
Conclusion: From Insight to Action
The hollow fiber dialyzer market is expanding within a disciplined growth corridor, shaped by clinical demand, regulatory rigor, reimbursement stability, and continuous membrane innovation. The strategic question for 2026 is not whether the market will grow, but how organizations will position themselves to convert that growth into sustainable share, margin, and capability. Our market research is built to support that conversion, offering a structured, data-grounded view of where value is created and how competitive advantage can be protected or extended.
To access the full segmentation breakdown, complete regional and application analysis, detailed company profiles, and the comprehensive forecast model, visit the source page for the Hollow Fiber Dialyzer Market report. The complete intelligence suite provides the depth required to translate market-wide trends into precise, defensible action plans for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Hollow Fiber Dialyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


