



PW Consulting Report: PC Gaming Peripheral Market to Hit $5.63B by 2032, 5.3% CAGR Through 2032

The 2026 PC Gaming Peripheral Market: Strategic Intelligence for Corporate Decision-Making
The global PC gaming peripheral market stands at a critical inflection point. As hardware capabilities converge with evolving player expectations, competitive differentiation is no longer driven by incremental feature upgrades alone. It requires a rigorous understanding of demand shifts, supply chain vulnerabilities, pricing architecture, and the strategic positioning of incumbents and challengers. Our newly published PC Gaming Peripheral Market research report delivers exactly that: a comprehensive, forward-looking intelligence framework designed to support executive decision-making throughout 2026 and beyond.
Drawing on a historical analysis spanning 2020 through 2025 and a detailed forecast horizon extending to 2032, this study maps the structural forces that will shape revenue allocation, product roadmaps, regional expansion strategies, and procurement planning. The market has demonstrated consistent resilience, with total industry revenue reaching approximately 3,924.19 million USD in 2025 and climbing to an estimated 4,176.38 million USD in 2026. Over the full forecast period, the sector is projected to expand at a compound annual growth rate of 5.3 percent, ultimately approaching 5,633.12 million USD by 2032. These figures are not merely retrospective indicators. They represent a baseline against which product portfolio investments, channel partnerships, and geographic prioritization must be stress-tested.
This report is engineered for leaders who require actionable clarity rather than high-level speculation. Below, we outline the strategic architecture of the study, the competitive contours it maps, and the macroeconomic and regulatory pressures that will define market execution in 2026.
Why This Research Matters for 2026 Strategic Planning
Enterprise decisions made in 2026 will be judged against a market environment defined by three simultaneous pressures: shifting consumption patterns across gaming modalities, tightening component availability, and intensifying competition among established peripheral manufacturers. Executive teams cannot afford to treat these dynamics as isolated risks. They must be modeled together.
Our analysis frames the market as a system of interdependent variables. Revenue growth, for instance, is not distributed uniformly across usage contexts or hardware categories. Instead, value creation is increasingly concentrated in segments where performance fidelity, latency optimization, and creator-oriented ergonomics intersect. The report dissects these intersections without relying on surface-level categorization, enabling strategy teams to identify where incremental R&D spend will yield disproportionate returns and where legacy product lines may face structural decline.
Equally important, the forecast model accounts for the macroeconomic and regulatory turbulence that has reshaped electronics supply chains over the past twelve months. Raw material constraints, trade policy adjustments, and semiconductor input costs have moved from peripheral concerns to central planning variables. The study integrates these factors into scenario-based guidance, allowing procurement, manufacturing, and pricing teams to evaluate margin sensitivity under multiple supply disruption pathways.
For organizations evaluating market entry, portfolio consolidation, or regional scaling, the report functions as a decision-validation instrument. It does not simply describe what is happening; it clarifies where strategic leverage exists and which assumptions require continuous monitoring as the forecast window progresses.
Inside the Report: Operational Intelligence Built for Execution
The study is structured to move seamlessly from macro market architecture to execution-level detail. Rather than presenting static tables in isolation, the analysis embeds quantitative baselines within strategic narratives that can be directly translated into planning workflows.
The core deliverables include:
PC Gaming Peripheral Market
Gaming Mouse & Keyboards Market
- Market sizing and trajectory modeling anchored in a transparent historical baseline and extended across a multi-year forecast window, with explicit treatment of the 5.3 percent compound growth pathway and its inflection points.
- Demand decomposition across hardware categories , including headsets, mice, keyboards, gamepads, and ancillary peripheral subcategories, with attention to performance segmentation, pricing tiers, and adoption velocity.
- Application-linked consumption mapping that distinguishes how revenue flows across competitive esports environments, casual gaming usage, and streaming and content creation workflows, highlighting divergent feature priorities and purchase cycles.
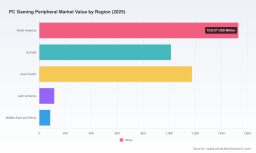
- Regional demand architecture that captures where consumption is concentrated, how growth momentum differs across markets, and which geographic corridors present the most viable expansion candidates under current economic conditions.
- Competitive benchmarking and strategic positioning analysis that evaluates brand differentiation, performance claims, ecosystem lock-in potential, and product cadence among the leading manufacturers shaping market direction.
- Supply-side and regulatory context integration , connecting component sourcing pressures, export control developments, and tariff-related cost shifts to practical implications for procurement timing, input substitution, and margin management.
Each section is written to support cross-functional use. Product managers can extract priority feature sets and segmentation logic. Commercial leaders can align channel strategy with regional demand intensity. Finance and operations teams can use the scenario framing to model downside exposure from input cost volatility. This breadth ensures that the report does not sit idle as a reference document; it becomes an active input to quarterly planning, capital allocation, and market-response strategy.
Competitive Landscape: Positioning, Product Cadence, and Strategic Signal
The market’s competitive structure is defined by a concentrated set of influential players, each pursuing distinct value propositions while operating within the same performance-driven consumer expectations. The report examines the strategic posture of several core companies whose product decisions are actively shaping category standards and buyer expectations.
Corsair Gaming Inc., headquartered in Milpitas, California, continues to anchor its offering around high-performance keyboards, mice, headsets, gaming chairs, and custom PC components aimed at both gamers and creators. Its portfolio strategy emphasizes performance coherence across input devices and supporting ecosystem elements, giving it relevance in segments where system-level integration matters.
Razer Inc., based in San Jose, California, directs its peripheral lineup toward esports-optimized gaming mice, keyboards, headsets, and accessories centered on low-latency performance. The company’s product narrative is tightly coupled to competitive play requirements, making responsiveness and precision central to its market identity.
Logitech International S.A., headquartered in Lausanne, Switzerland, maintains a broad gaming peripheral presence through its Logitech G series, spanning gaming mice, keyboards, headsets, and controllers designed for both competitive and casual players. Its scale and brand recognition provide a strong platform for cross-segment appeal, while its product roadmap increasingly reflects nuanced performance segmentation.
SteelSeries A/S, operating from Copenhagen, Denmark, focuses its lineup on Arctis headsets, Apex keyboards, and Rival mice optimized for competitive esports. Its positioning reflects a disciplined emphasis on tournament-grade performance characteristics and player-facing comfort features that align with intensive usage cycles.
Turtle Beach Corporation, based in San Diego, California, has extended its footprint through Command Series keyboards, mice, and gaming audio peripherals designed for PC and console crossover appeal. This cross-platform orientation broadens its addressable audience while reinforcing its audio-centric heritage.
HyperX, a division of Kingston Technology Corporation and headquartered in Fountain Valley, California, contributes to the market through Cloud series headsets, keypads, and accessories focused on immersive PC gaming audio. Its product identity has long been associated with comfort, durability, and audio consistency, giving it a distinctive place within the broader headset and accessory conversation.
These companies do not compete in a vacuum. Their product announcements, positioning choices, and feature priorities send clear market signals. Recent developments in 2026 illustrate how rapidly the category is evolving. In April 2026, Turtle Beach Corporation unveiled the Command Series ecosystem of PC gaming keyboards and mice at multiple price points, emphasizing high-speed performance and precision for gaming and content creation. Logitech International S.A. announced the G512 X gaming keyboard with TMR analog switches, mechanical options, and customizable layouts intended to enable tuned performance in PC gaming. Corsair Gaming Inc. introduced the Night Sword B2 wireless gaming mouse at Computex, highlighting extended battery life and high-performance PC gaming input.
The strategic implication is consistent: competition is being fought at the level of latency, switch technology, wireless efficiency, ergonomic tuning, and ecosystem breadth. Our report translates these announcements into competitive intelligence by assessing what each move reveals about underlying product strategy, target segmentation, and potential market-share reallocation.
Market Dynamics in 2026: Regulation, Materials, and the Cost of Precision
The trajectory of the PC gaming peripheral market cannot be separated from the environment in which its components are sourced and manufactured. In 2026, supply-side constraints and trade policy have become first-order planning considerations rather than background noise.
One of the most consequential supply dynamics involves gallium and related materials. China accounted for 99 percent of the world’s low-purity primary gallium supply, and export controls on gallium, germanium, and related materials have affected semiconductor and electronics components across multiple downstream categories. Compounding this, China imposed an outright prohibition on exports of gallium, germanium, antimony, and superhard materials to the United States effective December 2024, with the ban suspended until November 2026 while licensing remains active. For peripheral manufacturers, this creates a planning environment in which input availability, approval workflows, and sourcing diversification must be evaluated well ahead of product build cycles.
Simultaneously, semiconductor-related trade measures have introduced additional cost variability. In January 2026, the U.S. Department of Commerce implemented a 25 percent ad valorem tariff on specified advanced semiconductor chips, affecting upstream components for peripheral electronics. This development followed a broader Section 232 investigation initiated in April 2025 into semiconductor imports and manufacturing equipment, with a report issued in December 2025 and 25 percent tariffs applied in January 2026. The practical consequence is that precision electronics used in high-performance peripherals face an elevated and potentially fluid cost structure, which can influence pricing architecture, margin planning, and the timing of new product introductions.
China’s broader rare earth export controls have also extended into the supply chain. In January 2026, controls were expanded to samarium, gadolinium, and lutetium compounds, raising costs for high-temperature magnets used in precision components across electronics supply chains. Since these materials support performance-critical mechanisms inside advanced peripheral hardware, even modest cost escalation can affect the economics of feature-rich designs.
These dynamics do not just alter short-term input costs; they reshape the strategic calculus of product development. Companies must decide whether to absorb cost pressure, pass it through selectively, redesign around constrained materials, or accelerate supplier diversification. The report integrates these considerations into a market dynamics framework that links raw material exposure, regulatory timing, and component sourcing strategy to commercial outcomes.
Concentration in the competitive structure adds another layer of context. The market remains moderately fragmented at the top, with the top three firms holding approximately 28.0 percent of revenue and the top five firms accounting for about 34.0 percent. This concentration level indicates that while leading brands exert meaningful influence, there is still room for differentiated positioning, niche performance propositions, and regional or application-specific gains. The report examines how this concentration interacts with product cadence, brand equity, and channel strength to determine which players can defend share and which vulnerabilities may open under supply or pricing stress.
What Decision-Makers Will Gain
The objective of this study is to convert complex market signals into a clear strategic lens. Readers will gain a stronger ability to:
- Evaluate which hardware categories and application segments present the most durable growth opportunities through 2032.
- Identify where performance specifications, input reliability, and wireless efficiency are becoming table stakes rather than differentiators.
- Understand how regulatory and materials-related pressures may affect cost structures and product launch timing across 2026 and the surrounding forecast period.
- Assess the strategic posture of key competitors and interpret recent product launches as signals of broader market direction.
- Align regional expansion assumptions with where demand intensity and growth momentum are most likely to persist.
In practical terms, the report is designed to reduce uncertainty in portfolio planning, sharpen competitive response timing, and support more resilient procurement and pricing decisions. It gives executive teams a shared factual foundation on which to debate entry, expansion, consolidation, and innovation priorities.
Obtain the Full Strategic Blueprint
The overview presented here captures the architecture of the analysis and the strategic questions the study is built to answer. It does not expose the detailed segmentation values, regional splits, application-level revenue distribution, or category-specific market sizing that form the analytical core of the report. Those findings are where the most precise planning insights reside, and they are reserved for the full version of the study.
For teams preparing product strategy, commercial planning, sourcing decisions, or competitive positioning for 2026, the complete report provides the depth required to move from directional confidence to execution-ready intelligence. We invite strategy, product, and commercial leaders to access the full PC Gaming Peripheral Market research to obtain the granular forecasts, competitive benchmarks, and scenario analysis needed to support high-stakes decisions throughout the forecast window.
For detailed analysis of this topic, please visit the official page: PC Gaming Peripheral Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


