



PW Consulting Report: 2-Mercaptoethanol Market Forecasts CAGR of 5.5% from 2026-2032

Navigating the 2-Mercaptoethanol Market: Strategic Intelligence for 2026 and Beyond
The chemical industry landscape in 2026 is defined by a complex interplay of supply chain realignment, regulatory tightening, and strategic capacity expansions. For stakeholders involved in the production and utilization of 2-Mercaptoethanol, understanding these shifts is not merely an academic exercise but a critical component of risk management and growth planning. Our latest market research publication serves as a comprehensive guide through this evolving terrain, offering the granularity needed to make informed decisions in a sector characterized by volatility and specialized demand.
2-Mercaptoethanol Market
This report is designed for senior leadership teams, procurement strategists, and market entry analysts who require more than surface-level data. By dissecting the historical performance and future trajectory of the 2-Mercaptoethanol market, we provide a framework for anticipating supply constraints, pricing fluctuations, and regulatory impacts. The analysis spans a historical review from 2020 through the base year of 2025, extending into a robust forecast period reaching to 2032. This long-view approach allows organizations to align their capital allocation and operational strategies with the realistic demands of the coming decade.
Market Trajectory and Historical Context
The overarching narrative of the 2-Mercaptoethanol market over the past half-decade reflects a period of contraction followed by a poised recovery. Historical data indicates that market revenue experienced a downward trend from 2020 through 2025. This compression was driven by a combination of factors including global economic headwinds, shifts in downstream demand, and adjustments in production capacities across key manufacturing hubs. Despite these challenges, the market is now positioned at an inflection point.
Looking forward, the forecast period from 2026 to 2032 suggests a return to growth. The market is projected to expand at a Compound Annual Growth Rate of 5.5 percent during this interval. This rebound is not uniform but is instead underpinned by specific industrial recoveries and strategic investments in chemical infrastructure. For decision-makers, this growth rate signals a timely opportunity to reassess supply agreements and vertical integration strategies. The transition from a contracting market to an expanding one requires a nuanced understanding of where the demand is originating and which production nodes are becoming reliable.
Revenue figures throughout the analysis are denominated in USD Millions, providing a standardized metric for comparing investment opportunities across different regions and sectors. The scale of the market, while specialized, possesses sufficient liquidity to attract significant industrial interest. Understanding the total addressable market size without getting lost in fragmented data allows executives to gauge the potential return on investment for new capacity or distribution networks.
Segmentation and Demand Drivers
A critical value of this research lies in its detailed segmentation analysis. We have broken down the market by region, type, and application to reveal where the actual value creation is occurring. However, the strategic insight goes beyond simple percentage splits. It involves understanding the structural reasons behind these divides.
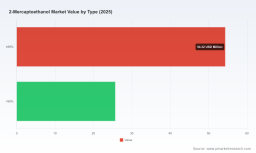
In terms of product purity, the market distinguishes between high-grade and standard grades. The premium segment, often defined by purity levels of 99 percent or higher, commands a significant share of the revenue. This reflects the stringent requirements of downstream applications where impurities can compromise product performance. Conversely, the lower purity segment serves industrial uses where cost efficiency is paramount. The balance between these two types dictates pricing power and margin potential for manufacturers.
Application-wise, the demand is heavily skewed towards specific industrial processes. PVC production remains a cornerstone consumer of 2-Mercaptoethanol, utilizing the chemical primarily for stabilizers and intermediates. Alongside this, the polymer and rubber sectors, along with food industry applications and water treatment processes, contribute to the diverse demand base. Agrochemicals and other specialty uses round out the consumption profile. Each of these segments faces its own regulatory and economic pressures. For instance, changes in PVC manufacturing standards or shifts in agricultural chemical regulations can ripple through the 2-Mercaptoethanol supply chain. Our report details how these application segments are evolving individually and collectively.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While the aggregate data shows a global footprint, the density of consumption and production varies significantly. Asia Pacific represents a substantial portion of the global volume, reflecting the region's heavy industrial base. North America and Europe maintain strong positions driven by high-specification industrial and laboratory needs. Emerging regions in Latin America and the Middle East and Africa offer incremental growth opportunities. The report elaborates on the logistical and tariff implications of these regional distributions without exposing the exact volume splits, encouraging a deeper dive into the regional chapters for specific procurement planning.
Competitive Landscape and Strategic Positioning
The competitive environment for 2-Mercaptoethanol is characterized by a mix of large-scale chemical integrators and specialized laboratory suppliers. Market concentration metrics indicate that the top three players hold a combined share of approximately 35 percent, while the top five extend this to 45 percent. This level of concentration suggests that while there is room for niche players, the bulk of industrial supply is controlled by established entities with significant capital and technical resources.
Key industry participants include major chemical corporations such as Chevron Phillips Chemical and BASF SE. Chevron Phillips Chemical, headquartered in The Woodlands, Texas, operates as an active producer and supplier of 2-Mercaptoethanol for PVC stabilizers, agrochemical intermediates, corrosion inhibitors, and oilfield applications. Their integration into the oilfield and PVC supply chains provides them with a stable demand baseline. Similarly, BASF SE, based in Ludwigshafen, Germany, is a pivotal supplier for PVC production, organotin stabilizers, crop protection, and oilfield chemicals. BASF's operational footprint was notably strengthened when their new 10,000 metric tons per year 2-Mercaptoethanol production plant at the Ludwigshafen Verbund site achieved regular operations in the fourth quarter of 2021. This capacity addition significantly altered the supply dynamics in the European region, providing a benchmark for production efficiency and scale.
On the laboratory and research side, the market is served by specialized suppliers including Molecular Toxicology Inc., Sigma-Aldrich International GmbH, Thermo Fisher Scientific, Carl Roth GmbH + Co. KG, and Cambridge Isotope Laboratories. These entities, located across the USA and Germany, focus on providing laboratory-grade 2-Mercaptoethanol for research use only. Their role is critical for R and D sectors, including molecular biology and toxicology studies, where purity and certification are the primary purchase drivers rather than bulk industrial volume. Companies like Sunion Chemical and Hefei TNJ Chemical Industry in China also maintain a presence as active manufacturers for industrial and specialty applications, adding a layer of competitive pressure on pricing and availability in the Asian supply chain.
Strategic interactions among these players involve not just price competition but also securing raw material streams and navigating regulatory compliance. For a new entrant or an existing player looking to expand, understanding the barrier to entry in both the industrial and laboratory segments is vital. The report provides a detailed competitive benchmarking section that evaluates these companies based on capacity, geographic reach, and product portfolio depth.
Regulatory Dynamics and Production Technology
Regulatory compliance remains a defining factor in the 2-Mercaptoethanol market, particularly for entities operating within or exporting to the European Union. The chemical is subject to REACH Annex XVII R3 restriction. This regulation imposes specific usage limits and safety requirements that can impact formulation choices and market access for downstream customers. Compliance costs and the administrative burden of adhering to these restrictions create a moat for larger producers who can absorb regulatory overhead, while potentially squeezing out smaller operators who lack robust compliance infrastructure. Our analysis examines how these regulations are reshaping the competitive landscape and influencing procurement decisions in regulated markets.
On the production side, the industrial synthesis of 2-Mercaptoethanol typically involves the reaction of ethylene oxide with hydrogen sulfide. This process utilizes thiodiglycol and zeolites as catalysts. The efficiency of this reaction, along with the availability and cost of ethylene oxide and hydrogen sulfide, directly impacts production margins. Fluctuations in the petrochemical feedstock market can transmit volatility to 2-Mercaptoethanol pricing. Furthermore, advancements in catalytic technology and process optimization are areas of continuous development. Manufacturers investing in more efficient 촉매 systems or waste reduction technologies may gain a cost advantage. The report delves into the technical nuances of production methods and how they correlate with regional cost structures and environmental standards.
Strategic Implications for 2026 Decision Makers
For organizations planning their strategy in 2026, the insights provided in this market research report translate into several actionable imperatives. First, supply chain resilience must be prioritized. Given the concentration of production among a few key players and the regulatory complexities in regions like Europe, relying on a single source of supply introduces significant risk. Diversification across geographies, balancing between Asian industrial producers and Western integrated chemical manufacturers, can mitigate disruption risks.
Second, pricing strategy needs to be dynamic. The shift from a contracting market to a growing one implies that pricing power may gradually return to suppliers. However, this is contingent on the ability to meet specific purity standards and regulatory requirements. Businesses must evaluate whether they are positioned to capture the premium segment or if they should compete on volume in the standard grade market. Understanding the margin implications of the purity segmentation is essential for portfolio management.
Third, investment in R and D or capacity expansion should be timed against the forecast growth trajectory. The projected CAGR of 5.5 percent suggests steady demand growth, but capital allocation should be targeted towards the applications and regions showing the highest momentum. For instance, sectors related to PVC and organotin stabilizers may require different investment horizons compared to laboratory-grade supply chains. The long-term forecast to 2032 helps in smoothing out short-term volatility and identifying genuine long-term trends versus temporary fluctuations.
Finally, regulatory intelligence is non-negotiable. Compliance with regulations such as REACH Annex XVII R3 is not just a legal requirement but a market access prerequisite. Companies must assess their exposure to restricted substances and prepare for potential tightening of norms. The report includes a dedicated section on regulatory trends, helping stakeholders anticipate changes that could affect product formulation or export eligibility.
Conclusion
The 2-Mercaptoethanol market in 2026 stands at a crossroads. While historical data reflects a period of contraction, the forward-looking indicators point to recovery and growth driven by specific industrial applications and strategic capacity additions. Success in this environment requires a granular understanding of segment dynamics, competitive positioning, and regulatory frameworks.
Mercaptoacetic Acid Market
This market research report offers the depth and breadth required to navigate these complexities. It provides the macroeconomic context while drilling down into the operational details that matter for day-to-day decision-making. However, the full spectrum of data, including precise regional volume splits, exact application revenue contributions, and detailed company profiling, is reserved for the comprehensive study. To fully equip your organization with the intelligence needed to capitalize on the opportunities outlined here and mitigate the associated risks, we invite you to access the complete report via our source webpage. There you will find the detailed tables, charts, and strategic analyses that form the backbone of this executive summary.
Navigate the complexities of the 2-Mercaptoethanol market with confidence. Access the full detailed intelligence to secure your strategic advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: 2-Mercaptoethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


