



PW Consulting: Geothermal Heat Pump Market to Hit $228M by 2032 at 6.5% CAGR

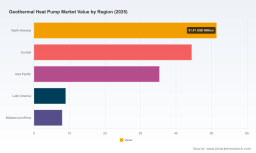
Geothermal Heat Pump Market 2026–2032: Strategic Intelligence for the Energy Transition
The global transition toward decarbonized building infrastructure has placed geothermal heat pumps at the center of HVAC innovation and investment strategy. After five years of consistent expansion, the industry now stands at a critical inflection point. Over the historical period from 2020 to 2025, total market revenue climbed steadily from approximately 112.34 million USD to 148.0 million USD, reflecting sustained demand across residential, commercial, and industrial sectors. Our latest comprehensive market study projects this momentum to continue through the forecast window of 2026 to 2032, with a compound annual growth rate of 6.5 percent and a projected market valuation exceeding 228.0 million USD by the terminal year. These figures represent more than incremental growth; they signal a structural realignment of heating and cooling procurement driven by regulatory mandates, incentive architectures, and technological maturation.
For executive teams, capital allocators, and operational leaders navigating the 2026 landscape, this research report serves as a decision-grade intelligence asset. The following overview outlines the strategic scope, analytical architecture, and competitive context embedded within the study, demonstrating how the findings can be operationalized for product roadmapping, market entry planning, supply chain optimization, and competitive positioning.
Geothermal Heat Pump Market
Macro Trajectory and Forward-Looking Market Signals
Market expansion in the geothermal heat pump sector is no longer a linear extension of past performance. It is increasingly shaped by intersecting forces: tightening refrigerant compliance timelines, evolving federal and state-level tax credit frameworks, and rising capital sensitivity around imported HVAC components. The baseline trajectory from 2025 through 2032 indicates consistent year-over-year revenue progression, with notable acceleration anticipated as commercial retrofitting programs scale and residential deployments benefit from expanded incentive eligibility windows that extend through 2032.
The competitive landscape remains moderately concentrated, with the top three firms collectively commanding a significant share of total industry revenue and the top five firms extending that footprint further. This concentration underscores the importance of understanding not only market sizing but also the strategic maneuvers that allow emerging players and regional specialists to capture differentiated value pools. The report dissects these structural dynamics with granular attention to pricing behavior, channel strategies, and regional deployment pacing, enabling stakeholders to anticipate where market share will migrate over the next several years.
Report Architecture and Actionable Content Framework
This study is designed as an execution-oriented reference rather than a static sizing exercise. The analytical framework is organized around three core pillars, each structured to translate high-level industry trends into tangible corporate strategies:
- Segmentation and Demand Mapping: The report categorizes the market across technology configurations, application verticals, and geographic demand centers. Rather than presenting isolated percentage breakdowns, the analysis connects each segment to underlying adoption drivers, including building stock characteristics, drilling and installation economics, refrigerant transition readiness, and regional policy environments. This approach enables readers to identify which end-use environments are experiencing the fastest adoption inflection and which are facing friction points that require strategic mitigation.
- Competitive Positioning and Corporate Strategy Evaluation: Profiles of leading manufacturers and specialized operators are synthesized with recent product launches, partnership announcements, and standardization milestones. The analysis moves beyond corporate descriptors to examine strategic intent: where companies are reallocating R&D resources, how they are adapting product architectures to meet low-GWP refrigerant requirements, and which commercial models are proving most effective in scaling residential and commercial deployments.
- Regulatory, Incentive, and Cost-Driver Analysis: Policy and reimbursement frameworks are evaluated as strategic variables rather than background conditions. The study traces how tax credit structures, efficiency certification pathways, and refrigerant phase-out schedules are reshaping project economics. Attention is also given to upstream cost pressures stemming from tariffs on critical HVAC components, including compressors, heat exchangers, and refrigerants, which are influencing margin structures and sourcing strategies across North America and Europe.
Each section is cross-referenced to provide a unified view of how market sizing, competitive behavior, and external policy signals interact. Executives can use this integrated lens to stress-test product portfolios against upcoming compliance deadlines, evaluate partnership opportunities in high-growth deployment corridors, and model margin scenarios under varying component cost and incentive realization assumptions.
Competitive Landscape and Strategic Maneuvers
The geothermal heat pump industry features a blend of global HVAC incumbents, regional specialists, and emerging residential-focused innovators. Our analysis tracks how these companies are differentiating through technology adaptation, channel expansion, and strategic collaborations.
Among established manufacturers, several firms have actively recalibrated their product lines to align with evolving refrigerant standards and serviceability expectations. Recent product relaunches and model updates emphasize low-GWP refrigerant integration and improved field-service design, reflecting a broader industry shift away from legacy refrigerants that are being phased out in major markets. These transitions are not purely technical exercises; they carry implications for inventory planning, training pipelines, and installer partnership models. Companies that have moved early to align with next-generation refrigerant architectures are positioning themselves to reduce compliance risk while capturing demand from specifiers seeking future-proof installations.
Parallel to product-level innovation, the competitive landscape is being reshaped by collaboration-driven scaling strategies. Strategic partnerships have emerged as a critical mechanism for accelerating residential deployment, particularly in markets where installation capacity, permitting complexity, and customer acquisition costs have historically constrained growth. By aligning with broader HVAC distribution networks and deployment specialists, select market participants are constructing pathways to higher-volume residential rollouts that would be difficult to achieve through standalone operations.
The report provides detailed competitive intelligence on leading players, including Carrier Corporation, Bosch Thermotechnology, NIBE Energy Systems, Trane Technologies plc, ClimateMaster Inc., WaterFurnace International, BDR Thermea, Stiebel Eltron, Viessmann Group, and Dandelion Energy. Each profile is contextualized within broader strategic themes: how multinational firms leverage scale and integrated HVAC portfolios, how European manufacturers differentiate through energy-efficient ground-source system design, and how U.S.-based specialists are building niche leadership in residential and commercial ground-source applications. The study also examines recent standardization activity, including updated design and installation guidelines from industry bodies, which are influencing engineering practices and creating new compatibility expectations across product ecosystems.
A concrete illustration of the commercial and public-sector value proposition is visible in recent institutional deployments. Notably, a large school district completed geothermal heat pump upgrades across ten facilities, achieving substantial annual energy savings and outlining expansion plans to additional campuses. Projects of this nature reinforce the financial and operational case for geothermal adoption in public infrastructure and provide a reference architecture for commercial entities evaluating similar retrofitting pathways.
Regulatory, Reimbursement, and Cost Dynamics Shaping 2026 Decisions
The operating environment for geothermal heat pump stakeholders in 2026 is defined by a combination of compliance acceleration, incentive accessibility, and cost volatility. Understanding how these forces interact is essential for accurate forecasting and risk-adjusted planning.
On the regulatory front, the phase-down of legacy refrigerants has moved from anticipated policy to implemented reality. Major markets have moved to restrict the production and use of higher-GWP refrigerants, with manufacturers shifting engineering and sourcing toward compliant alternatives. This transition affects product design, supply chain logistics, and service infrastructure, creating both challenges and differentiation opportunities. Companies that have already aligned their portfolios with low-GWP refrigerant pathways are better positioned to navigate procurement constraints and installer readiness requirements.
Incentive architecture remains a powerful demand catalyst. Residential and commercial adopters continue to benefit from federal tax credit provisions that support qualifying installations through the early 2030s. Residential programs offer meaningful credit coverage through established energy efficiency pathways, while commercial frameworks provide base investment tax credit rates that can be expanded significantly when projects meet prevailing wage, domestic content, or energy community criteria. The strategic implication is twofold: early engagement with incentive compliance can materially improve project economics, and incentive optimization is increasingly becoming a competitive differentiator in commercial proposals and utility-coordinated programs.
Geothermal Power Market
At the same time, cost pressures are intensifying on the input side. Tariffs on imported HVAC components are elevating upfront installation costs and prompting supply chain reevaluation. Compressors, heat exchangers, and refrigerant sourcing are among the components drawing heightened cost attention, particularly for projects in North America and Europe. The report analyzes how these cost dynamics are influencing pricing strategies, manufacturing localization discussions, and procurement timing, helping stakeholders model realistic cost trajectories rather than relying on static assumptions.
Strategic Implications for Corporate Decision-Makers in 2026
The data and analysis presented in this study converge on a set of strategic imperatives for organizations operating in or entering the geothermal heat pump market. First, portfolio alignment with next-generation refrigerant standards should be treated as a near-term execution priority, not a long-range planning item. Second, incentive optimization and compliance readiness must be embedded into commercial proposal development, particularly for commercial and institutional projects where bonus credit pathways can meaningfully shift ROI profiles. Third, supply chain exposure to component tariffs requires proactive sourcing strategies, inventory planning, and scenario modeling to protect margin integrity in a volatile input-cost environment.
For companies evaluating market entry or expansion, the segmentation analysis in the report highlights where adoption momentum is strongest and where structural friction remains highest. For incumbents, the competitive profiles and recent development timeline illuminate where rivals are concentrating investment, which product features are becoming table stakes, and where partnership-based scaling is outpacing standalone deployment models. For investors and strategic planners, the market trajectory and concentration metrics provide a foundation for sizing opportunity pools while the detailed segment and dynamic layers enable more precise allocation decisions.
Closing Perspective
The geothermal heat pump market is evolving from a specialized efficiency solution into a strategically significant component of broader building decarbonization efforts. The convergence of regulatory momentum, incentive availability, product maturation, and cost-structure realignment creates a complex but navigable environment for organizations that can integrate market intelligence into execution planning. This research report is intended to provide that integration: a rigorous, forward-looking framework that converts macro trajectory and competitive behavior into actionable corporate strategy. The full dataset, segmented modeling, and detailed competitive evaluation are available through the complete study, enabling decision-makers to move beyond general market directionality and into the precise intelligence required for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Geothermal Heat Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


