



PW Consulting Projects 19.5% CAGR for Lithium-ion Battery Recycling Market Through 2032

Strategic Intelligence for 2026: Navigating the Lithium-ion Battery Recycling Market
Executive Overview: The Imperative for Precision Intelligence
The global energy transition is no longer just a policy aspiration; it is a supply chain reality. As electric vehicle adoption accelerates and stationary storage deployments multiply, the volume of end-of-life lithium-ion batteries is entering an inflection point. For corporate strategists, investors, and sustainability leaders, the question is no longer whether to engage with battery recycling, but how to position operations, partnerships, and capital allocation to capture value in a rapidly formalizing market.
PW Consulting's latest Lithium-ion Battery Recycling Market research is designed specifically for decision-makers operating in the 2026 landscape. This report does not merely aggregate historical figures; it translates trajectory, regulatory pressure, and competitive maneuvering into actionable frameworks. The analysis that follows is built to be read by executives who need to separate structural growth from cyclical noise, and who require validated intelligence to guide capacity planning, technology selection, and geographic expansion.
The market has already demonstrated remarkable momentum. Historical data from 2020 through 2025 reveals a sustained acceleration, with revenue climbing from 2.8 billion USD to 10.7 billion USD over that span. Looking forward, the trajectory suggests continued robust expansion, supported by a compound annual growth rate of 19.5 percent across the 2026 to 2032 forecast period. By 2032, this research projects the market will approach 37.5 billion USD. These are not abstract numbers; they represent a structural reallocation of capital, materials, and regulatory attention that will define competitive positioning for the remainder of the decade.
Why This Market Demands Specialized Intelligence
A Rapidly Evolving Value Chain
Battery recycling is not a monolithic activity. It spans collection logistics, discharge and disassembly, multiple metallurgical recovery pathways, and the reintroduction of refined intermediates into cathode and cell manufacturing. Each link in that chain carries distinct economics, technology risk, and regulatory exposure. The firms that succeed will be those that understand how these layers interact rather than those that optimize a single step in isolation.
The research recognizes this complexity. It maps the value chain from end-of-life battery intake through material recovery and back into production streams, highlighting where margins are created, where bottlenecks form, and where policy is reshaping the economics of recovery. For 2026 planning, this systems-level view is essential because capacity decisions made this year will lock in operational footprints that must withstand both feedstock variability and evolving compliance requirements.
Regulation as a Structural Driver, Not a Background Condition
Policy is now a primary determinant of market behavior. Across major jurisdictions, regulators are moving from voluntary guidance to enforceable standards that directly affect recycling economics. In the United States, the Infrastructure Investment and Jobs Act requires the EPA to develop battery collection best practices and labeling guidelines, with completion mandated by September 30, 2026. The EPA is also planning to propose new rules to improve the management and recycling of end-of-life lithium batteries, with a proposed rule expected in February 2026.
Europe is moving even faster on material recovery and recycled content. From 2026, the EU requires at least a 65 percent recycling rate for lithium-ion batteries, with the recovery rate for lithium increasing from 35 percent to 70 percent between 2026 and 2030. By 2031, batteries placed on the EU market must contain minimum levels of recycled content, including 6 percent lithium. In parallel, new European Commission rules published on July 4, 2025 establish requirements to calculate and verify recycling efficiency and material recovery rates.
These are not peripheral developments. They alter the cost structure of recovery operations, shift the value of specific recovered elements, and create compliance-driven demand for certified processes. The report integrates these regulatory trajectories into its market outlook so that leadership teams can evaluate exposure, opportunity, and contingency planning with a clear understanding of how compliance timelines intersect with commercial scaling.
Report Architecture: What Decision-Makers Will Find Inside
Granular Segmentation Without Losing Strategic Focus
The research is organized to support both portfolio-level strategy and operational decision-making. It segments the market along multiple dimensions, including geography, battery chemistry, recycling process, and source of end-of-life material. This structure allows readers to understand how growth is distributed across different pathways and where specific technologies or feedstock streams are gaining traction.
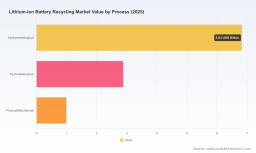
At the aggregate level, the segmentation data indicates that the Asia Pacific region represents the largest share of market revenue, followed by Europe and North America, with Latin America and the Middle East and Africa accounting for smaller but strategically relevant portions of the total. On the chemistry side, NMC-based batteries currently command the largest revenue share, with LFP and other chemistries forming meaningful but comparatively smaller components of the market. In terms of process, hydrometallurgical methods lead in revenue contribution, followed by pyrometallurgical and physical or mechanical approaches. By source, automotive end-of-life batteries represent the dominant revenue stream, with non-automotive sources contributing a substantial secondary share.
Importantly, this report avoids reducing these segments to isolated percentages. Instead, it explains the interplay between them: how chemistry mix influences process choice, how regional regulation shapes feedstock availability, and how source dynamics affect the economics of collection and pretreatment. That integrated framing is what makes the segmentation actionable rather than descriptive.
Technology and Process Evaluation for Capital Allocation
Choosing the right recovery approach is one of the most consequential decisions facing recycling investors and operators. Hydrometallurgical routes, pyrometallurgical routes, and physical or mechanical processes each carry different trade-offs in terms of material recovery rates, energy intensity, capital requirements, and sensitivity to feedstock composition. The report assesses these pathways in the context of current commercial deployments, emerging improvements, and the regulatory push toward higher lithium recovery and verified efficiency metrics.
For 2026 planning, this matters because process selection is increasingly tied to compliance and offtake confidence. As lithium recovery targets rise and recycled content requirements come into view, operations that can demonstrably meet higher recovery thresholds and provide traceable material streams will enjoy stronger positioning with downstream buyers. The research helps leaders weigh these considerations against capital timing, scaling risk, and regional feedstock characteristics.
Competitive Landscape: Who Is Moving, and How
The competitive environment is consolidating around firms that combine scale, technology differentiation, and strategic partnerships. The report profiles the companies most relevant to 2026 strategy, examining their operational posture, geographic focus, and recent commercial moves.
Among the firms analyzed are American Battery Technology Company, based in Reno, Nevada, which operates a commercial-scale recycling facility producing black mass and byproducts and is advancing a second 100,000 metric tonne-per-year facility with Department of Energy support. Ascend Elements, headquartered in Covington, Georgia, specializes in lithium recovery through its Hydro-to-Cathode technology and has achieved commercial-scale production of greater than 99 percent pure recycled lithium carbonate at its Georgia facility, with expansion plans extending to Poland. BatX Energies, based in Gurugram, India, provides hydrometallurgical recycling and critical minerals extraction services through its Uttar Pradesh plant and has secured agreements for high-voltage battery recycling and repurposing.
Ecobat, with headquarters in Dallas, Texas, operates as a global battery recycling provider and has commissioned three fully operational lithium-ion recycling plants in Germany, the United States, and the United Kingdom, each processing up to 10,000 tons annually of black mass. Altilium Metals, based in Plymouth, United Kingdom, develops proprietary EV battery recycling technology for the recovery of critical minerals including nickel MHP, lithium sulphate, and graphite, with its ACT 3 commercial facility under construction and supported by grant funding. Umicore, headquartered in Brussels, Belgium, reports recycling business group revenues of 947 million euros in 2025 and remains focused on battery materials processing at scale.
The landscape also includes Li-Cycle Corp, based in Toronto, Canada, which provides integrated recycling and refining services across multiple North American facilities; Call2Recycle, Inc., in Chicago, Illinois, which operates the nation's largest consumer battery stewardship and collection program and has partnered with recyclers such as American Battery Technology Company to expand domestic lithium-ion recycling channels; and Redwood Materials, based in San Francisco, California, which specializes in lithium-ion battery recycling and critical materials recovery and supports domestic supply chains with developments in South Carolina and medium-format battery processing.
Rather than presenting these profiles as static company summaries, the report situates them within broader strategic themes. It examines how partnerships, facility commissioning, and technology milestones are reshaping feedstock access, regional capacity, and the competitive bar for recovery quality. Recent developments included in the analysis illustrate this dynamic clearly: Ascend Elements achieved first commercial-scale production of greater than 99 percent pure recycled lithium carbonate from black mass at its Georgia facility in September 2025, enabling plans for more than 15 kilotons annually in the US and Europe by 2027. Ecobat commissioned three fully operational recycling plants in Germany, the US, and the UK in April 2025, processing up to 10,000 tons annually with expansion plans to 25,000 tons. American Battery Technology Company launched a landmark partnership with Call2Recycle in September 2025 to expand direct-to-consumer lithium-ion battery recycling in the US. In April 2026, Altilium Metals secured an 18.5 million pound grant for its ACT 3 facility, the UK's first commercial EV battery recycling plant in Plymouth, which is designed to recover nickel MHP, lithium sulphate, and graphite from up to 24,000 EV batteries annually.
Lithium-ion Battery Recycling Market
Strategic Implications for 2026 Decision-Making
Capacity Timing and Feedstock Realities
One of the central tensions in this market is the gap between announced capacity and the practical realities of feedstock collection, sorting, and pretreatment. Growth is real, but it is not uniformly distributed across regions, chemistries, or battery formats. The research provides the analytical scaffolding to assess where demand for recycled materials is most credible, which feedstock streams are likely to be most accessible, and how collection infrastructure is evolving to meet industrial and consumer sources alike.
For 2026, this means that capacity decisions should be evaluated not just against headline market size, but against the maturity of local collection channels, the chemistry mix in a given region, and the probability of securing consistent offtake at acceptable quality levels. The report's segmentation and competitive analysis are designed to support exactly this kind of calibrated planning.
Supply Chain Resilience and Domestic Processing
A recurring theme across recent industry activity is the drive to strengthen domestic and regional supply chains for critical materials. Recycled cathode materials, lithium compounds, and other recovered intermediates are increasingly viewed as components of supply security, not just sustainability initiatives. Firms such as Redwood Materials and American Battery Technology Company are explicitly building capacity that supports domestic value chains, while Ascend Elements is extending its footprint toward Europe.
The report examines how these supply chain ambitions interact with market economics and regulatory direction. It helps leaders understand where recycled materials can provide differentiated value in procurement strategies, where policy may further incentivize local processing, and how recyclers and battery users can structure relationships that reduce exposure to raw material volatility.
Concentration, Competition, and the Bar for Differentiation
The competitive environment is not yet an oligopoly, but it is cohesive enough that concentration matters. The research notes that the top three competitors account for approximately 32.5 percent of market revenue, while the top five reach about 42.8 percent. This level of concentration indicates that scale players are establishing meaningful positions, but substantial space remains for differentiated entrants, regional specialists, and technology-focused operators.
In practical terms, this means that competitive advantage in 2026 will depend on more than simply building capacity. It will depend on recovery quality, process reliability, compliance readiness, feedstock access, and the ability to demonstrate material traceability to downstream customers. The report's competitive analysis is structured to help readers identify where those differentiators are emerging and which strategic moves are most likely to create durable positioning.
Who Should Use This Research and How
This research is built for executives and advisors who need a credible, structured view of a market that is simultaneously high-growth and high-complexity. It is relevant to recycling operators evaluating capacity and process choices, to battery and automotive companies assessing supply chain resilience, to investors analyzing where capital can be deployed with the strongest risk-adjusted rationale, and to policy-adjacent professionals who need to understand the commercial implications of evolving compliance frameworks.
The report is organized so that different functions can extract what they need without losing sight of the whole. Strategy teams can use the segmentation and competitive analysis to frame market entry, expansion, and partnership decisions. Operations leaders can draw on the process evaluation and regulatory integration to inform technology and compliance planning. Corporate development groups can use the company profiles and recent developments to identify partnership targets and monitor competitive signaling.
Forecasting Discipline for a Market in Motion
Forecasts in fast-moving industries can easily become either too optimistic or too cautious. The research is designed to avoid both traps by grounding projections in historical trajectory, current commercial activity, and the regulatory calendar that will shape the market over the next several years. The forecast period from 2026 through 2032 is presented not as a single line, but as a framework within which leadership teams can test assumptions about feedstock availability, process economics, and regional policy implementation.
Lithium Ion Battery Market
This approach is especially important for 2026 decisions because the market is at a point where early-mover advantages can be consolidated or eroded depending on execution. Companies that understand the interplay of regulation, chemistry mix, process economics, and competitive behavior will be better positioned to time investments, negotiate offtake, and build relationships that hold value as the market matures.
Conclusion: Use the Preview, Then Lock In the Full Picture
The lithium-ion battery recycling market in 2026 is too strategically important to navigate on partial information. The revenue trajectory, the pace of regulatory change, the diversity of recovery technologies, and the competitive moves already underway all point to a market where disciplined intelligence will separate durable strategies from reactive ones.
This overview has outlined the scope, structure, and strategic logic of PW Consulting's latest research. It has provided the macro picture, highlighted the segmentation architecture, introduced the competitive landscape and recent developments, and connected the analysis to the decisions that matter this year. What it has not done is replace the full report. The complete research delivers the deeper segmentation detail, the integrated regulatory analysis, and the competitive context needed to turn these themes into specific plans.
For teams planning capacity, partnerships, procurement, or investment in 2026, the next step is clear: use this preview to identify the questions that matter most, then access the full report to obtain the validated market intelligence required to answer them with confidence.
For detailed analysis of this topic, please visit the official page: Lithium-ion Battery Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


