



PW Consulting: Centrifugal Pump Market Hits $215M in 2025, Projects 6% CAGR to 2032

Strategic Insights into the 2026 Centrifugal Pump Market Dynamics
Executive Overview
The global centrifugal pump industry stands at a pivotal juncture as we move through 2026. Driven by intensifying regulatory frameworks, evolving industrial demands, and a steady trajectory of growth, the market presents both significant opportunities and complex challenges for stakeholders. As strategic advisors, we recognize that understanding the nuanced shifts in this sector is no longer optional—it is imperative for sustainable competitive advantage. This article serves as an introduction to our comprehensive market research, designed to equip decision-makers with the intelligence required to navigate the forecast period from 2026 to 2032.
The industry has demonstrated resilience and consistent expansion over the past five years. Historical data indicates a steady climb in revenue, reflecting the essential nature of fluid movement across municipal, industrial, and infrastructure sectors. As organizations plan their capital expenditures and operational strategies for the remainder of the decade, having access to granular data regarding market sizing, growth rates, and segmentation is critical. Our latest study dissects these elements to provide a clear roadmap for investment and development.
Market Trajectory and Macro Economic Indicators
Analyzing the historical performance from 2020 through 2025 reveals a robust upward trend that sets the stage for the current forecast period. The market has consistently expanded, moving from a base of approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. This growth underscores the fundamental reliance on centrifugal technology across diverse end-use industries. As we look forward, the momentum is expected to continue, with projections indicating the market will reach 227.68 million USD in 2026 and potentially ascend to 344.8 million USD by 2032.
The compound annual growth rate (CAGR) during the forecast period is estimated at 6.0 percent. This metric is vital for long-term planning, suggesting a steady, albeit competitive, expansion environment. For enterprises involved in manufacturing, distribution, or procurement, this growth rate signals a market that is mature enough to offer stability yet dynamic enough to reward innovation. However, capturing this growth requires more than just historical context; it demands an understanding of where the volume is shifting geographically and technically.
Our research delves deep into the specific valuation shifts expected over the next six years. While the aggregate numbers provide a high-level view, the true value lies in understanding the underlying drivers pushing these figures. We have mapped the revenue projections year-by-year to help stakeholders benchmark their internal growth targets against market realities. This longitudinal analysis highlights inflection points where market acceleration may occur due to regulatory changes or technological adoption curves.
Segmentation Dynamics: Type and Application
The market is broadly categorized by pump configuration and end-use application, each presenting distinct growth vectors. In terms of pump type, the landscape is divided primarily between single-stage and multi-stage configurations. The single-stage segment currently holds a significant portion of the market value, reflecting its widespread use in general industrial and municipal applications. However, the multi-stage segment is gaining traction, driven by the need for higher pressure and efficiency in specialized processes.
On the application front, the diverse range of industries utilizing centrifugal pumps ensures market stability. Water and wastewater management remains a cornerstone of demand, consistent with global infrastructure development goals. Beyond this, the oil and gas sector, chemical and petrochemical processing, and mining and metals industries contribute substantial revenue streams. Each application vertical has unique operational requirements regarding durability, flow rate, and compliance with safety standards.
Understanding the interplay between these segments is crucial. For instance, regulatory pressures in the water sector may accelerate the adoption of specific pump types, while harsh environments in mining may sustain demand for robust single-stage solutions. Our report provides a detailed breakdown of these segmentation splits without relying on generic industry assumptions. We analyze the value distribution across these categories to identify which areas offer the highest margin potential and which are becoming commoditized.
Regional Growth Vectors
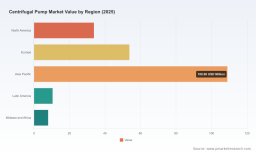
Geographically, the market exhibits varied growth patterns influenced by local industrialization rates, infrastructure spending, and regulatory environments. The Asia Pacific region represents a significant volume driver, reflecting rapid urbanization and industrial expansion. Europe continues to be a mature market where efficiency standards and sustainability mandates heavily influence procurement decisions. North America remains a key hub for technological innovation and high-reliability industrial applications.
Emerging regions in Latin America and the Middle East and Africa also contribute to the global revenue pool, often driven by specific infrastructure projects or resource extraction activities. While the aggregate global number is important, the strategic nuance lies in recognizing regional disparities. Supply chains, local competition, and import-export dynamics vary significantly across these territories. Our analysis maps these regional contributions to help companies tailor their market entry or expansion strategies effectively.
We have assessed the revenue contribution from each major region to highlight where the growth hotspots are located for the forecast period. This regional intelligence allows stakeholders to allocate resources more efficiently, avoiding saturated markets while capitalizing on emerging opportunities. The data provided in our full study offers a clear view of regional market sizes, enabling precise geographic targeting.
Regulatory Landscape and Industry Dynamics
One of the most critical factors influencing the centrifugal pump market in 2026 is the tightening regulatory environment. Governments worldwide are increasingly focusing on energy efficiency and carbon footprint reduction, directly impacting pump specifications and replacement cycles. In the United States, Department of Energy rules effective January 2025 set new energy-index thresholds. These regulations are accelerating the swap-out of inefficient single-stage centrifugal pumps, forcing manufacturers and end-users to reconsider their equipment portfolios.
Centrifugal Compressors Market
Similarly, the European market is preparing for significant changes. IE4 motor stipulations set to become effective in 2027 are expected to advance the adoption of variable-speed multi-stage centrifugal pumps. These regulations are not merely compliance hurdles; they are catalysts for technological upgrading. Companies that anticipate these shifts can gain a first-mover advantage by stocking compliant inventory or offering retrofit solutions before the deadlines hit.
These regulatory drivers are converging to shape the overall market dynamics. The push for energy efficiency is aligning with operational cost reduction goals, making high-efficiency pumps an attractive investment despite potentially higher upfront costs. Our report analyzes how these regulatory measures interact with market demand, estimating the potential impact on replacement rates and new installations. We explore the compliance landscape in detail, providing a risk assessment for non-compliance and an opportunity analysis for early adopters.
Competitive Landscape and Key Players
The market structure is characterized by a mix of global giants and specialized niche manufacturers. The top three companies hold a combined market share of 35.5 percent, while the top five account for 39.8 percent. This concentration suggests a competitive environment where large players dominate through scale and brand equity, but significant room remains for specialized firms to capture value through innovation and service excellence.
Several key companies define the current competitive landscape. Grundfos Holding A/S, based in Denmark, continues to be a major force in manufacturing energy-efficient centrifugal pumps for municipal, industrial, and building applications. Their focus on sustainability aligns well with current regulatory trends. Xylem Inc., headquartered in the United States, provides IoT-enabled centrifugal pumps for utilities, water treatment, and industrial sectors, representing the technological integration trend within the industry.
Flowserve Corporation specializes in large-scale, high-reliability centrifugal pumps for oil and gas, chemical, and power industries, catering to the high-end industrial segment. Sulzer Ltd, from Switzerland, offers precision centrifugal pumps for refining, chemicals, and water systems, maintaining a reputation for engineering excellence. KSB Group, based in Germany, produces automation-ready centrifugal pumps for industrial and infrastructure applications, highlighting the shift towards smart manufacturing integration.
In the Americas, Gorman-Rupp Company manufactures high-performance centrifugal pumps for municipal, industrial, and construction markets, maintaining a strong regional presence. Carver Pump Company builds military-grade centrifugal pumps for demanding industrial, marine, and process applications, serving niche high-durability needs. Ampco Pumps Company offers sanitary and industrial centrifugal pumps with ISO 9001:2015 compliance, focusing on quality assurance in sanitary sectors. Cornell Pump Company, also based in the United States, produces efficient, Made-in-USA centrifugal pumps for agriculture, municipal, and industrial use, recently celebrating its 80th anniversary with a focus on efficient by design pumps at ConExpo in April 2026. Finally, SPP Pumps from the United Kingdom specializes in engineered centrifugal pump packages and systems for industrial applications, offering customized solutions.
Our analysis goes beyond corporate profiles to examine recent developments and strategic moves. For example, Cornell Pump Company's recent milestone highlights the enduring value of domestic manufacturing and efficiency-focused design. We track how these companies are responding to regulatory pressures and technological shifts. The full report includes a detailed competitive benchmarking analysis, evaluating each player's market position, product portfolio strength, and strategic response to industry dynamics.
Centrifugal Pump Market
Strategic Implications for Stakeholders
For manufacturers, the key to success in 2026 and beyond lies in aligning product portfolios with regulatory roadmaps. Developing pumps that meet upcoming IE4 standards or DOE energy indices is not just about compliance; it is about future-proofing the product line. Investment in R&D for variable-speed drives and energy-efficient motor integrations will likely yield higher returns as customers seek to reduce operational expenditures.
For distributors and supply chain partners, understanding the segmentation shifts is vital. As multi-stage and variable-speed pumps gain share due to regulations, inventory strategies must adapt. stocking legacy single-stage models may become risky as replacement mandates take effect. Partners need to ensure they have the technical expertise to support the installation and maintenance of next-generation equipment.
End-users and industrial operators must consider the total cost of ownership rather than just the purchase price. With energy costs and regulatory penalties potentially rising, the economic case for high-efficiency pumps strengthens. Procurement strategies should factor in the lifespan of equipment relative to regulatory deadlines, ensuring that capital investments do not become stranded assets due to non-compliance.
Investors looking at the sector should focus on companies with strong R&D pipelines andadaptive supply chains. The concentration of market share among the top players indicates barriers to entry, but innovation can disrupt existing hierarchies. Companies that successfully integrate IoT capabilities or offer superior service models may outperform the average market growth rate.
Research Methodology and Value Proposition
Our market study is constructed using a robust methodology that combines top-down and bottom-up analysis. We utilize historical data to validate growth trends and apply stringent forecasting models to project future performance. The data is sourced from primary interviews with industry participants, supply chain partners, and regulatory bodies, supplemented by extensive secondary research.
The report provides actionable intelligence beyond mere market sizing. It includes detailed segmentation analysis, competitive profiling, and regulatory impact assessments. We examine the supply chain dynamics, identifying key bottlenecks and opportunities for optimization. The forecast period analysis is granular, allowing users to model different scenarios based on varying assumptions about economic conditions and regulatory enforcement.
By consolidating this information into a single comprehensive document, we save stakeholders the time and resources required to gather disparate data points. The insights provided are designed to support strategic planning, market entry decisions, investment analysis, and operational benchmarking. Every claim and projection is backed by data, ensuring that decision-makers can rely on the findings with confidence.
Conclusion and Next Steps
The centrifugal pump market in 2026 is defined by a convergence of steady growth, regulatory pressure, and technological evolution. With a projected CAGR of 6.0 percent and a market size expected to exceed 340 million USD by 2032, the sector offers substantial potential for those equipped with the right intelligence. The shift towards energy efficiency, driven by DOE rules and European IE4 stipulations, will reshape demand patterns, favoring advanced multi-stage and variable-speed solutions.
Navigating this landscape requires more than general industry knowledge. It demands precise data on segmentation values, regional contributions, and competitive movements. While this article provides a high-level overview of the market dynamics and key players, it intentionally omits specific segmentation percentages and detailed regional breakdowns to maintain the integrity of our proprietary research.
To fully leverage these insights for your strategic planning, we invite you to access the complete Centrifugal Pump Market report. The full study contains the detailed data tables, comprehensive company profiles, and in-depth regulatory analysis necessary to make informed decisions in this evolving market. Secure your copy today to ensure your organization remains ahead of the curve in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Centrifugal Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


