



PW Consulting: Dispensing Systems Market Hits $57.99B in 2025, Projects 6.7% CAGR Through 2032

Strategic Precision: Navigating the Dispensing Systems Market Trajectory Through 2032
The global dispensing systems market is entering a decisive growth cycle, driven by tightening quality standards, the rise of automated production, and accelerating demand across high-tech manufacturing verticals. As organizations plan capital allocation and technology roadmaps for 2026 and beyond, understanding where the market is heading—and which capabilities will separate leaders from laggards—has become a critical competitive advantage. Our latest Dispensing Systems Market research study provides a structured, forward-looking intelligence framework designed to support executive decision-making through the 2026–2032 forecast horizon.
Why 2026 Marks a Strategic Inflection Point
The market has moved steadily from 41.9 billion USD in 2020 to approximately 58.0 billion USD in 2025, reflecting sustained expansion across multiple industrial and life sciences applications. The projected trajectory continues with a forecast valuation near 59.8 billion USD in 2026, progressing toward roughly 89.1 billion USD by 2032. With a compound annual growth rate of 6.7 percent, this is not a market defined by sudden volatility but by compounding structural demand. For strategic planners, that consistency is both an opportunity and a warning: steady growth rewards early positioning, but it also intensifies competition for market share as incumbents scale and new entrants refine niche technologies.
Dispensing Systems Market
Several cross-currents are reshaping how companies think about dispensing investments this year. Precision fluid control is no longer a back-office manufacturing concern. It is increasingly tied to product reliability, regulatory compliance, yield improvement, and ultimately brand credibility. In medical device assembly, electronics encapsulation, and pharmaceutical filling, consistency is not optional. Stringent quality and product consistency requirements enforced by FDA and ISO standards are pushing manufacturers toward dispensing solutions that can deliver repeatable performance under stringent inspection regimes. At the same time, advancements in robotics, closed-loop control, and integrated work cells are expanding what automated dispensing can achieve on high-mix production lines.
This is exactly why a 2026-focused intelligence view matters. Executive teams need more than a headline growth figure. They need context on how demand is shifting across system types, where adoption is accelerating, and which operational pressures are turning dispensing from a component purchase into a strategic capability.
What This Research Delivers: An Executive-Level Roadmap
Our Dispensing Systems Market study is built as a decision-support platform rather than a static data sheet. It translates macro growth signals into actionable insight across technology, application, and competitive dimensions, giving leaders a clearer line of sight into where to invest, consolidate, or differentiate.
The report examines the evolving architecture of dispensing solutions, including manual, automated, and robotic system categories. Rather than treating these as isolated product groups, the analysis maps how each category fits into different manufacturing environments, volume profiles, and precision requirements. That distinction is essential because the value proposition of a dispensing system changes depending on whether the priority is flexibility, throughput, repeatability, or contamination control.
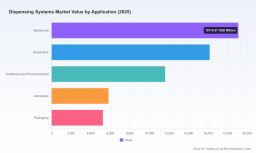
The research also explores demand patterns across major end-use environments, including electronics, automotive, healthcare and pharmaceutical, aerospace, and packaging applications. These sectors are not moving in lockstep. Some are being pulled forward by miniaturization, sensor proliferation, and advanced assembly requirements. Others are being reshaped by traceability mandates, sterile processing expectations, or the need to handle higher-viscosity materials with greater control. The study breaks down those dynamics so strategy teams can identify which application pockets offer the strongest alignment with their own capabilities and which carry higher barriers to entry.
Beyond segmentation, the report evaluates the operational and regulatory forces that are quietly redefining competitive requirements. In life sciences and pharmaceutical production, dispensing equipment increasingly must support aseptic processing, containment discipline, and sterile drug production workflows. In medical device manufacturing, quality consistency and documentation rigor have become embedded in procurement criteria. In electronics and related high-precision sectors, the push for finer deposits, lower waste, and tighter process control is accelerating adoption of more sophisticated dispensing equipment. These trends are not abstract compliance issues; they directly influence purchasing criteria, vendor selection, and long-term service expectations.
Competitive Landscape: Where Consolidation and Differentiation Converge
The market remains concentrated, with a small group of established players commanding a significant share of revenue. That concentration matters because it shapes pricing power, technology diffusion, and partnership dynamics. Companies that can combine precision engineering, application-specific know-how, and strong service networks are well positioned, while those relying on commoditized hardware face increasing pressure.
Several firms stand out for their focus on differentiated dispensing technologies and target vertical expertise. Nordson EFD continues to emphasize precision fluid dispensing systems, automated robotic dispensers, and single-use packaging for manufacturing applications. Its recent activity underscores the importance of live demonstration and application-specific positioning, including automated fluid dispensing systems presented for medical device assembly and encapsulation, as well as demonstrations focused on wearable medical technology sensor encapsulation. That pattern illustrates a broader industry shift: competitive advantage is increasingly earned through application proof points, not specification sheets alone.
Fisnar remains focused on fluid dispensing equipment, valves, and integrated robot work cells for adhesives, resins, and industrial liquids, reflecting the continuing importance of modular, integration-ready architectures. Musashi Engineering contributes a strong precision orientation, with emphasis on liquid dispensing systems and ultra-micro control equipment for industrial manufacturing environments where minute fluid handling matters. Fluid Metering, Inc. differentiates around valveless ceramic metering pumps and dispensers designed for precise fluid control in lab, chemical, and industrial applications—an approach that highlights the role of pump and metering technology in achieving consistent output.
GPD Global targets high-performance fluid dispensing systems for electronics, PCB, semiconductor, and solar manufacturing, sectors where process discipline and contamination sensitivity reward specialized solutions. In the pharmaceutical and sterile production space, Comecer concentrates on aseptic dispensing and filling systems for pharmaceutical, radiopharmaceutical, and sterile drug production. Its recent tabletop dispensing system announcement for standalone filling and closing of injectable and non-injectable vials points to the growing demand for compact, flexible solutions that still meet stringent sterile processing requirements.
The competitive field also includes firms with strong customization and application-engineering capabilities. Hernon Manufacturing focuses on custom adhesive dispensing systems, valves, and integrated solutions for high-viscosity manufacturing, while GP Reeves builds around customized automated fluid dispensing systems for production and assembly lines. SPEC, Inc. brings a specialized emphasis on ink dispensing systems and integrated mixing equipment for coatings and industrial applications, and JagCo contributes automated adhesive, fluid, and robotic dispensing systems for manufacturing precision. Together, these players illustrate a market where broad capability and vertical specialization are both viable paths—but only when paired with convincing integration, service, and process validation support.
Recent activity across these companies reinforces a clear theme. Trade show demonstrations, product announcements, and application-focused showcases are increasingly oriented toward real-world performance in regulated or high-precision environments. That suggests the market is maturing from hardware comparison toward solution validation. Buyers are less interested in whether a system can dispense, and more interested in whether it can do so consistently within their specific process constraints.
Market Dynamics Shaping 2026 Decisions
A few strategic dynamics will influence how companies prioritize dispensing investments over the next several years.
Dispensing Robot Market
- Regulatory and quality pressure is becoming a demand catalyst. In medical device manufacturing and electronics production, expectations for quality, traceability, and product consistency are tightening. That environment favors dispensing systems with stronger process control, repeatability, and validation support.
- Automation is moving from efficiency tool to precision enabler. As labor constraints, variability, and throughput demands intensify, automated and robotic dispensing solutions are increasingly evaluated for their ability to reduce variability and support complex assembly or encapsulation tasks.
- Application specialization is reshaping purchasing criteria. Different verticals impose different constraints on viscosity handling, contamination control, deposit size, speed, and documentation. Companies that can align system design with those constraints gain an advantage in qualified supplier lists and repeat sourcing.
- Sterile and aseptic processing requirements are elevating the importance of integrated system design. In pharmaceutical and life sciences environments, dispensing equipment is being assessed not only on dispensing accuracy but also on cleanliness, containment, and compatibility with sterile workflows.
- Demonstration-led commercialization is gaining importance. Recent product showcases and live demonstrations suggest that the market values tangible proof of performance in target use cases, especially where failure is costly or compliance exposure is high.
For strategy teams, the implication is straightforward. Dispensing investment decisions should be evaluated not just against unit cost, but against compliance readiness, integration complexity, application fit, and long-term serviceability. In many cases, the most cost-effective system on paper is not the most strategically sound choice once total operating risk is considered.
How to Use This Intelligence for 2026 Planning
This Dispensing Systems Market research study is designed to support multiple planning functions. For portfolio and product teams, it provides a structured view of where demand is expanding and where application requirements are becoming more demanding. For operations leaders, it helps frame the trade-offs between manual, automated, and robotic approaches in different production contexts. For commercial and business development teams, it offers a way to benchmark competitive positioning, identify emerging solution expectations, and prioritize the verticals most aligned with organizational strengths.
The report also supports scenario thinking. Because growth is projected to persist through 2032, companies can use the analysis to test whether their current capabilities will be sufficient as requirements tighten, or whether they need to invest earlier in precision control, automation integration, or regulatory-aligned system design. The goal is not simply to forecast size, but to improve decision quality under uncertainty.
Why the Full Study Matters
Macro figures tell part of the story, but they do not reveal which segments are driving momentum, how technology preferences are shifting, or where competitive intensity is most likely to compress margins. They do not show which application requirements are becoming disqualifying factors, or how leading companies are translating regulatory and precision demands into differentiated offerings. Those insights require a deeper, more structured examination.
The complete report goes further by mapping market structure, competitive positioning, application-specific demand signals, and the operational forces that will shape purchasing behavior through the end of the decade. For teams preparing 2026 investment decisions, supplier strategies, or technology roadmaps, that level of detail is essential.
If your objective is to move beyond surface-level market sizing and understand where precision dispensing is heading, the full study offers the analytical depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Dispensing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


