



PW Consulting: LNG Liquefaction Market Hits $215M in 2025, Projected 8.2% CAGR Through 2032

Strategic Intelligence for the LNG Liquefaction Equipment Market 2026: A PW Consulting Strategic Brief
As global energy trade realigns around natural gas security, flexible supply chains, and decarbonization pathways, the LNG liquefaction equipment sector has transitioned from a cyclical capital goods segment to a structural enabler of export diversification and buyer-side procurement resilience. PW Consulting’s latest market research release examines the full architecture of this market, providing executives, investors, and procurement strategists with a decision-grade intelligence framework calibrated for 2026 and the forecast horizon through 2032.
LNG Liquefaction Equipment Market
This article serves as a strategic preview of the complete report. It synthesizes the observable macro trajectory, the structural segmentation patterns, the competitive theater now being redefined by recent contract executions, and the operational dynamics that are reshaping cost, schedule, and technology selection in liquefaction programs. It is designed to demonstrate the analytical depth of the full dataset while preserving the exact segmentation figures, regional share distributions, and granular revenue breakdowns that our clients rely on for capital allocation, competitive benchmarking, and commercial positioning.
The 2026 Growth Trajectory: From Post-Pandemic Recovery to Structural Expansion
The market for LNG liquefaction equipment has moved decisively beyond the volatility of the early 2020s. The historical record shows a measured recovery across the 2020 to 2025 period, followed by an acceleration that establishes a robust baseline heading into the forecast window. According to the full research dataset, total market revenue has expanded from 163.15 million USD in 2020, through 177.66 million USD in 2021 and 180.05 million USD in 2022, to 183.07 million USD in 2023, climbing further to 201.3 million USD in 2024 and reaching 215.0 million USD in 2025. This progression reflects not only the restoration of project delays and supply chain normalization, but the emergence of sustained demand for liquefaction systems across both greenfield export capacity and mid-tier modular deployments.
Looking forward, the forecast period from 2026 to 2032 charts a clear path of compounding growth. The model projects revenue advancing to 236.46 million USD in 2026, 251.25 million USD in 2027, and 263.25 million USD in 2028, before an inflection step-up to 300.93 million USD in 2029, 322.5 million USD in 2030, 349.2 million USD in 2031, and 373.44 million USD in 2032. This trajectory is underpinned by a forecast CAGR of 8.2%, a rate that positions the liquefaction equipment segment as a disciplined growth market rather than an episodic boom cycle. For strategic planners, the significance of this 8.2% CAGR lies in what it implies about capital intensity, technology refresh cycles, and the competitive urgency of securing preferred equipment slots in late-2020s train expansions.
The full report contextualizes these headline numbers within a broader analytical architecture that explains the timing, magnitude, and structural logic of the 2029 step-change. Rather than presenting raw figures in isolation, the study maps them against contracting pipelines, modularization economics, train-scale dynamics, and vendor capacity constraints, transforming the top-line numbers into a decision-support system for capacity planning, partnership strategy, and risk-weighted procurement horizons.
Inside the Research: What Decision-Makers Will Find in the Full Report
A market research deliverable earns its strategic value only when it translates macro trends into actionable intelligence. The full PW Consulting study is structured to support that translation. It moves beyond a single aggregate view and decomposes the market into the operational, manufacturing, and infrastructure dimensions that determine real-world competitive outcomes.
The report provides a multi-dimensional segmentation framework that covers system-level equipment architectures, equipment manufacturing pathways, plant size classifications, and regional deployment patterns. This structure allows readers to isolate demand drivers across refrigerant compression, pumping and storage, power systems, and auxiliary categories, and to understand how plant configuration choices, modular versus stick-built construction philosophies, and plant sizing strategies influence both equipment mix and commercial positioning.
Within the plant-size lens, the dataset examines distinct deployment profiles, including small-scale LNG facilities, mid-scale plants, large export-oriented complexes, and floating LNG platforms. Each category carries different procurement patterns, technology preferences, cadence of equipment orders, and competitive access barriers. The research evaluates how these profiles interact with project financing structures, liquefaction cycle selection, and the increasing role of scalable modular solutions in compressing delivery timelines.
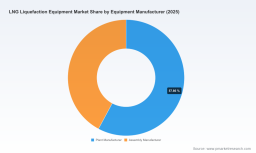
At the equipment manufacturing level, the analysis distinguishes between plant manufacturers and assembly manufacturers, clarifying the division of responsibility, integration risk, and commercial leverage that defines the current supply chain. This distinction is essential for procurement teams seeking to balance technology ownership against fabrication capability, for investors assessing vertical integration strategies, and for operators evaluating EPC partnerships with embedded equipment supply relationships.
The regional architecture of the market is equally critical. The full report covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, mapping where demand is concentrated, where equipment supply is scaling, and where project execution dynamics are most likely to generate near-term procurement pressure. The research avoids superficial regional rankings and instead examines the structural conditions that differentiate market access, lead-time expectations, and competitive intensity across geographies.
Beyond segmentation, the study integrates competitive profiling, recent contract executions, technology adoption patterns, modularization trends, labor and fabrication dynamics, and infrastructure developments that shape the competitive playing field. It is designed to be read alongside internal capital models, procurement planning cycles, and technology roadmaps, giving executives a common reference point for comparing vendor propositions, negotiating equipment package scopes, and anticipating bottlenecks.
Competitive Theater: Who Shapes the Liquefaction Equipment Landscape in 2026
The competitive environment in LNG liquefaction equipment is defined by a blend of proprietary process technology providers, primary equipment suppliers, modular solution developers, and large engineering-procurement-construction integrators. Market concentration, as captured in the full dataset, reflects a landscape where the top players collectively command a significant but not dominant share of revenue, leaving substantial space for differentiated capability, niche technology positioning, and regional execution strength. The CR3 and CR5 concentration metrics in the report provide an evidence-based starting point for understanding how competition is structured and where entry, partnership, or displacement opportunities may emerge.
Honeywell remains a central force in liquefaction process technology. Its equipment portfolio and cycle solutions are widely deployed across major export projects, anchoring its role in the refrigerant compression and heat exchange architecture that underpins liquefaction trains. The company’s technology footprint is reinforced by recurring selection in new train awards and its established presence in global LNG production workflows.
Baker Hughes operates as a core primary equipment supplier, with a focused position in refrigerant turbo compressors and gas turbine power systems that supply the mechanical and energetic core of liquefaction facilities. Its product relevance extends across export-oriented plants where reliability, efficiency, and long-term service integration are critical to project economics.
Technip Energies brings a distinct angle through modular liquefaction engineering and standardized SnapLNG concepts, alongside full engineering support for export terminals and liquefaction plants. Its approach reflects the broader industry shift toward scalable, repeatable, and faster-to-deploy plant configurations, making it a relevant benchmark for operators evaluating modular versus conventional delivery modes.
Kiewit and Bechtel anchor the large-scale execution side of the market. Both firms lead EPC programs for major LNG liquefaction and export projects, with responsibilities spanning module integration, pretreatment, pipe racks, process technology integration, and full facility construction. Their roles matter because the boundary between equipment supply and EPC execution increasingly shapes commercial risk, schedule certainty, and the strategic value of early equipment-selection decisions.
What gives this competitive set strategic importance in 2026 is not static market share, but the way recent contracts are revealing shifting alliances, modular technology adoption, and equipment-package contracting. These patterns are not decorative details; they inform pricing power, slot availability, technology preference, and the likelihood of localized fabrication versus global supply. The full report unpacks these competitive signals in depth, using recent project activity as a lens on where capabilities are being monetized and where competitive gaps may open.
2026 Activity Snapshot: What Recent Contracts Reveal About Market Direction
Recent developments in liquefaction projects are already reshaping how equipment suppliers, EPC firms, and operators interact across the value chain. The activity observed in early 2026 provides a forward-looking signal of execution priorities, technology choices, and fabrication strategies that directly affect equipment demand.
Technip Energies’ recent EPC contract execution for a 9.5 MTPA export facility reflects the continued scaling of modular-capable engineering solutions in large export infrastructure. The award underscores how modular liquefaction concepts are being embedded into substantial projects, influencing scope boundaries, equipment package structures, and delivery sequencing.
Honeywell’s technology supply agreement for Rio Grande LNG Train 4 and Train 5 demonstrates the continued relevance of established coil-wound heat exchanger equipment and C3MR process technology in high-profile export expansions. Selection of this type reinforces the importance of proven liquefaction cycle architecture in securing long-cycle export train awards, and it signals sustained demand for high-efficiency heat exchange and associated equipment packages.
Kiewit’s lump-sum turnkey EPC execution for a Texas LNG facility, including module fabrication for liquefaction, pretreatment, and pipe rack systems, highlights the intensifying role of self-performed work and integrated module fabrication in controlling schedule and cost outcomes. When a single EPC entity manages both on-site execution and off-site module fabrication, equipment procurement timing, coordination risk, and fabrication capacity become strategic variables rather than background logistics.
Baker Hughes’ additional order for primary liquefaction equipment on Rio Grande LNG Train 5, including gas turbines and centrifugal compressors, further illustrates how core rotating and compression equipment continues to anchor project schedules and equipment package value. These orders reveal the layering of equipment commitments within multi-train programs and the importance of aligning equipment delivery with modular construction milestones.
Beyond contract awards, the surrounding operational context matters. Module fabrication for liquefaction, pretreatment, and pipe rack systems is proceeding in Texas, reflecting localized fabrication strategies that can reshape lead times and labor deployment. The Rio Grande LNG project’s phased construction across multiple trains demonstrates the modular EPC approach in practice, with successive train progression creating a cadence of recurring equipment and integration demands. Technology adoption is another structural signal: one major equipment provider’s liquefaction technology is reported to be used in nearly two-thirds of global LNG fuel production, reinforcing the gravitational pull of established cycles in new selection decisions. Meanwhile, modular scalable solutions are increasingly delivering large tonnages of LNG modules as part of standardized liquefaction train offerings, tightening the link between modularization capability and competitive differentiation.
Taken together, these developments indicate that 2026 is a year when execution logic is shaping equipment market outcomes as much as project announcements are. The full report builds this context into a structured competitive reading that helps clients anticipate where bottlenecks, leverage points, and partnership opportunities will arise.
Strategic Implications for 2026 Decision-Making
For executives navigating LNG liquefaction equipment markets, 2026 is not simply a forecast year; it is a planning inflection point. The combination of an 8.2% CAGR, a stepped revenue path into the late 2020s, and an increasingly modularized, contract-dense competitive environment means that strategic decisions made now will influence equipment access, technology positioning, and cost outcomes across the 2026 to 2032 horizon.
Procurement teams need to understand where equipment demand is being concentrated by train configuration, plant size strategy, and modularization choice, and how those choices alter vendor leverage. Investors require segmentation visibility not merely to assess size, but to judge which system categories, manufacturer types, and plant-size segments are likely to see the strongest compounding demand and the most intense competitive contestation. Competing firms need competitive intelligence that goes deeper than headline company profiles to reveal how recent contracts, fabrication strategies, and technology selection patterns are redrawing the practical boundaries of market access.
The full PW Consulting report is designed to support all of these decisions. It gives readers the structure, evidence, and analytical language needed to evaluate equipment package scopes, prioritize manufacturing and partnership relationships, and align capital and procurement strategies with the underlying shape of the market.
Helium Liquefier Market
Why the Full Report Matters
This article provides the strategic frame and the visible portion of the analysis. The complete research report goes further. It delivers the segmentation breakdowns that reveal how system types, equipment manufacturer categories, plant size profiles, and regional markets interact to shape total demand; it presents the exact market size progression and concentration metrics that anchor scenario planning; it profiles the core companies with competitive context and recent activity integration; and it translates project-level developments into procurement, technology, and execution implications that can be applied across internal decision processes.
Most importantly, the full report preserves the precision that strategic planning requires without diluting it into oversimplified rankings. It is built for teams that need to compare vendor propositions, assess scope boundaries, forecast equipment ordering windows, and understand how competing modular and EPC strategies are reshaping the commercial landscape.
For executives, investors, procurement leaders, and competitive strategists preparing for 2026 and beyond, the complete PW Consulting LNG Liquefaction Equipment Market research is the next step in converting market intelligence into commitment-ready strategy. Explore the full dataset and segmentation detail to gain the complete view needed for capital, contract, and competitive decisions.
For detailed analysis of this topic, please visit the official page: LNG Liquefaction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


