



PW Consulting: Tungsten Hexafluoride Market to Hit USD 344.8 Million by 2032, Growing at 6.8% CAGR

Strategic Intelligence Behind the Tungsten Hexafluoride Market Outlook: Navigating the 2026–2032 Inflection Point
Executive Perspective: Why This Market Deserves Boardroom Attention
Tungsten hexafluoride has long operated as a quiet but indispensable enabler of advanced manufacturing. As a key precursor in chemical vapor deposition and a foundational feedstock for tungsten-based materials, its demand profile is tightly coupled to the cadence of semiconductor scaling, advanced packaging, and industrial tungsten carbide production. Yet the market has entered a new strategic era defined by material geopolitics, capacity realignments, and accelerating procurement complexity. For executives managing supply chains, capital allocation, and technology roadmaps, the task is no longer to track price movements in isolation, but to decode the structural forces reshaping availability, grade differentiation, and competitive positioning across the value chain.
The latest PW Consulting Tungsten Hexafluoride Market research was built to meet that challenge. It translates a multi-year historical trajectory and a forward forecast window into a decision-ready framework, giving leadership teams the clarity needed to evaluate sourcing strategies, investment timing, and competitive exposure with greater precision.
Cumulative Momentum and the Forward Growth Arc
The market’s growth narrative over the past half-decade reflects sustained expansion rather than episodic spikes. Historical revenue progression from 2020 through 2025 shows a steady upward path, building from a base above 160 million USD in 2020 to a 2025 position at 215.0 million USD. This trajectory establishes an important baseline: demand has not merely recovered, it has compounded through successive manufacturing cycles, capacity additions, and broader content gains in high-value applications.
Looking ahead, the forecast architecture extends across the 2026–2032 period and points to continued expansion at a projected CAGR of 6.8 percent. The forward numbers illustrate a market that is scaling into a materially larger revenue envelope, with the outlook positioning 2026 near 238 million USD and progressing toward a 2032 level of approximately 345 million USD. These figures are not simply statistical projections; they are a structural signal that demand creation is becoming more durable, more diversified, and increasingly sensitive to technology roadmaps, regional production strategies, and grade-specific sourcing preferences.
For decision-makers, the strategic implication is clear. Growth at this pace rewards early visibility. Companies that wait for market signals to become obvious often find themselves reacting to capacity constraints, grade availability issues, or regional supply interruptions rather than shaping their own positioning. A research framework that maps the progression from historical consolidation to the forecasted expansion window allows executives to test scenarios around procurement timing, regional exposure, and application mix well before those decisions become urgent.
Where Value Is Being Created: Segmentation Logic That Matters
A market of this scale cannot be managed through aggregate totals alone. The operational reality is that different segments behave very differently in terms of procurement cadence, specification sensitivity, pricing tolerance, and supply chain vulnerability. That is why the research framework decomposes the market along axes that matter to real purchasing and production decisions.
Regionally, the market is shaped by clusters of semiconductor manufacturing intensity, industrial material demand, and the evolving geography of gas supply chains. Some regions anchor high-volume advanced manufacturing ecosystems, while others function as growing demand centers or specialized supply nodes. Understanding these regional dynamics is essential because exposure to one geography can carry very different risk-and-opportunity profiles than exposure to another.
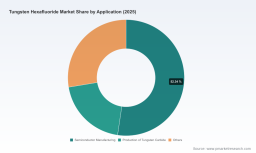
By application, the demand base reflects the relative weight of semiconductor manufacturing, tungsten carbide production, and a broader set of industrial and specialty uses. The semiconductor segment carries a distinct set of requirements: high-purity specifications, tight quality assurance expectations, and procurement tightly linked to fab build-outs and node transitions. Tungsten carbide demand, meanwhile, follows a different rhythm tied to tooling, industrial components, and downstream manufacturing cycles. A third application grouping captures additional specialty and industrial use cases that contribute to overall resilience and diversification.
By grade, the distinction between electronic-grade and industrial-grade material is especially important. Electronic-grade supply tends to command stricter qualification processes, more intensive quality documentation, and stronger sensitivity to continuity and traceability. Industrial-grade demand is shaped by different performance thresholds and cost structures. For buyers, the grade mix is not a detail; it is a procurement architecture decision that influences supplier qualification, inventory strategy, contract design, and risk exposure across the supply base.
The research does not flatten these distinctions into generic averages. Instead, it treats segmentation as a strategic lens: where demand is concentrated, which segments are expanding fastest in structural terms, and how grade and application choices shape competitive positioning. This approach enables a much more grounded evaluation of where opportunity and vulnerability coexist.
Competitive Structure: Concentration, Capability, and Strategic Posture
The tungsten hexafluoride supply landscape is characterized by meaningful concentration, but concentration alone does not tell the full story. Concentration ratios indicate how much of the market is controlled by a smaller group of players, yet the real competitive insight lies in what each participant brings to the market in terms of grade capability, application focus, geographic reach, and supply strategy.
The leading competitive set spans globally integrated electronic-gas specialists, major industrial gas companies with semiconductor-facing portfolios, regional distributors and suppliers, and increasingly active producers aligned with regional demand expansion. Merck KGaA operates with a semiconductor-grade offering oriented toward deposition and metals applications across logic and memory markets, with a footprint that spans major semiconductor manufacturing centers. Linde plc supplies tungsten hexafluoride as an electronic special gas tied to chemical vapor deposition, positioning the material within a broader electronic gases context. Air Liquide S.A. delivers the product through its electronics business unit, supporting semiconductor fabs and display manufacturers internationally. These players reflect the high-specification end of the market, where qualification, consistency, and global service capability often matter as much as volume.
At the same time, other participants illustrate the more diversified and regional dimensions of the supply base. Airgas USA, LLC distributes and supplies tungsten hexafluoride for industrial, synthetic, and analytical chemistry applications, emphasizing breadth of reach and application flexibility. Inhance Technologies emphasizes semiconductor CVD-grade supply with customized specifications and an American-made supply angle that aligns with onshoring considerations. This illustrates how national supply posture is becoming a procurement attribute in its own right, especially where supply security and local presence are weighted alongside price and quality.
On the production side, Chinese manufacturers are expanding to meet growing demand and to strengthen domestic and export capacity. CSSC Special Gas Co., Ltd. has announced a new project designed to add substantial annual capacity, with operations expected in 2027, signaling a deliberate response to demand growth and an intent to scale output in step with market needs. Jiangsu Kaimei Electronic Materials Co., Ltd. manufactures high-purity material for export and maintains a dedicated production capacity, reinforcing the presence of specialized export-oriented supply. Asian Isotope International supplies hexafluorotungsten for semiconductor-related CVD applications, reflecting continued participation across the semiconductor demand chain.
The strategic takeaway is that the market combines concentrated leadership with an active and sometimes divergent set of regional and application-specific players. For buyers, this means qualification strategy, dual-sourcing design, and supplier evaluation must be handled with care. For investors and competitors, it means that capacity announcements, grade capabilities, and regional supply posture can shift bargaining dynamics and availability patterns more quickly than broad market averages suggest.
Industry Dynamics: Supply Security, Material Controls, and Capacity Response
One of the most consequential features of the current market environment is the interaction between raw-material policy and production capacity. Tungsten hexafluoride does not exist in a vacuum; its supply chain is affected by the accessibility of tungsten feedstocks and by the regulatory frameworks that govern their movement. Recent developments have highlighted how quickly material controls can reshape procurement conditions for downstream producers.
Worldwide Inorganic Fluoride Market
China introduced an export licensing system for strategic minerals, including tungsten, in early 2025. This measure affected raw-material procurement pathways for tungsten hexafluoride producers in Japan and contributed to output constraints in the second half of 2026. Around the same timeframe, China’s Ministry of Commerce reinforced export controls on tungsten-related items to Japan and placed tighter oversight on the flow of tungsten products. Taken together, these measures have illustrated how policy can alter the input side of the supply chain with direct consequences for availability, cost structures, and planning confidence.
The impact of such controls is amplified by the role played by Japanese suppliers in the global supply base. With Japanese sources accounting for a meaningful share of global supply, restrictions on raw-material procurement have prompted preparation for production adjustments and have introduced a new layer of uncertainty into sourcing plans. For semiconductor and industrial buyers alike, this is a reminder that even a market with strong overall demand can experience localized disruption when upstream material access is constrained.
Capacity expansion is the market’s structural answer to that uncertainty, but capacity decisions are rarely instantaneous. The planned addition of new production capacity in 2027 reflects a medium-term response to demand growth and supply pressure. This is exactly the kind of dynamic that makes forward-looking research valuable: it helps organizations distinguish between temporary interruptions and more durable shifts in supply geography, grade availability, and competitive balance.
Moreover, these dynamics interact with broader procurement themes such as regionalization, qualification lead times, and the increasing sensitivity of advanced manufacturing to supply resilience. In that environment, the ability to anticipate where supply may tighten, which grades may become more contested, and how competitors are adjusting their sourcing strategies can create meaningful advantages in negotiation timing, inventory planning, and supplier diversification.
What the Research Delivers: Practical Intelligence for Decision-Making
A strong market study is not defined by the size of its forecast alone. It is defined by whether the findings can be used. This research is structured to serve as a practical analytical toolkit rather than a static overview. It provides a connected view of historical performance, forward projections, segmentation patterns, competitive positioning, and the external forces currently reshaping the market.
Inside the full report, readers can expect a detailed examination of market sizing and growth architecture, with context that links the historical baseline to the forecast trajectory and explains the logic behind the projected expansion path. The segmentation analysis goes beyond high-level splits to show how regional, application, and grade differences influence demand behavior, procurement complexity, and strategic exposure. This is especially useful for organizations that need to evaluate where their own exposure sits within the broader market structure and whether that exposure is concentrated, diversified, or shifting.
The competitive assessment provides a working map of the supply base. It situates major electronic-gas participants alongside industrial suppliers and regional producers, enabling a more nuanced reading of concentration, capability, and strategic intent. That matters because supplier relationships in this market are not interchangeable. Qualification requirements, grade capabilities, geographic reach, and service expectations can differ substantially, and the report framework is designed to help decision-makers evaluate those differences with greater precision.
The report also integrates the market dynamics that are shaping near-term behavior. Supply-side developments, regulatory actions, capacity expansion plans, and raw-material policy signals are analyzed not as isolated news items, but as interconnected forces that influence availability, pricing posture, and sourcing risk. By placing these dynamics inside a longer forecast horizon, the research helps users separate short-term disruption from structural realignment.
For strategy teams, this translates into a more reliable basis for scenario planning. For procurement organizations, it supports smarter supplier evaluation and sourcing architecture. For investors and corporate development teams, it offers a clearer picture of where growth is accumulating and what competitive conditions are likely to shape profitability and access. In each case, the objective is the same: to make the market legible well enough for confident action.
Why 2026 Is a Decision-Making Inflection Year
The current environment places a premium on anticipation. Demand is expanding, capacity is being added, and material-flow controls are altering procurement conditions in ways that can affect multiple quarters of planning. In a market like this, information that arrives too late can become a constraint rather than an advantage.
2026 represents an inflection point because several forces are converging at once. Forecast momentum suggests continued growth into the next phase of the cycle. Competitive dynamics reflect both concentration and regional diversification, which means sourcing strategy and supplier evaluation require careful judgment. At the same time, raw-material policy and capacity response are reshaping the practical terms of availability and continuity. Organizations that understand how these forces interact will be better positioned to make sourcing, investment, and risk-management decisions with foresight rather than hindsight.
This is the strategic value of the full research: it gives leadership a structured way to interpret a market that is growing, concentrating, and simultaneously being reshaped by policy and capacity decisions. The macro direction provides the context; the segmentation, competitor mapping, and dynamic analysis provide the operational detail needed to act on that context.
How to Use This Intelligence
The most effective use of this research begins with a clear strategic question. For procurement leaders, the relevant question may be how to structure supplier qualification, dual sourcing, and grade selection in a way that balances cost, continuity, and specification requirements. For corporate strategists, the question may be how regional demand trends and supply-side developments affect long-term sourcing geography and capacity exposure. For investors and market entrants, the question may be where growth is most durable and which competitive conditions will determine access and margin opportunity.
Whatever the starting point, the research is designed to support decision-making at the level where it matters most: the intersection of market structure, competitive behavior, and external dynamics. By combining historical grounding, a forward outlook, and a detailed breakdown of the forces shaping supply and demand, it provides a platform for more informed planning and more confident strategic choices.
Tungsten Hexafluoride Market
Next Steps
The figures, segmentation breakdowns, competitor profiles, and dynamic analyses summarized here are intended to convey the direction and analytical depth of the full study. They establish the strategic frame; the complete report provides the operational detail, contextual interpretation, and scenario-ready structure needed to put that frame to work. For organizations operating in or adjacent to the tungsten hexafluoride market, the value lies not only in understanding where the market is going, but in understanding how to position for it before the next phase of growth, constraint, and competition fully unfolds.
For detailed analysis of this topic, please visit the official page: Tungsten Hexafluoride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


