



PW Consulting: Poultry Breeding Equipment Market to Hit $609.8M by 2032 at 5.54% CAGR

Strategic Imperatives in the Poultry Breeding Equipment Market: A 2026 Outlook
The global poultry industry stands at a critical inflection point. As protein demand scales and production systems modernize, the machinery underpinning breeding operations has evolved from a operational necessity to a strategic asset. For executives, investors, and supply chain leaders operating in animal agriculture, understanding the trajectory of poultry breeding equipment is no longer optional. It is a prerequisite for capital allocation, competitive positioning, and long-term resilience. This industry insight introduces our latest comprehensive market research, designed specifically to equip decision-makers with the analytical rigor required for 2026 planning and beyond.
Poultry Breeding Equipment Market
Why 2026 Demands a Reset in Equipment Strategy
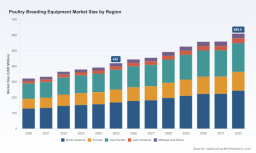
The past half-decade has reshaped the economics of poultry breeding. Historical performance from 2020 through 2025 demonstrates a consistent upward trajectory, with total market valuation climbing from 321.5 million USD to 420.0 million USD. This growth was not merely cyclical; it reflects structural shifts in automation adoption, biosecurity prioritization, and the consolidation of breeding operations around standardized, high-throughput environments. Looking forward, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 5.54 percent. By the close of the forecast window, market revenue is expected to surpass 600 million USD.
These figures are more than macroeconomic indicators. They signal a maturing equipment ecosystem where incremental efficiency gains translate directly into margin protection. Flocks are growing larger, turnaround cycles are tightening, and regulatory scrutiny around disease control has intensified. Equipment procurement decisions made in 2026 will lock in operational characteristics for the next seven to ten years. A feeder system, climate control array, or incubation line selected today dictates throughput capacity, labor dependency, and vulnerability to biological stressors. Strategic buyers must therefore evaluate equipment not as isolated capital expenditures, but as integrated components of a long-term production architecture.
What This Research Delivers: Operational Intelligence Over Abstract Projections
Our market study is structured to bridge the gap between high-level industry narratives and floor-level execution. Rather than offering a single growth curve, the report deconstructs the market across multiple analytical dimensions, each calibrated to answer specific strategic questions. The segmentation framework examines equipment categories including incubation systems, hatching infrastructure, and breeding management platforms, allowing readers to isolate capital intensity, technology readiness, and adoption velocity within each functional area. Application-level analysis further distinguishes between broiler breeding and layer breeding operations, acknowledging that feed conversion targets, cycle lengths, and environmental control requirements diverge significantly between the two production models.
Regional dynamics are mapped with equal precision. The research captures how procurement patterns, infrastructure maturity, and policy environments differ across major geographic corridors. Readers will find contextual guidance on where equipment demand is being pulled by capacity expansion, where it is being pushed by modernization of legacy facilities, and where regulatory or logistical friction is reshaping procurement timelines. This geographic lens is essential for manufacturers evaluating market entry, distributors planning inventory positioning, and end-users benchmarking regional best practices against their own operational baselines.
Beyond segmentation, the report integrates forward-looking modeling that stress-tests growth assumptions against plausible macroeconomic and industry-specific variables. Sensitivity scenarios address fluctuations in feed input costs, shifts in labor availability, and the pace of automation penetration across different farm sizes. By presenting these scenarios side by side, the study enables leadership teams to identify which equipment investments remain robust under downside conditions and which carry elevated exposure to external shocks.
Competitive Landscape: Differentiation, Velocity, and Strategic Positioning
The poultry breeding equipment sector is characterized by a concentrated yet highly active competitive field. Our analysis tracks the strategic postures of leading manufacturers whose product portfolios and deployment footprints shape market standards. Roxell, headquartered in Belgium, has carved a specialist position through automated feeding, drinking, nesting, and climate systems tailored specifically for broiler breeder environments. Big Dutchman, based in Germany, operates as a global leader in smart poultry production equipment, offering integrated feeding, housing, and climate control solutions that emphasize data connectivity and breeder management efficiency. VAL-CO, operating from the United States, focuses on watering systems, feeding architecture, and environmental control equipment designed for the practical demands of commercial breeder farms.
The competitive field also includes Facco from Italy, which provides complete turnkey poultry equipment solutions encompassing breeding systems and integrated farm layouts. TEXHA, based in Slovakia, manufactures both cage-based and cage-free equipment configurations, reflecting the industry's ongoing navigation between conventional and alternative housing philosophies. Hightop Group, headquartered in China, has expanded its footprint as a manufacturer of fully automatic poultry farming equipment, including dedicated breeder systems that combine scale economics with automation features. Together, these players illustrate a market where differentiation emerges from engineering specialization, regional service networks, and the ability to package equipment into cohesive operational ecosystems rather than standalone machines.
Recent corporate activity underscores the pace of strategic execution. In March 2025, Big Dutchman completed the installation of comprehensive poultry production systems at a Hungarian broiler breeder farm, a deployment that highlights the industry's preference for integrated solutions capable of streamlining breeder management across multiple production variables. By March 2026, the same company showcased its newest equipment innovations at the PEAK trade show powered by the Midwest Poultry Federation, signaling continued investment in product iteration and direct engagement with North American procurement audiences. Meanwhile, Facco confirmed its attendance at VIV Europe 2026 in Utrecht, Netherlands, positioning itself to present the latest poultry equipment developments to a concentrated European buyer base. These events are not isolated press items; they are indicators of where engineering priorities are being demonstrated, where sales channels are being reinforced, and how manufacturers are aligning product roadmaps with regional demand clusters.
Regulatory Forces and Biosecurity as Equipment Design Drivers
Equipment selection in poultry breeding cannot be divorced from the regulatory and biosecurity environment. The National Poultry Improvement Plan establishes sanitation procedures for hatchery equipment, including incubators and hatchers, to ensure the integrity of disease-free breeding stock. Under these standards, hatchery equipment must be cleaned and disinfected after each set or transfer, reinforcing a operational reality that equipment design, material selection, and access geometry directly influence compliance feasibility.
For procurement teams, this translates into a practical evaluation criterion: how readily can a system be sanitized without compromising throughput, and how do design choices affect the labor and chemical costs associated with routine disinfection protocols? Equipment that integrates smooth surfaces, removable components, and clear access pathways reduces the friction of compliance, while systems that complicate sanitation routines introduce hidden operational costs and biosecurity risk. The report examines how manufacturers are responding to these requirements through engineering choices and how end-users can factor compliance burden into total cost of ownership calculations.
Beyond sanitation, the broader regulatory context influences ventilation standards, climate control precision, and environmental monitoring integration. As breeding operations face increasing expectations around traceability, animal welfare, and disease containment, equipment that supports data capture and environmental consistency gains strategic value. The research connects these regulatory dynamics to procurement timing, vendor selection criteria, and lifecycle planning, ensuring that compliance considerations are treated as design inputs rather than afterthoughts.
How to Use This Study for 2026 Decision-Making
This market research is designed for operational deployment, not passive reading. Capital planning teams can use the segmentation and forecasting framework to prioritize equipment categories that align with their production mix and growth targets. Procurement leaders can benchmark regional demand patterns against supplier coverage, identifying gaps where localized service capacity or inventory positioning may create competitive advantage. Manufacturers and distributors can leverage the competitive landscape analysis to refine product roadmaps, assess white-space opportunities, and calibrate partnership or channel strategies against the positioning of established players.
The study also supports risk governance. By mapping growth assumptions against operational sensitivities, leadership teams can distinguish between investments that are structurally aligned with industry momentum and those that depend on narrow favorable conditions. The inclusion of biosecurity and regulatory context further ensures that equipment acquisitions are evaluated through the lens of long-term operational resilience, not just upfront pricing or specification checklists.
Detailed regional breakdowns, application-level revenue distributions, company-level capability assessments, and scenario-modeling outputs are reserved for the full report. These components are built to support specific procurement timelines, investment committee reviews, and strategic planning cycles. The executive summary presented here establishes the analytical foundation and directional evidence; the complete study delivers the granular intelligence required to translate strategy into executed decisions.
Next Steps: Accessing the Full Intelligence Package
The poultry breeding equipment market is expanding with structural consistency, but the dispersion of opportunity across equipment types, applications, and regions requires precise navigation. Our full market research report provides the segmented data, competitive profiling, regulatory context, and forward-looking modeling needed to ground 2026 decisions in evidence rather than assumption. For executives seeking to allocate capital, refine vendor selection, or position operations for the next phase of industry modernization, the complete study offers the depth and structure necessary for confident action.
To access the full report, including detailed market size trajectories, segmentation intelligence, competitive benchmarks, and scenario analyses tailored for strategic planning, visit the source page to request the complete intelligence package.
Worldwide Bee Breeding Equipment Market
For detailed analysis of this topic, please visit the official page: Poultry Breeding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


