



PW Consulting: Medical Practice Management Software Market Hits $8.95B in 2025, 9.2% CAGR to 2032

Navigating the Next Wave: Strategic Intelligence for the Medical Practice Management Software Market
The healthcare technology sector is entering a decisive phase. As administrative burdens grow and regulatory frameworks tighten, medical practices are no longer treating practice management software as a back-office utility. It has become the operational backbone connecting clinical care, revenue integrity, and patient experience. For executives, investors, and strategic planners, understanding where this market is heading is no longer optional. It is a prerequisite for capital allocation, vendor selection, and product roadmap planning.
PW Consulting has released a comprehensive market research study on the Medical Practice Management Software Market. This report is built to inform 2026 decision-making with granular market sizing, segmentation analysis, competitive profiling, and forward-looking scenario modeling. What follows is a preview of the market terrain, the structural forces reshaping it, and the analytical rigor you can expect from the full study. The complete dataset, detailed breakdowns, and advanced scenario models are available through the source page, where decision-makers can access the full intelligence package needed to act with confidence.
A Market in Measured but Accelerating Expansion
Over the 2020 to 2025 historical window, the market demonstrated consistent upward momentum, expanding from 6800 Million USD in 2020 to 8950 Million USD in 2025. This trajectory reflects a sector that has absorbed the shock of rapid digital transformation and evolved into a more mature, demand-driven environment. Practices are no longer purchasing software in isolation. They are consolidating administrative workflows, integrating clinical documentation, and seeking platforms that can adapt to shifting reimbursement models and patient expectations.
Looking ahead to the 2026 to 2032 forecast period, the market is projected to continue its expansion at a compound annual growth rate of 9.2 percent. By 2032, the overall market size is anticipated to reach 16559 Million USD. This growth profile signals more than incremental adoption. It points to structural adoption cycles where mid-sized and independent practices, healthcare systems, and specialty groups are reevaluating their technology stacks. The forecast reflects a market where demand is broadening beyond core scheduling and billing into integrated clinical, financial, and engagement workflows.
For 2026 strategy sessions, the most important takeaway is trajectory stability paired with segment-level divergence. While the headline growth path is clear, the drivers behind it vary significantly across practice types, deployment models, and functional priorities. Our full report unpacks these variations without flattening them into averages, giving leadership the precision needed to align investments with the segments that matter most to their portfolio.
Where Value Is Being Created: Structural Shifts in Demand
The market is not expanding uniformly. Demand is being reshaped by three interlocking forces: workflow consolidation, AI-enabled automation, and compliance pressure. These forces are influencing how practices evaluate vendors, what features they prioritize, and how quickly they move from evaluation to deployment.
Workflow Consolidation and Integrated Platforms
Practices are increasingly favoring platforms that unify scheduling, billing, clinical documentation, and patient engagement rather than stitching together point solutions. Integrated deployments reduce data silos, lower administrative handoff errors, and create a cleaner audit trail for compliance and revenue cycle management. This trend is particularly visible among independent and group practices that need to do more with smaller administrative teams. At the same time, larger healthcare systems are seeking enterprise-grade platforms that can scale across specialties while maintaining consistent revenue cycle optimization. The report examines how these preferences are influencing adoption patterns and vendor positioning across the market landscape.
AI as an Operational Inflection Point
Artificial intelligence has moved from a marketing differentiator to a practical operational lever. According to the 2026 Physician Survey on Augmented Intelligence from the American Medical Association Center for Digital Health and AI, 81 percent of physicians are using AI tools professionally, more than double the 38 percent reported in 2023. That surge is reshaping expectations for practice management software. 일선 physicians and administrators now expect AI-assisted clinical documentation, smarter scheduling optimization, and automated revenue cycle support. The market response is accelerating, with product releases and financing activity increasingly centered on AI capabilities.
Recent developments illustrate this shift clearly. AdvancedMD’s 2026 Winter Product Release introduced more than twenty updates, highlighted by the AI Clinical Assistant. Athenahealth’s Spring 2026 release added authorization expiration alerts embedded directly into scheduling and eligibility workflows. DrChrono’s January 2026 update launched a No Show Predictor AI feature that assigns risk scores to upcoming appointments. Meanwhile, Tebra secured 250 million USD in new equity and debt financing led by Hildred to accelerate AI development across clinical documentation, billing automation, and practice marketing. These moves are not isolated product tweaks. They represent a broader reorientation toward AI as a core value driver in practice management.
Compliance Pressure Reshaping Procurement Priorities
Regulatory and reimbursement dynamics are tightening the cost of inaction. The proposed HIPAA Security Rule update would eliminate the distinction between required and addressable safeguards, mandating encryption, multi-factor authentication, and 72-hour system restoration. It is also projected to add a 9 billion USD industry cost in year one. These requirements are pushing security, resilience, and audit readiness up the procurement checklist.
Enforcement intensity is rising in parallel. HHS enforcement accelerated dramatically in 2025, with 19 or more HIPAA settlements announced through August alone for risk analysis failures. For practice management software buyers, this environment changes the evaluation calculus. Functionality remains essential, but vendors that cannot demonstrate robust risk management, secure data exchange, and reliable restoration capabilities face growing scrutiny. Our report places these compliance dynamics in context, showing how they influence purchasing timelines, contract terms, and long-term vendor viability.
Competitive Landscape: Differentiation in a Consolidating Arena
The competitive field is defined by a mix of established platforms, cloud-native entrants, and specialty-focused vendors. Concentration levels indicate a market that is still broad enough for differentiated positioning while increasingly shaped by scale players. The top three competitors account for 35.5 percent of the market, while the top five reach 48.2 percent. This concentration suggests that while no single vendor dominates outright, leadership positions are beginning to consolidate around platforms that can deliver integration depth, AI-enabled workflow support, and strong revenue cycle capabilities.
Several core companies define the current battleground, each bringing a distinct strategic profile:
- Athenahealth, based in Boston, Massachusetts, provides cloud-based medical practice management software with integrated EHR, revenue cycle management, scheduling, and patient engagement tools targeted at independent and group practices.
- AdvancedMD, headquartered in South Jordan, Utah, offers cloud-based EHR, practice management, and AI-powered tools with specialty-specific workflows for front office, billing, and patient engagement.
- Veradigm LLC, formerly Allscripts Healthcare Solutions, delivers specialty-adaptable practice management software for administrative, financial, and clinical operations across multiple medical specialties.
- eClinicalWorks, located in Marlborough, Massachusetts, provides comprehensive medical practice management and EHR software focused on independent practices, including scheduling, billing, and reporting.
- CureMD, based in New York, New York, offers easy-to-use medical practice management and EHR solutions optimized for cost-effective independent practices.
- Greenway Health, headquartered in Atlanta, Georgia, supplies integrated practice management and EHR platforms with emphasis on specialty care and seamless data exchange.
- Kareo, from Salt Lake City, Utah, delivers cloud-based practice management software specifically for independent medical practices, including billing and front-office automation.
- Practice Fusion, based in San Francisco, California, offers cloud-based EHR and practice management software with certified tools for ambulatory care and billing.
- NextGen Healthcare, also in Atlanta, Georgia, provides enterprise-grade practice management and EHR solutions with a strong focus on healthcare systems and revenue cycle optimization.
- ChartLogic, based in Fort Worth, Texas, supplies practice management and EHR software including e-prescribing, revenue cycle, and patient portals for independent providers.
- OmniMD, headquartered in Overland Park, Kansas, delivers web-based practice management software with tools for scheduling, billing, and clinical documentation in ambulatory settings.
The strategic question for 2026 is not simply who leads today, but how each vendor is positioned to absorb the compliance burden, scale AI capabilities, and maintain data interoperability across diverse practice settings. Some players are leaning into specialty workflows and independent practice economics. Others are emphasizing enterprise-grade revenue cycle optimization or cloud-native automation. Our report evaluates these postures in detail, mapping capabilities to the segments where they create the most competitive advantage.
What the Report Delivers: From Market Sizing to Actionable Strategy
This study is designed to support both strategic planning and operational decision-making. It integrates historical performance, forward-looking forecasts, segmentation analysis, competitive profiling, and industry dynamics into a single decision framework. Rather than presenting high-level commentary, the report grounds each insight in structured data and practical interpretation.
The report covers the full market arc, with a base year of 2025 and a historical review spanning 2020 to 2025. The forecast period extends from 2026 to 2032, enabling leadership to test near-term commitments against longer-term adoption cycles. Market sizing is presented in Million USD, with growth trajectories evaluated through a 9.2 percent CAGR lens. This structure allows readers to understand not only where the market stands, but how momentum is likely to build across the forecast horizon.
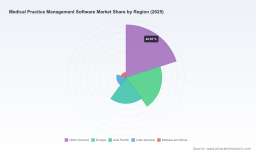
Beyond top-line sizing, the study breaks down demand by type, application, and region. These segmentation views help identify where adoption is strongest, which functional categories are attracting the most investment, and how geographic patterns differ across maturity levels and practice structures. Importantly, the report connects segmentation to decision relevance, showing how each slice of the market relates to vendor strategy, purchasing behavior, and implementation risk.
Competitive analysis is another central pillar. The report profiles the companies shaping the market, examining their strategic focus, target segments, and recent product or financing activity. This is paired with concentration analysis to give readers a realistic picture of market structure, competitive intensity, and the room available for differentiated positioning. For organizations evaluating partnerships, procurement, or market entry, this section provides a practical map of who is competing on which dimensions.
The research also integrates industry context that directly affects market behavior. Regulation, reimbursement pressure, AI adoption trends, and enforcement activity are treated as active market drivers rather than background noise. The goal is to help leaders anticipate how these forces will alter purchasing timelines, feature priorities, and vendor requirements in 2026 and beyond.
How Decision-Makers Can Use the Study
The full report is structured to support a range of strategic use cases. Executive teams can use it to validate market entry assumptions, prioritize investment areas, and benchmark growth expectations. Procurement and IT leaders can use the segmentation and competitive sections to refine vendor shortlists and align feature requirements with market realities. Investors and financial analysts can use the forecast framework and concentration data to assess market maturity, growth durability, and the distribution of value across participants.
Because the market is expanding while becoming more complex, the most valuable insights are often the ones that connect macro trends to segment behavior. That is where the full study adds the most weight. It isolates the demand patterns that averages can obscure and highlights the operational implications that matter for planning cycles.
Why 2026 Demands a More Precise Read on This Market
This is a year when technology expectations, compliance requirements, and operational economics are converging. Practices are under pressure to reduce administrative friction, protect revenue integrity, and meet rising security expectations. Vendors are racing to embed AI, strengthen interoperability, and demonstrate tangible workflow improvements. In that environment, strategy built on broad generalizations is increasingly risky.
Medical Practice Management Software Market
Legal Practice Management Software Market
The Medical Practice Management Software Market is large enough to offer meaningful opportunity and fragmented enough to reward targeted positioning. A 9.2 percent CAGR through 2032 indicates durable expansion, but the real strategic value lies in understanding which demand pockets are accelerating, how competitive pressure is concentrating, and where regulatory and reimbursement shifts will reshape buyer behavior.
This preview has outlined the market’s direction, the forces shaping it, and the analytical depth of the full study. The complete report provides the detailed segmentation, company-level assessments, scenario-ready forecasts, and compliance-context analysis needed to move from awareness to action. For organizations preparing decisions in 2026, the source page offers the full intelligence package, including the granular breakdowns and proprietary analysis that support confident, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Medical Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


