



Precision Industries Forecasts Cold Heading Machine Market to Hit $4.69B by 2032 With 4.01% CAGR

Navigating the Cold Heading Machine Market: Strategic Intelligence for 2026 and Beyond
The cold heading machine market stands at a critical inflection point. As manufacturing precision demands escalate and fastener production scales to meet complex industrial needs, decision-makers require more than surface-level forecasts. They need actionable intelligence that connects machine specifications, regional supply chains, application-specific demand drivers, and competitive positioning into a coherent strategic narrative. This introduction frames the Cold Heading Machine Market research report by PW Consulting, a comprehensive study designed to equip C-suite executives, procurement leaders, and strategic planners with the clarity needed for 2026 decision-making and multi-year investment planning.
Why This Research Matters Now
Cold heading remains one of the most efficient manufacturing processes for producing high-volume fasteners, pins, and precision components. The ability to form metal at or near room temperature—without the thermal degradation risks of hot working—offers distinct advantages in dimensional accuracy, material grain structure, and production economics. Yet the machines that execute these processes are evolving rapidly. Multi-die configurations, advanced automation integration, and tighter tolerance capabilities are reshaping procurement criteria across automotive, electronics, industrial equipment, and aerospace supply chains.
Our study delivers a rigorous, data-grounded assessment of the market across a structured historical window and a forward-looking forecast horizon. The analysis spans from 2020 through 2025, capturing the market's recent trajectory, and extends through 2032 to illuminate long-term demand pathways. For 2026 strategists, this temporal range is invaluable: it isolates the post-2025 recovery signals, quantifies the direction and pace of growth, and exposes the structural shifts that will define competitive advantage in the years ahead.
The market measured in this report is expressed in Million USD. From a 2025 base year assessment of 2,923.01 Million USD, the forecast period projects a market that advances to approximately 3,709.16 Million USD in 2026, climbs steadily through the late 2020s, and reaches 4,685.24 Million USD by 2032. The overall compound annual growth rate across the 2026–2032 forecast window registers at 4.01 percent. These macro figures anchor the study, but they are only the starting point. The real strategic value lies in how this growth decomposes across machine types, end-use applications, and geographic corridors—and in the operational insights the report surfaces beneath the headline numbers.
Report Architecture: What Decision-Makers Will Find Inside
This study is structured for immediate practical use. Rather than presenting a static collection of charts, the research is organized around the strategic questions that procurement directors, plant managers, and market entry strategists face when evaluating cold heading equipment investments.
Market Sizing and Historical Trajectory
The report reconstructs the market's behavior from 2020 through 2025, a period marked by shifting production priorities, supply chain adjustments, and variability in capital expenditure cycles. By tracing the path from 3,558.00 Million USD in 2020 through to the 2025 base year assessment, the study identifies the inflection points that shaped buyer behavior and supplier responses. Readers will gain a clear picture of how demand fluctuated, where resilience emerged, and which segments absorbed capacity during softer periods.
Forecast Framework and Growth Drivers
Beyond 2025, the analysis projects a market that regains momentum and expands at a measured, sustained pace. The forecast portion of the report links this trajectory to concrete demand catalysts: fastener volume requirements tied to vehicle electrification and lightweighting, electronics miniaturization driving precision component needs, industrial equipment refurbishments and expansions, and aerospace program ramp-ups. Each driver is mapped to the machine categories and regional demand pools it influences, giving strategists a framework for scenario planning rather than a single-point prediction.
For those evaluating capacity additions, replacement cycles, or technology upgrades, the forecast window through 2032 provides a multi-year canvas. The progression from the 2026 baseline toward the 2032 endpoint reveals where growth concentrates, which years carry the steepest incremental demand, and how the market's composition is expected to evolve. This temporal granularity is essential for aligning procurement lead times, capital budgeting cycles, and production planning with market realities.
Segmentation for Targeted Strategy
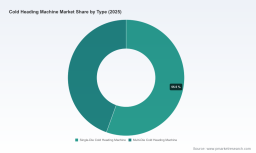
One of the study's core strengths is its segmentation architecture. Market demand is analyzed across machine type, end-use application, and geographic region, enabling readers to isolate the pockets of opportunity most relevant to their strategic posture. Whether a company focuses on single-die precision lines or multi-die high-throughput systems, whether its customer base skews toward automotive components, electronics, industrial equipment, or aerospace, and whether it targets mature production hubs or emerging manufacturing corridors, the segmentation layer provides the lens needed to prioritize resources and tailor value propositions.
Importantly, the report avoids the reductive approach of presenting isolated regional or application shares without context. Instead, it situates each segment within the broader demand ecosystem, explaining how subsegments interact, where substitution dynamics occur, and which structural factors will accelerate or temper growth in specific pockets of the market over the forecast period.
Competitive Intelligence and Firm-Level Insights
Market growth is meaningless without understanding who captures it. The competitive landscape section profiles the leading entities shaping the cold heading machine sector, offering readers a grounded view of supplier capabilities, geographic footprints, and market positioning. The study examines established manufacturers and specialized suppliers that collectively define the industry's current architecture, including National Machinery LLC, headquartered in Tiffin, Ohio, recognized globally for advanced cold and warm forming machinery, process technology, and customer support for precision cold forming solutions; Hariton Machinery Company, Inc., based in New York, which supplies new and used cold header machines, multi-station headers, and related cold heading equipment; SACMA Group of Limbiate, Italy, known for cold heading machines including the KSP series headers for fastener production; Chun Yu Group, operating through Chun Zu Machinery Industry Co. Ltd in China, producing cold heading machines and forming equipment for the fastener industry; GFM GmbH Steyr of Steyr, Austria, supplying high-performance cold heading machines and forming systems; Hatebur Umformmaschinen AG of Grenchen, Switzerland, a manufacturer of precision cold heading and forming machines; Asahi Sunac Corporation of Japan, providing cold heading machine solutions for fastener and precision parts production; Wrentham Tool Group LLC of Massachusetts, specializing in cold heading tools and equipment for machine manufacturers; Sakamura USA Inc., a U.S.-based distributor and provider of Sakamura cold heading machines; and HUBEI TRI-RING METALFORMING EQUIPMENT CO. of China, manufacturing metalforming and cold heading equipment.
Beyond firm profiles, the report examines recent market activity that signals evolving competitive intensity. For example, Krevere's participation in the International Fastener Show IFS 2026 in Shanghai, where it showcased cold heading machines including the KRBF-64S model, illustrates the ongoing product introductions and trade presence that keep the competitive environment in motion. Such developments matter for procurement teams tracking supplier innovation cycles and for strategists assessing which players are actively expanding their visibility in key regional venues.
Market Dynamics: Structural Forces Shaping the Landscape
Understanding where the market is going requires grasping the forces that constrain and accelerate it. The report disentangles these dynamics into several interconnected themes.
Cost Efficiency, Precision, and Process Evolution
Cold heading's enduring appeal rests on its ability to deliver high-volume output with tight tolerances and favorable material utilization. As downstream industries push for lighter components, higher strength-to-weight ratios, and greater consistency in fastener performance, machine builders have responded with designs that improve strike accuracy, reduce secondary operations, and integrate process monitoring. The study examines how these technological and process trends are translating into buyer preferences, what trade-offs exist between single-die and multi-die configurations in different production contexts, and where automation and tooling advancements are reshaping total cost of ownership calculations.
Cold Forging Machine Market
Regional Manufacturing Footprints and Demand Geography
The market does not grow uniformly across the globe. Production capacity, fastener consumption patterns, and industrial policy environments differ markedly by region, and these differences shape both demand and competitive entry strategies. The research maps how demand pools align with regional manufacturing strength and where export-oriented equipment flows intersect with local production needs. For organizations evaluating market entry, supplier localization, or regional capacity deployment, this geographic lens is essential for avoiding misallocated investment and for identifying where near-term volume and long-term structural demand diverge.
Cold Heading Machine Market
The study covers the full regional spectrum, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, situating each within the broader demand architecture rather than treating them as isolated silos. Readers will understand not just which regions carry significant volume, but how regional dynamics—industrial base maturity, trade flows, and application mix—interact with machine type and end-use segmentation to create distinct strategic environments.
Standards, Safety, and Compliance as Operating Parameters
Machinery procurement and deployment do not occur in a regulatory vacuum. The report integrates the standards and safety frameworks that shape equipment specification, installation, and operation. ISO 4954-1:2024 specifies requirements for non-alloy and alloy steels intended for cold heading and cold extruding delivered as wire rods and wire, establishing a material-grade reference that ties directly to cold heading process performance. EN 10263:2017 serves as the standard reference for cold heading steel wire grades, including boron-alloyed and alloyed steels, further anchoring material selection to machine capability and output quality. On the safety side, the U.S. Occupational Safety and Health Administration enforces ANSI B11.7-2020 safety requirements for cold headers and cold formers, a framework that remains active and relevant for operators and equipment purchasers alike.
These standards are not peripheral details; they influence machine design expectations, supplier qualification, operator training, and the risk profile of capacity investments. By incorporating this compliance layer, the report equips readers to assess supplier offerings and project requirements with a fuller understanding of the operational environment in which cold heading equipment must perform.
Competitive Concentration and Market Structure
The distribution of market share among leading participants provides a window into the industry's competitive architecture. The study notes that the top three firms collectively account for approximately twenty-five percent of market revenue, while the top five reach roughly thirty percent. This concentration profile suggests a market where scale advantages, technological differentiation, and regional reach matter, but where meaningful headcount of specialized suppliers also persists. For strategists, this balance between concentration and fragmentation has implications for supplier negotiation leverage, partnership selection, and the feasibility of displacing incumbents in targeted segments.
The report examines how this structure is likely to evolve as growth accelerates through the forecast period, where consolidation pressure may intensify, and which types of firms—broad-line manufacturers, application specialists, or regionally anchored suppliers—are best positioned to capture incremental share. Rather than offering a static snapshot, the analysis connects concentration data to the strategic behaviors that will shape competitive outcomes over time.
Translating Insights into 2026 Action
Strategic reports derive their value from how they inform decisions. This study is built with that principle at its core. Across procurement, capacity planning, competitive positioning, and market entry, the research provides a framework for converting market intelligence into concrete action.
For procurement teams, the segmentation and competitive analysis clarify which machine types align with specific application requirements and which suppliers offer credible capability in those niches. The standards and safety context supports more rigorous equipment qualification, reducing the risk of downstream fit or compliance issues. For capacity planners and plant executives, the historical trajectory and forecast pathway inform timing decisions—when to accelerate replacement cycles, where to concentrate automation investments, and how to sequence expansions against anticipated demand increments. For market strategists evaluating expansion or new product lines, the regional and application lenses identify where demand momentum is strongest and where competitive barriers are most navigable.
Crucially, the report's structure is designed to support scenario thinking rather than point forecasts alone. By revealing how demand drivers, machine categories, and regional dynamics interact, it enables decision-makers to test assumptions, stress-test investment plans, and align internal timelines with external market rhythms.
What the Full Study Delivers
This introduction previews the analytical rigor and strategic relevance of the complete Cold Heading Machine Market research. The full report extends this foundation with detailed segmentation analytics, deeper competitive profiling, granular demand-driver mapping, standards and safety integration, and forward-looking scenario considerations that together form a comprehensive decision-support toolkit. It is written for executives who need to move beyond headline market figures and into the operational and strategic detail that determines whether a 2026 investment, procurement decision, or market move lands effectively.
The complete analysis, including the full segmentation breakdowns, firm-level evaluations, regional demand contexts, and the nuanced interpretation of growth drivers across the 2026–2032 horizon, is available through the full report. Readers seeking the precise figures, segment-level decompositions, and the complete competitive landscape assessment are encouraged to access the source study to obtain the complete intelligence package.
In a market where precision, timing, and supplier selection carry outsized consequences, the difference between reactive planning and strategic advantage comes down to the quality of the intelligence underpinning decisions. This research is designed to deliver exactly that—grounded in data, attentive to dynamics, and oriented toward the actions that matter in 2026 and the years that follow.
For detailed analysis of this topic, please visit the official page: Cold Heading Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


