



PW Consulting: UPVC Window And Door Market Hits $28.4B In 2025, Projected 6.4% CAGR To $43.61B By 2032

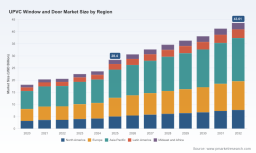
Strategic Horizons: Navigating the UPVC Window and Door Market in 2026 and Beyond
Executive Overview
The global construction and renovation landscape is undergoing a significant transformation, driven by stringent energy efficiency regulations, urbanization trends, and a growing emphasis on sustainable building materials. Within this evolving ecosystem, Unplasticized Polyvinyl Chloride (UPVC) windows and doors have emerged as a cornerstone solution for manufacturers, contractors, and homeowners alike. Our latest market intelligence report offers a comprehensive deep dive into this sector, providing the strategic clarity necessary for informed decision-making throughout the 2026-2032 forecast period.
This analysis serves as a strategic preview of our full market research publication. While we highlight the macro-economic trajectories and competitive forces shaping the industry, the complete dataset—including granular segmentation splits, precise regional revenue shares, and detailed financial modeling—remains an exclusive resource for our clients. Understanding the broad contours of the market is the first step; mastering the specific data points is where competitive advantage is forged.
Market Trajectory and Macro Economic Indicators
The UPVC window and door market has demonstrated robust resilience and growth over the past five years. Historical data from 2020 through 2025 indicates a consistent upward trend, reflecting the material's increasing adoption in both replacement markets and new construction projects. The market valuation, expressed in USD billions, has progressed steadily, signaling strong underlying demand fundamentals.
Looking ahead, the forecast period from 2026 to 2032 projects a continued expansion phase. Industry analysts anticipate a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. This growth is not merely linear but is influenced by shifting demographic patterns, infrastructure spending, and regulatory pushes toward energy conservation. The trajectory suggests that by the early 2030s, the market will reach significantly higher valuation thresholds, presenting substantial opportunities for stakeholders who position themselves correctly during the current cycle.
Key macro indicators suggest that the industry is moving past a phase of volatility into a period of structured growth. However, realizing the full potential of this growth requires more than just observing top-line numbers. It demands an understanding of how different product types, application sectors, and geographic regions contribute to the aggregate figure. Our full report dissects these layers, providing the specificity needed to allocate capital efficiently and identify high-yield segments.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global players and agile regional specialists. Concentration metrics indicate a moderately consolidated environment where top-tier manufacturers hold significant influence. The CR3 and CR5 ratios suggest that while a few key players dominate the landscape, there remains ample room for differentiation through technology, design, and regional presence.
UPVC Window and Door Market
Leading manufacturers are actively maneuvering to secure their positions through capacity expansion, strategic partnerships, and innovation in profile systems. Major entities such as VEKA Group, Rehau, aluplast, and Deceuninck continue to set benchmarks in PVC profile systems and energy-efficient solutions. These companies are not merely competing on price but are engaging in sophisticated value-chain integrations. For instance, recent collaborations have focused on sustainability initiatives, such as partnerships aimed at promoting green construction practices and enhancing the lifecycle efficiency of window systems.
Regional dynamics also play a crucial role in competitive strategy. In North America, companies like United Window & Door are expanding production capacities to meet local demand, reducing reliance on imported profiles and strengthening supply chain resilience. Simultaneously, in Asia Pacific, manufacturers like Fenesta and LG Hausys are leveraging local manufacturing advantages to cater to booming residential and commercial sectors. TWR Group in the UK and other fabricators are also adapting their offerings to meet specific trade and commercial requirements.
Recent developments highlight the pace of change. Facility expansions involving significant capital investment have been announced to accommodate growing order books. Product launches introducing new systems, such as tilt-turn solutions and triple-track patio doors, indicate a focus on diversifying portfolios to capture niche demands. Furthermore, partnerships regarding finishes and materials suggest an industry-wide push toward aesthetic customization and performance enhancement. Understanding the specific timing and impact of these moves is critical for benchmarking one's own strategy against the market leaders.
Industry Dynamics: Cost Structures and Regulatory Pressures
One of the most critical factors influencing margin stability and pricing strategies is the cost of raw materials. UPVC profile costs account for a substantial portion of manufacturing expenses, making resin price fluctuations a key risk variable. Recent market intelligence indicates divergent trends across major regions. In Europe, PVC resin prices have seen upward pressure, impacting cost structures for profile manufacturers. Conversely, in markets like India, price adjustments have followed global supply chain realignments, presenting a different cost environment. These disparities create complex challenges for multinational strategists who must navigate varying input costs while maintaining competitive pricing.
Regulatory frameworks are equally influential. Government initiatives aimed at affordable housing and energy efficiency are acting as primary demand drivers. In the European Union, plans emphasizing renovation-first approaches and stringent energy efficiency standards are accelerating the replacement of old fenestration systems with high-performance UPVC alternatives. Industry associations have welcomed these developments, recognizing the potential for increased market volume. However, regulatory shifts also bring compliance complexities. For example, changes in logistics schemes regarding PVC window profile transport pallets require operational adjustments.
In emerging markets, protectionist measures are gaining traction. Industry bodies in regions like India have appealed for import controls on uPVC profiles to safeguard domestic manufacturing interests. Such policy developments can alter competitive dynamics overnight, favoring local producers while potentially restricting supply options for assembled goods. Monitoring these regulatory signals is essential for risk mitigation. Our detailed report provides a nuanced analysis of how these dynamics vary across sectors and regions, offering actionable insights on navigating the regulatory maze.
Segmentation and Application Opportunities
The market is multifaceted, segmented by window and door types, applications, and geography. While the aggregate market size provides a high-level view, the real strategic value lies in understanding the performance of specific segments. Product diversity ranges from casement and sliding systems to tilt and turn configurations and French doors. Each type serves different functional and aesthetic needs, commanding different market shares and growth rates. For example, energy-efficient tilt-turn systems are gaining traction in markets with strict thermal performance codes, while sliding systems remain popular in space-constrained residential settings.
Application-wise, the residential sector typically constitutes the largest share of demand, driven by housing starts and renovation activities. Commercial applications follow, fueled by office complexes, hospitality projects, and institutional buildings. Industrial applications, while smaller in volume, offer specialized requirements regarding durability and security. The interplay between these segments determines the overall health of the market. A slowdown in residential construction might be offset by a surge in commercial retrofitting, depending on economic conditions.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities. Developed markets may focus on replacement cycles and energy upgrades, while developing markets might see higher volume from new infrastructure projects. Our complete analysis breaks down these regional nuances without relying on broad generalizations, providing the specific intelligence needed to tailor go-to-market strategies.
Strategic Value for 2026 Decision Making
For executives and strategists, the ability to anticipate market shifts is paramount. The 2026 landscape offers both risks and rewards. On one hand, rising raw material costs and regulatory changes pose challenges to margin management and compliance. On the other hand, government incentives for energy efficiency and housing create clear demand pull. Navigating this environment requires more than intuition; it requires data-backed precision.
PVC Window Profile Market
Our market research report is designed to equip leaders with the tools necessary to make decisive moves. Whether it is evaluating potential mergers and acquisitions, planning capacity expansions, or refining product portfolios, the data provided serves as a foundational asset. The report goes beyond static numbers to offer context on how competitive moves, such as new facility openings or strategic partnerships, are reshaping the battlefield.
Furthermore, understanding the concentration of market power helps in assessing barriers to entry and the viability of niche strategies. Companies can identify gaps where innovation can disrupt incumbent players or where consolidation might be beneficial. The insights into recent developments—such as specific product launches and investment rounds—provide a real-time view of where competitors are placing their bets. This intelligence allows organizations to align their own roadmaps with emerging trends rather than reacting to them after the fact.
The forecast period through 2032 offers a long-term horizon for planning. Stakeholders can model various scenarios based on the projected CAGR and market valuation trends. This long-view perspective is crucial for capital-intensive decisions in manufacturing and distribution. By integrating macro trends with segment-specific data, organizations can build robust strategies that are resilient to short-term volatility while capitalizing on long-term growth vectors.
Conclusion
The UPVC window and door market stands at a pivotal juncture. The convergence of economic recovery, regulatory support for energy efficiency, and technological innovation in profile systems creates a fertile ground for growth. However, realizing this potential requires a sophisticated understanding of the market's inner workings.
This article has provided a high-level overview of the market's trajectory, competitive forces, and dynamic pressures. To access the complete landscape of intelligence discussed herein—including precise segmentation data, detailed regional breakdowns, and exhaustive company profiles—we invite you to explore our full market research report. The detailed intelligence contained within is designed to transform uncertainty into strategic clarity, empowering your organization to lead rather than follow in the years ahead.
For detailed analysis of this topic, please visit the official page: UPVC Window and Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


