



PW Consulting: Smart Building Market Hits $111B in 2025, Projected to Reach $298.3B by 2032 at 15.2% CAGR

Unlocking the 2032 Horizon: Strategic Intelligence for the Smart Building Revolution
The trajectory of the global commercial real estate and infrastructure sectors has fundamentally shifted. As we move through 2026, the smart building market is no longer a niche segment of facility management but a central pillar of corporate sustainability, operational efficiency, and tenant experience strategies. For C-suite executives, investors, and industry stakeholders, understanding the velocity and direction of this transformation is critical for capitalizing on emerging opportunities and mitigating regulatory risks.
PW Consulting has synthesized extensive primary and secondary research to deliver a comprehensive Smart Building Market study, covering the historical performance from 2020 through 2025 and providing a robust revenue forecast from 2026 to 2032. This article serves as a strategic overview of the intelligence contained within our latest report, demonstrating why this analysis is an indispensable tool for navigating the next seven years of market evolution.
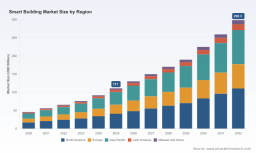
The numbers tell a compelling story of rapid acceleration. From a market size of US 46.0 Billion in 2020, the industry has expanded dramatically to reach an estimated US 111.0 Billion in 2025. This growth underscores the pent-up demand and the urgent adoption of automation technologies following the global shifts in work patterns and energy consciousness over the past few years. As we look forward, the momentum shows no signs of slowing. The total market revenue is projected to cross the US 130.12 Billion mark in 2026, continuing its ascent toward a transformative milestone of nearly US 298.3 Billion by 2032.
Driving this expansion is a compound annual growth rate (CAGR) of 15.2 percent over the forecast period. For strategy teams, this metric signals that smart building technologies are entering a phase of mainstream maturity where scale becomes as important as innovation. However, raw market size and growth rates are only the starting point. The true value of the PW Consulting study lies in decoding the underlying dynamics, competitive pressures, and technological standards that will determine which players thrive and which are left behind in this hyper-competitive environment.
The Anatomy of Market Acceleration
The surge from 2020 to 2025 was characterized by a rapid digitalization of building operations, driven by the need for remote monitoring, energy cost volatility, and heightened occupant health expectations. The jump from US 76.01 Billion in 2023 to US 91.93 Billion in 2024, followed by the breakout to US 111.0 Billion in 2025, reflects a decisive market shift. Organizations are moving beyond pilot projects to enterprise-wide deployments.
Looking ahead to the 2026-2032 forecast horizon, the growth trajectory suggests a market that is consolidating around integrated platforms. The revenue jump from US 130.12 Billion in 2026 to US 149.86 Billion in 2027, and the subsequent climb to US 224.76 Billion by 2030, indicates that adoption will deepen across diverse building portfolios. By 2032, when the market is anticipated to reach US 298.3 Billion, the definition of a smart building will have expanded to encompass fully autonomous energy management, predictive maintenance ecosystems, and seamless occupant interaction layers. Our analysis deconstructs these phases to identify the inflection points where investment yields the highest return.
Segmentation Insights and Strategic Allocation
While the aggregate market figures provide the macro context, the allocation of revenue across different dimensions reveals where the battle for market share is being fought. Our research dissects the market into key components, building types, and geographic regions to highlight concentration and opportunity.
A significant majority of current market activity is concentrated within the Solutions segment, accounting for the lion's share of revenue generation compared to Services. This dominance indicates that the market is prioritizing software platforms, automation engines, and integrated control systems over standalone consulting or maintenance services. The value is shifting toward intellectual property and scalable digital products. However, our report also provides a granular look at how the services component is evolving, particularly in areas such as integration support and lifecycle management, which remain essential for successful deployment.
In terms of building typologies, the market is no longer solely dominated by one sector. Commercial properties continue to drive substantial volume, reflecting the high density of enterprise deployments. Yet, residential and industrial applications are emerging as high-growth vectors. The residential segment is seeing a wave of upgrades driven by consumer demand for energy efficiency and home automation, while the industrial sector is leveraging smart building controls for safety, compliance, and operational resilience. Our study quantifies the interplay between these segments, helping clients identify cross-sector synergies and market gaps.
Building Management System Market
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America remains a powerhouse of adoption, fueled by mature infrastructure and strong enterprise investment. Europe is undergoing a regulatory-led transformation, while Asia Pacific presents rapid urbanization and digital leapfrogging opportunities. Latin America and the Middle East and Africa represent emerging frontiers with distinct growth drivers. The report avoids superficial generalizations, offering a nuanced view of regional maturity levels, investment climates, and specific adoption barriers that vary by location. By understanding these regional weights, multinational corporations can tailor their market entry or expansion strategies with precision.
Competitive Landscape: Titans and Disruptors
The smart building ecosystem is populated by a mix of established industrial giants, technology enablers, and specialized innovators. Market concentration data reveals that a core group of players holds significant sway, with the top three competitors collectively commanding more than half of the market revenue, while the top five extend their influence further. This level of concentration suggests that while barriers to entry exist, competitive intensity remains high as incumbents vie for dominance in platform ecosystems.
At the forefront of this landscape are companies that have built comprehensive portfolios spanning hardware, software, and analytics. Siemens AG continues to leverage its integrated building automation capabilities, utilizing platforms like Desigo CC and Building X to unify HVAC, lighting, security, and fire systems. Their focus on energy optimization and remote control positions them as a critical partner for large-scale infrastructure projects. Similarly, Johnson Controls International plc has reinforced its leadership through the OpenBlue smart building platform and Metasys building management system, integrating AI-driven analytics and cloud services to drive portfolio optimization and enhance occupant experience.
Schneider Electric SE contributes to the competitive fray with its EcoStruxure Building Operation platform, offering integrated control across HVAC, power, lighting, and access for commercial and campus buildings, backed by BACnet certification to ensure interoperability. ABB Ltd. counters with its ABB Cylon and i-bus KNX platforms, focusing on building automation, energy management, and HVAC controls, while also exploring integration opportunities within broader smart ecosystems such as SmartThings.
The landscape also includes major technology and industrial players adapting their core competencies to the built environment. Honeywell International Inc. is deploying AI and IoT solutions for predictive maintenance, security, and energy optimization, adding a layer of intelligence to traditional building controls. Cisco Systems, Inc. provides the foundational networking infrastructure and cybersecurity solutions necessary to support connected smart building systems and the proliferation of IoT devices, recognizing that connectivity is the backbone of the smart building. IBM Corporation brings its strength in cloud computing, AI, and analytics to building management, offering predictive insights that transform raw data into actionable strategy.
Regional and specialized players are also making their mark. Hitachi, Ltd. focuses on automation and control systems tailored for energy management and environmental monitoring, addressing the growing need for sustainability in Asian and global markets. Legrand SA rounds out the competitive field with its expertise in electrical installation and smart building solutions, delivering value through lighting, access, and automation technologies that enhance both functionality and user experience.
Recent developments illustrate how these companies are competing for mindshare and wallet share. In April 2025, Johnson Controls released a commissioned Forrester study quantifying up to 155 percent ROI and 10 percent energy savings from its OpenBlue platform across a composite customer model. This type of evidence-based marketing underscores the industry's shift toward demonstrating tangible financial returns to justify capital expenditures. Our report analyzes such developments to help clients benchmark vendor claims against market realities.
Regulatory Tailwinds and Industry Standards
The smart building market is operating within a dynamic regulatory environment that acts as both a catalyst and a constraint. In Europe, the revised Energy Performance of Buildings Directive (EU/2024/1275) entered into force on 28 May 2024, with a transposition deadline of 29 May 2026 for EU countries. This directive mandates significant improvements in building energy efficiency and promotes the deployment of building automation and control systems (BACS). Furthermore, EU countries are required to submit draft national building renovation plans by 31 December 2025 and final plans by 31 December 2026. The European Commission's adoption of a support package offering practical guidance to EU countries for transposing these requirements, including specific BACS mandates, signals a tightening regulatory framework that will drive demand for compliant solutions.
The industry is also responding to the need for harmonization and interoperability. Standardization efforts such as CEN/TR 18081:2024 specify the requirements of hardware and functions for products and systems for the control and management of HVAC in smart building automation. This standard, alongside the development of open international standards like KNX, LonWorks, and BACnet for BACS, is crucial for ensuring interoperability in smart building systems. As noted in recent academic research, these standards mitigate the risk of vendor lock-in and facilitate the integration of multi-vendor environments. Our study evaluates the impact of these regulatory and standardization trends on market growth, procurement cycles, and technology selection criteria.
Why This Study Matters for 2026 Decision-Making
In an era of information overload, clarity and actionable intelligence are the ultimate competitive advantages. The PW Consulting Smart Building Market report is designed for decision-makers who require more than high-level estimates. It provides a detailed map of the market landscape, enabling stakeholders to:
- Identify high-growth segments and geographic regions where investment can yield superior returns.
- Understand the competitive positioning of key players and anticipate shifts in market share.
- Align product development and go-to-market strategies with regulatory timelines, such as the EU building renovation plan deadlines and BACS requirements.
- Evaluate the financial impact of technologies by referencing independent studies and industry benchmarks.
- Navigate the complexities of interoperability and integration by leveraging insights on standards like KNX, BACnet, and CEN/TR 18081.
Our forecast model is built on a rigorous methodology that accounts for historical performance, current market indicators, and forward-looking variables. The revenue projections from 2026 to 2032 are not merely extrapolated trends but reflect a deep understanding of the drivers, restraints, and opportunities that will shape the industry. For investors, this means a clearer view of valuation metrics and risk factors. For technology vendors, it means validated demand signals for R&D prioritization. For facility owners and operators, it means a roadmap for phased modernization that aligns with budget cycles and compliance mandates.
The market concentration data, showing significant revenue held by leading players, also highlights the importance of differentiation. New entrants and established players alike must find unique value propositions, whether through superior analytics, niche application focus, or unbeatable integration capabilities. Our report includes profiling of key companies, detailing their core offerings, strategic moves, and areas of focus, providing a reference point for competitive analysis and partnership opportunities.
Smart Building Market
Conclusion: Your Gateway to Market Mastery
The smart building market stands at the intersection of technology, sustainability, and urban development. With projections pointing to a near tripling of market size by 2032, the decisions made in 2026 will have lasting implications for portfolio performance, operational resilience, and brand reputation. The PW Consulting Smart Building Market study offers the comprehensive intelligence needed to navigate this complex terrain with confidence.
We invite you to explore the full depth of our research. The complete report contains detailed segmentation data, competitive benchmarking matrices, regional analysis, and strategic recommendations that go beyond the scope of this overview. Don't rely on fragmented insights; equip your organization with the authoritative data and strategic context required to lead in the smart building era. Access the full report to unlock the detailed intelligence that will define your success over the next seven years.
For detailed analysis of this topic, please visit the official page: Smart Building Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


