



PW Consulting: Family Entertainment Market Hits $182.3M in 2025, 5.45% CAGR to 2032

Strategic Intelligence for the Future of Family and Indoor Entertainment: Navigating the 2026 Landscape
The global Family/Indoor Entertainment Centres market stands at a pivotal inflection point as we move through 2026. Against a backdrop of shifting consumer priorities, rising operational costs, and aggressive physical expansion by market leaders, strategic clarity is no longer optional. This newly released market research report delivers a comprehensive, data-driven foundation for decision-makers operating in or adjacent to the family entertainment ecosystem. By synthesizing historical performance, forward-looking projections, competitive intelligence, and operational benchmarks, the study equips executives, investors, and site-selection teams with the analytical rigor required to allocate capital, design experiential offerings, and defend market share in an increasingly crowded arena.
The sector has demonstrated remarkable resilience over the past half-decade. Drawing on verified historical records and carefully modeled trajectories, the market has evolved from a baseline of approximately $145.35 million in 2020 to a projected $182.3 million in 2025. The forward window extends through 2032, with revenue forecasts charting a steady climb toward $262.7 million by the terminal year. This expansion is underpinned by a compound annual growth rate of 5.45 percent across the forecast horizon, a figure that reflects sustained demand for structured, family-oriented leisure experiences even as discretionary spending patterns continue to recalibrate. The trajectory underscores a fundamental truth: experiential entertainment is transitioning from a discretionary luxury to a normalized component of household recreation budgets.
Macro Market Trajectory and Growth Architecture
Understanding the shape of this growth requires more than headline numbers. The report dissects the revenue curve across multiple temporal layers, beginning with the historical reconstruction from 2020 through 2025 and extending into a granular forecast spanning 2026 to 2032. Each year is contextualized within broader economic signals, seasonal visitation patterns, and capital deployment cycles. The analysis reveals that momentum is not evenly distributed; rather, it concentrates around specific operational models, geographic clusters, and experiential formats that consistently outperform peer configurations. By isolating the structural drivers behind the 5.45 percent CAGR, the study enables stakeholders to distinguish between temporary cyclical strength and durable secular expansion.
Revenue projections are anchored to realistic assumptions about foot traffic, per-visit spend, and operational scalability. Internal benchmarks indicate that families typically allocate between $12 and $22 at individual location-based entertainment venues, with an average spend nearing $25 when admission, gaming, food and beverage, retail, and equipment rentals are combined. This per-transaction economics framework is critical because it exposes the leverage points where design, pricing, and ancillary monetization converge. The report maps these dynamics across the forecast period, allowing operators to model sensitivity scenarios around ticket pricing, promotional cadence, and ancillary attach rates without relying on broad industry averages that obscure site-level reality.
Consumer Experience Drivers and Behavioral Segmentation
The heart of the family indoor entertainment proposition lies in how guests experience the venue. The research categorizes consumer engagement through experience intensity, revealing a clear hierarchy in how different guest profiles translate into revenue and loyalty. Full-experience environments, which integrate multi-attraction layouts, sustained dwell time, and comprehensive dining or retail components, command the largest share of market value. Half-experience configurations, which balance active play with selective amenities, represent a substantial secondary tier, while no-experience or entry-level formats capture a smaller but strategically relevant segment of the market.
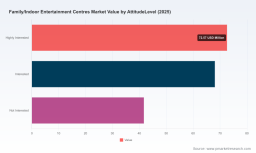
Parallel to experience depth, the report examines attitude-driven demand. Consumer sentiment clusters into highly interested, interested, and not interested cohorts, each requiring distinct site design, marketing messaging, and operational pacing. The highly interested segment drives repeat visitation and word-of-mouth amplification, while the moderately interested group responds strongly to seasonal programming, group bookings, and value-added passes. By aligning venue architecture and promotional calendars with these behavioral strata, operators can avoid the common pitfall of designing for an undifferentiated mass audience and instead engineer experiences that convert interest into recurring revenue.
Regional demand patterns further shape the opportunity set. Market value is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each geography presenting distinct visitation frequency norms, labor cost structures, and competitive density. The analysis does not treat these regions as monolithic blocks; instead, it examines how local consumption habits, real estate economics, and regulatory environments interact with the core entertainment model. For instance, North American households tend to visit family entertainment centers three to five times per year, prioritizing shared experiential leisure over material goods. This frequency baseline becomes a critical input for staffing models, inventory planning, and loyalty program design.
Competitive Landscape and Strategic Positioning
The competitive architecture of the sector is defined by a mix of highly scaled incumbents and regionally focused challengers, all competing on experience density, brand recognition, and operational efficiency. Dave & Buster's, headquartered in Coppell, Texas, has built a formidable presence through large-scale indoor entertainment centers that combine extensive arcade gaming, full-service dining, sports bar environments, and family-oriented attractions across North America. Its recent expansion cadence, including a major new location in King of Prussia, Pennsylvania, opened in May 2026 with over 100 arcade games, integrated dining, and the creation of 150 new jobs, signals a deliberate strategy of market deepening and brand reinforcement in high-traffic suburban corridors.
Urban Air Adventure Parks, based in Bedford, Texas, pursues a distinctly active-play orientation. Its indoor adventure parks center on climbing walls, trampoline networks, inflatable features, and structured active play zones designed to attract families seeking physical engagement rather than passive entertainment. The company's continued footprint growth, including a newly signed lease for an Owings Mills, Maryland facility expected to open in early 2027, reflects confidence in the durability of motion-centric family experiences and the willingness of consumers to pay for structured activity-based leisure.
Chuck E. Cheese, also headquartered in Irving, Texas, maintains its status as an iconic family entertainment brand by fusing arcade gaming, pizza dining, and birthday party venues into a tightly integrated experience model. Its May 2026 product launch introduced ten new arcade games alongside a 2026 Summer Fun Pass offering unlimited visits, a move that underscores the brand's focus on repeat engagement, seasonal campaign alignment, and family-centric programming. Main Event Entertainment, located in Coppell, Texas, competes through multi-activity indoor centers that layer bowling, laser tag, arcade games, and team-building experiences into a single destination. Its expansion pipeline, including a new Huntsville location unveiled in May 2026, a Brownsville center planned for July 2026, and a Greensboro grand opening, illustrates a methodical approach to geographic penetration and multi-attraction differentiation.
Scene75 Entertainment Centers, operating from Dayton, Ohio, rounds out the competitive field with large indoor venues that combine go-karts, laser tag, arcade gaming, bouncing areas, and full dining under one roof. This breadth of offering positions Scene75 as a destination-style player that competes on variety and dwell time. Collectively, these companies illustrate the spectrum of operational philosophies currently shaping the market, from arcade-and-dining dominance to active-play specialization and multi-activity integration.
Market Concentration and Structural Efficiency
A critical dimension of strategic planning is understanding how concentrated the market truly is and what that implies for new entrants, site acquisition, and competitive response. The report quantifies concentration through standard industry metrics, revealing that the top three players account for approximately 26.5 percent of market revenue, while the top five capture roughly 34.2 percent. This moderate concentration indicates a fragmented landscape with room for regional leaders and well-executed niche concepts, but it also signals that scaled operators retain meaningful advantages in purchasing power, brand recognition, and multi-site operational learnings.
The concentration profile has direct implications for capital deployment. Operators evaluating expansion must weigh the benefits of scale-driven cost efficiencies against the risks of market saturation in established corridors. The study provides a framework for assessing whether a given submarket is dominated by a single experiential format or remains open to differentiated concepts. By mapping concentration patterns alongside regional demand intensity, the report helps decision-makers identify corridors where competitive white space still exists and where brand positioning can be established before saturation intensifies.
Family/Indoor Entertainment Centres Market
Operational Economics and Profitability Levers
Operational discipline separates sustainable operators from those that chase foot traffic without securing margin. Industry benchmark data continues to show that employee payroll represents the largest expense category for family entertainment centers, making labor scheduling, cross-training, and peak-hour staffing efficiency central to profitability. The report integrates these cost realities into its strategic analysis, demonstrating how venue layout, attraction mix, and service design directly influence labor intensity per guest hour. Venues that optimize throughput without sacrificing experience quality consistently outperform peers on margin, even when facing similar revenue levels.
Profitability benchmarks further contextualize the operating environment. Approximately one-third of facilities report revenue exceeding $1 million, with an average profit margin of 14.8 percent across the sector. These figures are not aspirational; they are achievable outcomes of disciplined site selection, pricing architecture, and operational orchestration. The research breaks down how ancillary revenue streams, group bookings, birthday party packages, and seasonal promotions contribute to margin expansion, enabling operators to move beyond top-line growth and focus on value capture. By aligning labor models with visitation patterns and designing pricing structures that protect attach rates, operators can convert per-visit spend into durable profitability.
Party Costumes Market
What the Full Research Delivers
This report is engineered for execution, not observation. It provides a structured intelligence package that translates market dynamics into actionable planning inputs across strategy, operations, finance, and expansion functions. The full document includes:
- A complete historical reconstruction and forward forecast with year-by-year revenue trajectories, enabling scenario modeling under multiple demand and cost assumptions.
- Experience-level and attitude-level segmentation analysis that maps guest engagement intensity to revenue contribution, visitation frequency, and operational design requirements.
- Regional demand distribution and competitive density profiling that supports site selection, market entry timing, and format localization decisions.
- Competitive profiling of leading operators, including business model differentiation, recent expansion and product-launch activity, and strategic positioning cues.
- Operational benchmark integration covering labor cost structures, revenue thresholds, profit margin ranges, and per-visit spend dynamics that inform pricing, staffing, and ancillary monetization strategies.
- Market concentration metrics and structural readouts that clarify scale advantages, fragmentation risk, and the conditions under which new concepts can achieve defensible positioning.
- Actionable strategic recommendations for capital allocation, experiential design, promotional cadence, and geographic expansion sequencing through the 2032 horizon.
Each section is designed to feed directly into planning cycles. The historical reconstruction anchors expectations, the forecast window supports budgeting and expansion scheduling, the segmentation analysis guides venue architecture and marketing targeting, and the competitive and concentration readouts inform positioning and risk assessment. Together, these components create a decision-ready intelligence platform rather than a passive market summary.
Why This Research Matters for 2026 Decision-Making
The 2026 operating environment demands more than intuition. Consumer habits continue to favor shared experiential leisure, but families are also more deliberate about where they allocate limited discretionary budgets. Operators that succeed will be those that design for repeat engagement, manage labor intensity intelligently, and position their offerings against clearly defined competitive alternatives rather than against an abstract market average. The report's combination of macro trajectory, segmentation depth, competitive tracking, and operational benchmarking provides the evidentiary base required to make those choices with confidence.
For executives, the study functions as a strategic compass. It clarifies where growth is structurally supported, which experiential formats align with high-intent guest segments, how labor and ancillary revenue interact to shape margin, and where competitive concentration leaves space for differentiated concepts. For investors and corporate development teams, it offers a disciplined framework for evaluating expansion timing, site economics, and brand positioning in a market that rewards operational precision as much as creative concepting.
Conclusion
The Family/Indoor Entertainment Centres market is expanding along a measurable, multi-year trajectory, but the opportunity is not uniformly accessible. Success in 2026 and beyond will belong to organizations that translate market data into operational design, pricing strategy, staffing models, and expansion sequencing. This research report exposes the underlying architecture of that opportunity, from historical performance and forward forecasts to experience segmentation, competitive behavior, and concentration dynamics. It is built to support real decisions: where to invest, how to design, whom to target, and how to sustain margin in a competitive, labor-sensitive environment.
The complete analysis, including the full dataset, segmentation breakdowns, regional profiles, competitive tracking, and strategic recommendations, is available through the full report download. Stakeholders seeking to align their 2026 planning with a rigorous, forward-looking market view are encouraged to access the complete intelligence package and integrate its findings into capital allocation, site strategy, and experiential design decisions.
For detailed analysis of this topic, please visit the official page: Family/Indoor Entertainment Centres Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


