



PW Consulting: Industrial Butt Fusion Machines Market to Hit $0.29B by 2032, 4.32% CAGR

Industrial Butt Fusion Machines Market: Strategic Intelligence for 2026 Decision-Making
Navigating a Consolidated Landscape Defined by Precision, Digital Integration, and Material Dynamics
As industrial infrastructure demands continue to prioritize leak-free, high-integrity piping systems, the Industrial Butt Fusion Machines Market remains a critical enabler across utility, energy, and chemical sectors. Our latest market research delivers a comprehensive, forward-looking assessment of this specialized equipment arena, calibrated to guide corporate strategy through 2026 and beyond. The study is structured not merely as a historical retrospective but as a decision architecture that aligns procurement planning, product development, competitive positioning, and geographic expansion with verifiable market mechanics. By synthesizing multi-year historical tracking with a disciplined forecast window through 2032, the report equips executives with the contextual clarity needed to allocate capital, differentiate offerings, and respond to evolving technical standards.
The market’s trajectory reflects a broader industrial shift toward automation, traceable weld documentation, and diameter-flexible machine architectures. Over the historical review period spanning 2020 through 2025, the sector navigated an environment characterized by fluctuating raw material pricing, varying municipal procurement cycles, and the gradual adoption of digitally enabled fusion equipment. This period laid the foundation for a measured, yet structurally positive, growth path. The research captures these dynamics and translates them into actionable frameworks, allowing stakeholders to distinguish between cyclical pricing noise and durable demand shifts.
Macro Trajectory and Forecast Architecture: What 2026 Executes for Long-Range Planning
A core value of this research lies in its disciplined forecast architecture. The study establishes a forecast horizon from 2026 through 2032, anchored against a recent reference year and supported by a consistent historical dataset. Across the projection window, the market is positioned for a compound annual growth rate of 4.32%, signaling a steady and calculable expansion rather than a speculative surge. This level of growth implies that operators, investors, and suppliers must plan with precision: incremental volume gains will depend on successful deployment of advanced machine classes, alignment with regional infrastructure programs, and the ability to navigate raw material cost variability.
The revenue trajectory across the forecast horizon points toward gradual but compounding market scaling, with total industry revenue progressing into a higher range by the close of the decade. For leadership teams, the strategic implication is that timing matters as much as scale. Early positioning in semi-automated and fully automated platforms, along with service and data-recording ecosystems, becomes a differentiator when growth is distributed across a broad equipment continuum rather than concentrated in a single product breakthrough. The report maps this progression in a manner that supports scenario planning, allowing executives to test sensitivity around pricing, adoption pace, and application-led demand without relying on superficial indicators.
Electrofusion Fittings Market
Segmentation Architecture: Understanding Where Value and Volume Converge
A defining feature of the Industrial Butt Fusion Machines Market is its segmentation across multiple operational dimensions. Rather than presenting isolated percentages, the report contextualizes each segment through its functional relevance to buyers and manufacturers. By machine type, the market distinguishes among automatic, semi-automatic, and manual butt fusion equipment. This classification is not simply descriptive; it signals how various end users balance throughput requirements, labor availability, and site conditions. Automatic platforms tend to anchor high-volume industrial deployments where repeatability and weld-record traceability are paramount. Semi-automatic variants address mid-range projects with a need for flexibility and operator oversight, while manual configurations remain relevant for specialized or constrained installations where portability and lower upfront cost dominate purchasing logic.
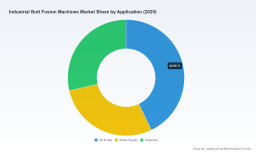
By application, the research examines how core end-use environments shape equipment requirements and purchasing cycles. Oil and gas operations continue to demand robust fusion solutions for pressure-critical piping, often favoring machines capable of handling larger diameters and ensuring rigorous documentation. Water supply networks depend on reliable fusion for municipal and regional distribution infrastructure, where consistency across long pipeline runs and field serviceability are decisive. Chemical applications place emphasis on material compatibility and welded joint integrity across corrosive or high-purity service conditions. The report details how these application streams influence machine specification, maintenance expectations, and aftermarket service demand, giving suppliers a clearer picture of where operational value is created over the equipment lifecycle.
On the regional front, the study evaluates how geographic demand clusters and infrastructure priorities create distinct market environments. Instead of reducing each territory to a single numeric share, the report analyzes regional demand drivers, competitive intensity, import and distribution patterns, and the role of localized service support. This approach allows readers to understand where equipment demand is likely to be volume-led, where technical customization dominates, and where export-oriented manufacturing strategies may create pricing pressure. In practice, this means stakeholders can better align product portfolios, distribution partnerships, and service footprints with the realities of each region’s procurement culture and infrastructure agenda.
Industrial Butt Fusion Machines Market
Competitive Dynamics: A Focused Field of Specialized Manufacturers
The competitive environment is characterized by a modest level of concentration, reflecting a market where specialized engineering capability, measurement precision, and application-specific reliability remain decisive advantages. The research examines the landscape through the lens of established manufacturers that have built reputations on machine performance, weld documentation, and breadth of pipe material compatibility. These firms span North America, Europe, Asia, and other regions, each competing through differentiated machine architectures, digital integration, and service ecosystems.
Key competitors evaluated in the study include firms such as McElroy Manufacturing, Inc., recognized for premium automatic and semi-automatic butt fusion machines designed for HDPE and PE piping, with digital weld recording capabilities and track-mounted platforms suited for demanding field conditions. Georg Fischer Piping Systems Ltd. is assessed for its automated and portable fusion equipment supporting pressure piping systems across water, gas, and industrial contexts. Ritmo S.p.A. is examined for its emphasis on high-productivity track-mounted and workshop-based machines covering HDPE, PP, and other thermoplastics. Fusion Group Limited contributes to the analysis as a supplier of precision butt fusion equipment for PE pipe and fittings in industrial and municipal projects. Rothenberger USA LLC and Hurner Welding Technology GmbH are reviewed for their manual, semi-automatic, and automatic machine offerings and workshop or on-site solutions for thermoplastics up to large diameters. WIDOS Wilhelm Dommer Söhne GmbH and KraussMaffei Technologies GmbH round out the evaluation as manufacturers of plastic welding machinery and butt fusion systems oriented toward pressure pipe applications. Additional players, including Wuxi Baoda Plastic Pipe Welding Equipment Co., Ltd., SWT Plastic Welding, Leister Technologies AG, Plasson Ltd., Worldpoly Pty Ltd, and Nupi Americas, Inc., are assessed for their contributions to multi-angle, portable, and industrial-grade fusion equipment portfolios. This competitive mapping is designed to provide relative positioning insight, not just product lists, enabling strategic benchmarking around automation levels, diameter coverage, documentation technology, and regional service reach.
Recent Developments and Operational Signals Shaping 2026 Strategy
Market momentum is not driven by forecasts alone; it is continuously reshaped by product launches, trade-channel activity, material cost behavior, and equipment pricing signals. The report integrates recent operational developments to give decision-makers a current picture of how the competitive field is moving. In mid-to-late 2025, new product catalog releases and showcase activity brought renewed attention to hydraulic butt fusion machines for water, gas, mining, and petrochemical applications. Trade show participation and technical demonstrations further illustrate how manufacturers are communicating advanced thermoplastic welding solutions and buyer guidance, reinforcing the importance of visibility and specification support in procurement cycles.
On the materials side, polyethylene pricing behavior remains a relevant variable for machine utilization, project budgeting, and pipe procurement. Recent price movements have reflected shifts in regional supply dynamics and import competition, with European HDPE markets experiencing steady softening in late 2025 due to competitive imports from Asia and the Middle East. These material fluctuations do not change the fundamental demand for fusion equipment, but they do influence project economics and the pace at which operators invest in higher-capacity or higher-automation machines. The report contextualizes such input-cost behavior so that market participants can separate short-term commodity movements from durable equipment demand.
At the equipment level, recent industry signals underscore how pricing ranges and product innovation interact. For example, automatic butt fusion machines in the 315 mm to 630 mm size range were observed at average selling price levels ranging broadly in 2025, reflecting the premium associated with larger-diameter, higher-throughput platforms. This matters because price dispersion across machine classes shapes buyer expectations, financing decisions, and competitive differentiation. Simultaneously, the introduction of independently powered track-mounted machines for large-diameter oil and gas applications demonstrates how manufacturers are expanding machine capability to serve more technically demanding installation environments. The report connects these developments to purchasing logic, showing how feature sets and power architecture affect total cost of ownership and site deployment efficiency.
Report Structure and Practical Content for Executive Use
Beyond high-level market orientation, this research is designed as an operational reference. The report introduces a structured view of segmentation logic, historical performance patterns, and forecast assumptions, allowing readers to interrogate demand drivers rather than simply accept summary figures. It includes detailed discussion of how machine type, application, and regional context interact in real purchasing environments, enabling more precise go-to-market planning and product positioning. The analysis also addresses competitive behavior, including how dominant firms maintain relevance through automation, documentation tools, and service coverage, and where smaller or regionally focused manufacturers can compete on specialization, lead time, or application-specific configuration.
In addition, the study incorporates market concentration indicators to provide a realistic view of competitive structure. With a moderately concentrated field, the research explains the strategic significance of scale, technical reputation, and the ability to support large-diameter or digitally integrated platforms. This is especially useful for companies evaluating partnership opportunities, acquisition targets, import pathways, or regional expansion, because it clarifies where market influence is distributed and where entry barriers remain tied to technical credibility and service reliability. The report’s practical orientation extends to purchase considerations, operational deployment factors, and the ways in which weld-record data and machine control architectures are becoming part of the broader value proposition in industrial piping projects.
Why This Research Matters for 2026 Decisions
The strategic value of this report comes from its ability to convert complex market mechanics into decision-ready intelligence. For manufacturers, it supports product roadmap choices by clarifying where automation, portability, and documentation features are most valued. For distributors and service providers, it highlights where regional demand patterns and machine-class preferences create opportunities for targeted inventory, training, and field support. For investors and corporate planners, it offers a forecast-consistent view of how the market is likely to expand and where competitive advantage will be earned through differentiation rather than volume alone.
By maintaining a disciplined balance between macro trajectory and operational detail, the study helps stakeholders avoid overreliance on fragmented indicators and instead base decisions on a connected understanding of type, application, region, and competitive behavior. It also prepares readers to interpret raw material movements, equipment pricing dispersion, and product launch activity as part of a larger market system rather than isolated events.
Accessing the Full Strategic Intelligence
This introduction outlines the scope and analytical direction of the research, but the complete dataset, scenario framing, and detailed segmentation discussion reside in the full report. To obtain the comprehensive market intelligence needed for precise 2026 planning across equipment strategy, regional deployment, competitive benchmarking, and demand forecasting, readers are encouraged to access the complete report directly through the source page. The full version delivers the depth required to convert market awareness into executable corporate strategy.
For detailed analysis of this topic, please visit the official page: Industrial Butt Fusion Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


