



PW Consulting: Motherboard Market Hits $135M in 2025, Forecast CAGR 7.45% to $226M by 2032

Strategic Intelligence for the Board-Level Infrastructure Decision-Maker
The motherboard has long been treated as a commoditized substrate, a passive backbone whose procurement is delegated to procurement teams and IT asset managers. That posture no longer fits the operational reality of 2026. As system architectures migrate toward heterogeneous compute, edge-to-cloud orchestration, and platform-level power optimization, the motherboard has re-emerged as a strategic control point. PW Consulting’s newly released Motherboard Market research is designed for leaders who must navigate this inflection point with precision rather than intuition.
This report does not simply track headline volumes. It maps the structural forces reshaping how boards are specified, sourced, bundled, and deployed across enterprise, industrial, and high-performance computing environments. By anchoring historical performance to a disciplined forward model, the study gives decision-makers a defensible basis for capex planning, supplier selection, capacity negotiation, and portfolio positioning. The objective is straightforward: shorten the distance between market signal and boardroom action.
Embedded Computer Market
The Trajectory: From Recovery to Platform Differentiation
Over the 2020 to 2025 historical window, the global motherboard market moved through a decisive expansion phase. Revenue grew from a baseline of USD 80.0 million in 2020 to USD 135.0 million in 2025, reflecting the compounded effect of platform refreshes, enterprise hardware reinvestment, and the broadening footprint of specialized computing workloads. That upward arc did not flatten into complacency. Instead, it set the stage for a forecast period from 2026 through 2032 in which the market is projected to reach USD 226.0 million by 2032, supported by a compound annual growth rate of 7.45 percent.
These figures are best read as directional trust signals rather than isolated line items. They indicate that demand is not merely rebounding; it is reorganizing around new performance, reliability, and integration requirements. For procurement leaders, that means historical unit-cost assumptions must be re-validated against evolving BOM complexity, substrate availability, and firmware-level feature sets. For product planners, it signals that board-level design choices increasingly cascade into system-level competitive advantage.
What the Report Delivers: Operable Intelligence, Not Just Estimates
PW Consulting built this study as a working instrument for cross-functional teams. The narrative is anchored in market sizing, but the real value lies in how the analysis connects structure to behavior. Readers can expect coverage that supports concrete planning decisions across several dimensions.
- Historical reconstruction and forward modeling that tie baseline years to forecast trajectories, giving finance and operations a consistent basis for scenario planning.
- Form factor analysis that examines how physical and electrical board architectures shape supplier positioning, integration pathways, and end-market requirements.
- Application-level decomposition that distinguishes how different usage environments influence board specification, thermal and power design priorities, and procurement cycles.
- Competitive profiling of leading participants, including their product architecture choices, deployment focus, and strategic posture across consumer, enterprise, and infrastructure segments.
- Recent development tracking that captures product launches, manufacturing moves, and supply-side actions relevant to sourcing strategy and lead-time planning.
- Market dynamics context that integrates pricing signals, component allocation pressures, trade environment shifts, and regional capacity considerations into a unified operating view.
The report is structured so that strategy, procurement, and engineering teams can draw from the same evidence base without having to reconcile conflicting market narratives. It also deliberately preserves room for deeper dives on our source portal, where full segmentation intelligence, methodology notes, and scenario tools are available for teams that need to stress-test assumptions at the category level.
Competitive Intensity and the Concentrated Core
The motherboard field is not a diffuse commodity battleground. Market concentration remains pronounced, with the top three participants holding an estimated 68.0 percent share and the top five accounting for approximately 75.0 percent. That concentration has strategic consequences. It means pricing dynamics, platform roadmaps, and supply commitments are shaped by a relatively small set of capable manufacturers whose decisions cascade through downstream assembly, channel distribution, and enterprise procurement.
Several firms anchor the competitive landscape in distinct ways. ASUTeK Computer Inc. draws on its long-standing design and manufacturing footprint in consumer and high-end motherboard series, including lines oriented toward enthusiast and creator platforms. MSI continues to compete across gaming, creator, and workstation environments through brand-tiered product families that emphasize performance segmentation and platform tuning. Gigabyte Technology Co., Ltd. maintains a broad consumer and creator presence while leaning into durability positioning and specialized performance tiers across its portfolio.
The commercial center of gravity shifts markedly when the frame moves from client PC ecosystems to server-grade and data-center infrastructure. Super Micro Computer, Inc. occupies that higher-density environment with server and data-center boards, power systems, and chassis configurations optimized for AI and cloud computing workloads. In parallel, Biostar Microtech International Corp. extends motherboard relevance into industrial PC and embedded contexts, where reliability, lifecycle support, and application specificity matter more than consumer-facing feature cadence.
The competitive set also includes board and platform suppliers that influence downstream system design rather than competing solely as standalone motherboard brands. ASRock Inc. supplies performance-oriented boards for gaming and workstation use, while Acer Incorporated, HP Inc., and Dell Technologies Inc. integrate motherboards into broader client, enterprise, and server product strategies. That mix matters because motherboard purchasing decisions are increasingly made within platform ecosystems rather than in isolation, and the supplier relationships that shape integration, firmware support, and lifecycle management often determine the real cost of ownership.
Recent Moves That Redefine Sourcing and Roadmap Assumptions
Market intelligence is only as useful as its timeliness. Recent company-level actions illustrate how quickly the strategic landscape is shifting, and the report integrates these developments into its operating context.
- Gigabyte Technology began local motherboard production in India under the Make in India initiative, a move aimed at improving supply efficiency and regional responsiveness.
- The same company introduced a new motherboard series emphasizing AI integration and enhanced performance features, signaling how board-level product roadmaps are increasingly tied to platform-level intelligence capabilities.
- ASUSTeK unveiled prototype boards at Computex 2025 supporting newer processor platforms with layout innovations that reduce cable clutter and change system integration assumptions.
- Super Micro Computer introduced energy-efficient server motherboards supporting advanced I/O and memory standards for cloud and edge computing, reinforcing the link between board design and data-center power economics.
These are not isolated product announcements. They are indicators of where capital, engineering effort, and regional supply strategy are moving. When major players simultaneously adjust manufacturing geography, packaging architecture, and performance positioning, procurement teams must look beyond unit price and assess total landed risk, regional continuity, and roadmap alignment.
Market Dynamics: Pricing Pressure, Supply Reallocation, and Trade Realities
The forward outlook cannot be separated from the environment in which boards are manufactured and sold. Several overlapping forces are reshaping near-term operating conditions. One persistent theme is component pricing pressure. Motherboard sales have faced contraction pressure as memory and other PC component prices rise, driven in part by AI demand reshaping allocation priorities across the broader hardware supply chain. At the same time, AI-driven prioritization of silicon production has contributed to supply shortages and price increases for components used in consumer motherboards, complicating cost forecasting and inventory planning.
Motherboard Market
Trade policy adds another layer of complexity. A 25 percent tariff on a narrow range of advanced semiconductor imports took effect in early 2026, altering cost calculations for certain advanced components and supply routes. At the same time, export control discussions have not uniformly intensified in every bilateral forum, illustrating that the regulatory landscape is uneven rather than monolithic. For planning teams, this mix of constraint and selective continuity demands scenario-based thinking rather than a single compliance assumption.
Geopolitical capacity dynamics also matter. China’s continued growth in semiconductor capacity is heightening supply chain risk for downstream products like motherboards, especially where regional concentration intersects with shifting demand patterns and component allocation. These are not abstract concerns. They affect lead times, alternate sourcing feasibility, and the durability of supplier commitments. The report treats these dynamics as decision inputs, situating pricing, regulation, and geopolitical exposure within a single operational framework instead of leaving them in separate silos.
How to Use This Intelligence in 2026 Planning
The strategic value of this research lies in its applicability to real decisions. For procurement and supply chain leaders, the study supports supplier evaluation beyond headline cost by connecting market structure, concentration behavior, and recent supply-side actions to sourcing resilience. For product and platform strategists, it provides a basis for anticipating how form factors, application requirements, and platform-level intelligence features will influence buyer expectations and system integration choices. For investors and corporate development teams, it offers a structured lens on where competitive advantage is accumulating and where commoditization risk remains highest.
The report is especially useful for organizations that need to reconcile near-term procurement realities with longer-term architecture planning. If memory and component pricing are pressuring unit economics, how should volume commitments be structured? If regional manufacturing moves are improving supply efficiency for certain players, how should dual-sourcing and geography exposure be reassessed? If board design is increasingly tied to AI workload integration and energy-efficient server platforms, where should engineering and sourcing priorities converge? These questions are answerable only when market data is paired with competitive behavior and operating context, which is precisely the integration this study is built to provide.
Why the Full Intelligence Matters
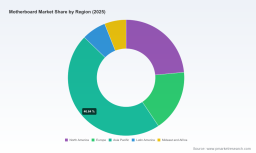
The macro trajectory is clear enough to set direction: the market expands from USD 140.86 million in 2026 toward USD 226.0 million by 2032, supported by a 7.45 percent CAGR, within a historically concentrated competitive structure. Yet direction is not the same as decision-ready precision. Effective planning requires insight into how demand splits across regions, how form factors and applications shape segment economics, and how competitive moves alter procurement leverage in specific buying contexts. Those details determine whether a strategy is merely plausible or genuinely executable.
PW Consulting has deliberately reserved the full segmentation breakdown, scenario modeling detail, and company-level competitive analysis for the complete report environment. That is not a marketing constraint; it is a design choice. Market intelligence is most valuable when it is complete enough to support commitment, not just conversation. The overview presented here is intended to establish analytical credibility and demonstrate the scope of the framework, while the full dataset, methodology, and applied tools remain available through the source page for teams that need to translate insight into procurement strategy, product roadmaps, and investment logic.
For decision-makers operating in a market where component economics, trade exposure, regional manufacturing strategy, and platform-level intelligence are all moving at once, partial information is a liability. The Motherboard Market research is designed to reduce that liability by giving leaders a coherent, evidence-based view of where the market has been, what is changing now, and how to position for the 2026 to 2032 horizon with greater confidence.
For detailed analysis of this topic, please visit the official page: Motherboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


