



PW Consulting: Automotive eCall Market Hits $1B in 2025, Projected to Triple by 2032 at 12.5% CAGR

Navigating the Next Wave of Automotive eCall: Strategic Insights for 2026 Decision-Makers
The automotive emergency call landscape is undergoing a structural transformation that demands immediate attention from OEMs, tier suppliers, and regulatory strategists. As vehicle connectivity evolves from legacy networks to packet-switched 4G and 5G architectures, the eCall ecosystem is no longer a compliance checkbox but a core component of occupant safety, aftermarket integration, and cross-border emergency response. Our latest market research on the Automotive eCall Market provides a rigorous, data-backed framework for navigating this transition through 2032. Built on historical tracking from 2020 through a forward-looking forecast window of 2026 to 2032, the study translates macroeconomic momentum, regulatory sequencing, and supplier innovation into actionable intelligence for enterprise planning.
The industry has already crossed a decisive inflection point. From an estimated 560 million USD in 2020, the global market expanded to 1,000 million USD by 2025, reflecting sustained investment in in-vehicle emergency systems, regulatory alignment, and network modernization. The trajectory accelerates from here, with the market projected to reach approximately 1,121.56 million USD in 2026 and continue its climb toward roughly 2,274.04 million USD by 2032. This growth path is underpinned by a compound annual growth rate of 12.5 percent across the forecast horizon, signaling durable demand rather than a temporary regulatory bump. For leadership teams mapping capital allocation, product roadmaps, and compliance portfolios, these figures establish the baseline scale of opportunity and the cost of inaction.
Regulatory Sequencing and the Legacy Network Risk
The dynamics shaping eCall adoption cannot be separated from the regulatory calendar. European Commission frameworks have introduced a phased approach to next-generation emergency calling, creating both certainty and transitional friction. Commission Delegated Regulation (EU) 2024/1180 mandates that new M1 and N1 vehicle types be equipped with 112-based eCall in-vehicle systems capable of operating over packet-switched networks such as 4G and 5G beginning 1 January 2026. This requirement reorients system design away from circuit-switched legacy dependencies and pushes the industry toward faster, data-rich emergency workflows.
Automotive eCall Market
At the same time, the regulatory timeline has been calibrated to give manufacturers breathing room. Commission Delegated Regulation (EU) 2025/1871 defers the mandatory application of the new eCall standards EN 17184:2024 and EN 17240:2024 to 1 January 2027. This adjustment reflects a pragmatic recognition of engineering lead times, supply chain readiness, and the need for validation cycles before full-scale compliance. For enterprises, the layered timeline creates a strategic window: early movers can align product architectures to next-generation specifications while de-risking certification, and late movers face a compressed retrofit environment as legacy systems age into obsolescence.
The legacy network dimension adds urgency. As several EU member states advance shutdowns of 2G and 3G infrastructure, approximately 64 million vehicles face potential loss of emergency call functionality without coordinated mitigation. This exposure does not merely affect aftermarket service providers; it impacts fleet operators, leasing companies, insurance models, and OEM brand reputation. Mitigation strategies increasingly require hybrid communication designs, network-agnostic fallback logic, and lifecycle planning that extends beyond the vehicle's initial homologation date. Our study analyzes how these regulatory and network transitions intersect, helping stakeholders prioritize where to invest, when to phase out legacy dependencies, and how to structure compliance roadmaps without disrupting production schedules.
Market Structure, Concentration, and Growth Drivers
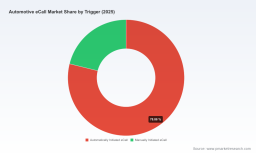
The eCall market is not a monolithic pool of demand. It is shaped by vehicle-type mix, trigger mechanisms, regional deployment intensity, and the concentration of competitive capability. The total addressable opportunity reflects a market where passenger vehicles and commercial fleets generate distinct adoption curves, and where automatically initiated emergency calls account for the dominant share of system activity relative to manually initiated calls. These structural patterns influence how suppliers design hardware and software, how testing organizations validate interoperability, and how OEMs plan service architecture across regions.
Concentration dynamics further sharpen the competitive picture. The market remains moderately consolidated, with the top three players accounting for 42.5 percent of share and the top five reaching 58.2 percent. This distribution indicates a landscape where a limited number of technologically advanced firms hold visible influence over standards readiness, test infrastructure, and hybrid system integration, while still leaving meaningful room for regional specialists and component suppliers to compete on cost, customization, and service coverage. Understanding this concentration profile is essential for procurement teams evaluating supplier resilience, for investors assessing competitive moats, and for executives considering partnerships or acquisitions in the emergency connectivity space.
Growth momentum is reinforced by several operational realities. Vehicle connectivity is becoming a baseline expectation rather than a premium feature, emergency response institutions are increasingly integrated with digital PSAP workflows, and manufacturers are compressing development cycles to meet evolving standards. The result is a market where volume expansion is tied to engineering reliability, certification velocity, and the ability to deliver consistent performance across heterogeneous network environments. These are precisely the conditions where comprehensive market intelligence delivers leverage: revealing where demand is genuinely durable, where margin pressure is likely to intensify, and where technical differentiation will determine share gains.
Competitive Landscape and the Test-and-Certification Frontier
The companies leading the eCall space are not only shipping products; they are actively shaping the validation environment that determines how quickly the industry can transition to next-generation standards. Three organizations illustrate the breadth of strategic activity now unfolding.
Keysight Technologies, Inc.
Headquartered in Santa Rosa, California, Keysight has moved decisively into the certification layer for hybrid eCall systems aligned to the EN 18052:2025 standard. The company develops and certifies test solutions that enable dynamic switching between legacy and next-generation eCall networks, a capability that directly supports interoperability across mixed connectivity environments. In June 2026, Keysight achieved DEKRA validation for Hybrid eCall certification to the EN 18052:2025 standard, reinforcing regulatory readiness and cross-system compatibility for in-vehicle emergency platforms. For OEMs and tier suppliers, such certification milestones shorten the path to compliance while reducing uncertainty around hybrid operation during the network transition period.
Rohde & Schwarz GmbH & Co. KG
Based in Munich, Rohde & Schwarz has built a strong position in verification and test infrastructure for next-generation eCall functionality. The company verified NG eCall implementation on the Qualcomm Snapdragon Auto 5G Modem-RF in line with EN 17240:2024, including PSAP simulation, as documented in a July 2025 press release. This work demonstrates end-to-end validation across modem, RF, and emergency call workflows, and it underscores the growing importance of integrating communications silicon with emergency service architecture. Rohde & Schwarz also offers test solutions spanning hybrid and next-generation eCall compliance, positioning the firm as a key enabler for manufacturers seeking to confirm performance before homologation.
LG Electronics Inc.
From Seoul, LG Electronics has expanded its role as an integrated supplier of hybrid emergency call solutions. Starting in 2025, LG began supplying hybrid emergency call systems designed for reliable communication across 2G, 3G, 4G, and 5G networks, embedding emergency call capability directly into vehicle platforms. This approach reflects a practical response to the legacy-to-next-generation transition: rather than treating network evolution as a separate engineering problem, LG's integration model aims to preserve emergency functionality while future-proofing the communication path. As manufacturers seek unified supply partners, such integration breadth becomes a differentiator in cost planning, validation complexity, and service continuity.
Taken together, these developments highlight a competitive arena where value is increasingly created at the intersection of hardware integration, modem and RF verification, and certification alignment. The firms that can deliver standards-compliant, network-resilient solutions with repeatable test coverage will influence not just individual vehicle programs, but the broader pace of industry migration toward packet-switched emergency calling.
What the Report Covers: Practical Intelligence for Execution
This research study is structured for decision-makers who need more than high-level forecasts. It connects market sizing with the operational realities of system design, validation, regulatory adoption, and supplier selection. The report is intended to support executive planning, product strategy, compliance roadmapping, and competitive positioning across the 2026 to 2032 horizon.
Readers will find an integrated view of the market that ties historical performance to forward projections, interprets growth through structural drivers rather than headline numbers alone, and maps competitive activity to the standards and testing infrastructure now shaping the industry. The study goes beyond generic trend statements to examine how automatically initiated and manually initiated eCall models distribute across the market, how passenger car and commercial vehicle segments differ in adoption intensity, and how regional deployment patterns influence supplier strategy and compliance prioritization. It also contextualizes market concentration, identifying where scale advantages matter, where specialized capabilities create entry points, and where partnership strategies can accelerate time to market.
Equally important, the report translates regulatory developments into execution-relevant implications. It examines how the EU's phased standards timeline interacts with network shutdown risks, what hybrid system architectures can mitigate legacy exposure, and how certification milestones such as DEKRA validation and EN 17240 verification affect product readiness. The analysis is designed to help teams answer practical questions: which technical capabilities are becoming table stakes, which validation activities should be prioritized now versus deferred, and how to structure supply and engineering plans so that compliance is achieved without sacrificing program velocity.
To ensure relevance for operational teams, the report links market intelligence to supplier evaluation, procurement strategy, and risk management. It examines how leading test and integration providers are positioning for next-generation compliance, what that means for component sourcing and system integration, and where enterprises should focus diligence when assessing partners for eCall hardware, software, and validation services. By anchoring these discussions in a 2025 base year and a detailed 2026 to 2032 forecast, the study provides a coherent framework for scenario planning, investment justification, and executive alignment.
Automotive Escape Tools Market
Why This Research Matters for 2026 Decisions
The 2026 planning cycle is not an ordinary annual reset. It arrives at the convergence of regulatory mandates, network modernization, and supplier capability maturation. For OEMs, the question is no longer whether eCall systems need to evolve, but how quickly hybrid and next-generation architectures can be deployed without disrupting homologation, cost targets, or service continuity. For tier suppliers and technology providers, the opportunity lies in delivering validated, standards-aligned solutions that reduce integration risk and accelerate certification. For commercial fleet operators and service organizations, the challenge is managing legacy exposure across large vehicle populations while preparing for packet-switched emergency workflows.
In this environment, strategic advantage comes from clarity. Decision-makers need a reliable view of the market's overall scale and growth trajectory, a grounded understanding of how regulatory timing reshapes development priorities, and a realistic picture of where competitive capability is concentrating. The forecast growth from approximately 1,121.56 million USD in 2026 to roughly 2,274.04 million USD by 2032, at a compound annual growth rate of 12.5 percent, sets the scale of the opportunity. The regulatory calendar, Legacy network risks, and certification milestones define the sequence of execution. The concentration profile and supplier activity shape the competitive response.
Our Automotive eCall Market research brings these elements together in a single, structured intelligence asset. It is designed to support strategic planning across engineering, compliance, procurement, and commercial functions, and it provides the context needed to evaluate investments, partnerships, and product roadmaps with confidence. For organizations preparing to act in 2026 and beyond, the study offers the analytical foundation to move from reactive compliance to proactive market positioning.
To access the full segmentation analysis, regional deployment context, complete forecast tables, and detailed company profiles, please visit the source page for the complete report. The comprehensive dataset and operational breakdowns are available there, enabling deeper diligence and more precise planning across your eCall strategy.
For detailed analysis of this topic, please visit the official page: Automotive eCall Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


