



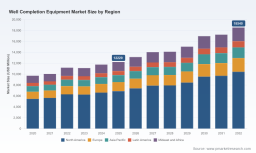
PW Consulting: Well Completion Equipment Market to Reach $18.5B by 2032, Growing at 5.13% CAGR

Navigating the Next Wave: Strategic Insights into the Well Completion Equipment Market Through 2032
The global energy landscape is entering a phase of calculated expansion, where efficiency, compliance, and technological resilience dictate competitive advantage. For operators, service providers, and investors, the well completion equipment market represents more than a transactional supply chain. It is a critical inflection point where geological complexity, regulatory evolution, and engineering innovation converge. As we move deeper into the 2026 decision cycle, understanding the structural drivers, competitive tensions, and material constraints shaping this sector is no longer optional. It is foundational to capital allocation, portfolio optimization, and long-term operational readiness.
Our latest market research on well completion equipment delivers a comprehensive, forward-looking assessment designed specifically for strategic planners and senior leadership teams. Spanning historical performance from 2020 through 2025 and projecting market trajectories through 2032, this study maps the revenue architecture, equipment specialization, application distribution, and regional footprint of a market that has consistently demonstrated resilience amid volatility. The analysis is structured to cut through noise, isolate actionable intelligence, and provide decision-makers with the clarity required to navigate an increasingly fragmented and regulation-intensive operating environment.
Market Architecture: Scale, Trajectory, and Structural Shifts
The well completion equipment market has evolved from a cyclical procurement category into a strategically calibrated segment of the broader oilfield services ecosystem. Over the past half-decade, revenue progression has reflected a combination of disciplined operator spending, accelerated unconventional development, and the gradual integration of intelligent completion technologies. The market closed the historical baseline year at approximately 12.22 billion USD, building on a compound annual growth trajectory that signals sustained demand across multiple development phases. Looking ahead to the 2026-2032 forecast window, the sector is projected to expand at a measured yet consistent compound annual growth rate of 5.13 percent, ultimately reaching an estimated 18.54 billion USD by the end of the forecast period.
This growth profile is not uniform. It is shaped by shifting capital priorities, the maturation of certain shale plays, and the steady push toward higher-pressure, higher-temperature well architectures in both established and emerging basins. The revenue curve reflects periods of consolidation, selective capacity expansion, and the gradual reallocation of expenditure toward completion systems that deliver longer operational lifecycles, improved zonal isolation, and greater conformance with evolving emissions standards. For corporate strategists, these patterns underscore a central reality: the market is rewarding suppliers and operators who can align equipment selection with long-term well performance rather than short-term cost minimization.
The study contextualizes these macro trends within a highly concentrated competitive environment. Market leadership is distributed across a handful of dominant players, with the top three firms collectively accounting for nearly half of total industry revenue and the top five firms capturing approximately two-thirds of the market. This concentration reflects the technical barriers to entry, the capital intensity of advanced manufacturing, and the entrenched relationships between equipment manufacturers and major operating companies. Yet concentration does not equate to homogeneity. The report dissects how differentiated product portfolios, regional service capabilities, and technology roadmaps are reshaping competitive positioning across equipment categories and application domains.
Equipment Specialization and Application Dynamics
Well completion equipment is not a monolithic category. It is a portfolio of specialized tools, each tied to distinct operational objectives, reservoir conditions, and completion philosophies. The research provides a granular breakdown of the principal equipment segments that define market structure, examining how demand patterns differ across packers, sand control tools, multi-stage fracturing equipment, liner hangers, and valve systems. Rather than presenting static share figures, the analysis focuses on the functional drivers that determine segment growth, including reservoir complexity, well architecture design, and the increasing reliance on staged completion methodologies in horizontal and extended-reach wells.
Packers continue to anchor the equipment landscape, serving as the foundation for zonal isolation, pressure management, and intervention readiness. Their performance characteristics directly influence well integrity, production optimization, and long-term asset reliability. Sand control tools remain critical in formations where particulate production threatens operational continuity, driving sustained demand for advanced filtering, gravel packing, and hybrid completion approaches. Multi-stage fracturing tools have gained structural importance as operators pursue higher recovery factors through precise stimulation sequencing, while liner hangers and valve systems support the mechanical and flow-control architecture that underpins safe, efficient well completion.
Application-side analysis further clarifies how completion strategies diverge across operating environments. Onshore development continues to represent the dominant demand center, reflecting the scale of unconventional resource development, the prevalence of horizontal drilling programs, and the ongoing optimization of mature fields. Offshore operations, while representing a smaller share of total activity, carry disproportionate strategic weight due to higher technical complexity, stricter safety and environmental standards, and the growing deployment of subsea completion architectures. The report examines how these application profiles shape procurement cycles, service expectations, and technology adoption curves, providing operators and suppliers with a clearer view of where demand is most durable and where performance differentiation matters most.
Competitive Landscape and Strategic Positioning
The competitive dynamics of the well completion equipment market are defined by a blend of global scale, technical specialization, and targeted regional expansion. Leading participants operate across a spectrum of service models, from integrated completion offerings to focused manufacturing of high-performance tools. The study profiles the core companies shaping market direction, analyzing their strategic footprint, product capabilities, and recent operational developments that signal shifting priorities.
Major integrated service organizations maintain a central role through broad equipment portfolios, proprietary completion technologies, and extensive field support networks. Their strategies increasingly emphasize intelligent completion systems, flow control solutions, and subsurface safety architectures that align with operator demands for real-time monitoring, improved well control, and extended intervention intervals. Alongside these broader service providers, specialized manufacturers and completion-focused firms contribute critical technological niches. Their product lines often target specific operational challenges, including high-pressure and high-temperature environments, multistage horizontal completions, expandable isolation technologies, and advanced sleeve systems designed for precision fracturing sequences.
Recent corporate activity highlights the pace of strategic adaptation within the sector. Expansion into international markets, targeted product launches, and the introduction of specialty systems for demanding well conditions all point to a competitive environment where differentiation is increasingly tied to engineering capability and geographic responsiveness. The report integrates these developments into a broader competitive assessment, examining how recent launches, delivery milestones, and portfolio broadening initiatives influence market positioning. By tracking these movements, the analysis provides a practical framework for evaluating which companies are strengthening their foothold in core segments, which are extending into adjacent application areas, and where partnership or procurement opportunities may emerge.
Worldwide Intelligent Well Completion Market
Regulatory Pressures, Material Constraints, and Operational Realities
Strategic planning in the well completion equipment market cannot be separated from the regulatory and material conditions that shape procurement decisions. Over the past year, the operating environment has been influenced by updated emissions requirements, revised performance standards, and shifting raw material cost dynamics. These factors do not merely affect compliance costs. They influence equipment specifications, design priorities, and the economic calculus behind technology selection.
Regulatory developments have placed renewed emphasis on reduced-emission completion practices and tighter performance expectations for hydraulically fractured wells. Updated federal guidance and extended performance standards have required operators to align completion workflows with broader environmental objectives, reinforcing the importance of equipment that supports emissions management, pressure control, and well integrity verification. At the same time, industry standards continue to serve as a baseline for equipment validation, ensuring that critical components such as subsurface safety valves and packers meet established requirements for personnel protection, environmental safeguarding, and asset reliability. The research maps these regulatory and standards-driven considerations into practical implications for equipment procurement, service planning, and long-term compliance strategy.
On the supply side, material cost dynamics have introduced a notable restraint in certain equipment categories. Fluctuations in metal pricing, influenced by global oversupply conditions, have affected input costs for components used in completion tools and packer manufacturing. While these cost pressures are not uniform across all product lines, they highlight the vulnerability of equipment economics to commodity market cycles and procurement timing. The study addresses these influences not as isolated headwinds, but as structural variables that affect pricing strategy, inventory planning, and supplier negotiations. By placing material constraints within the broader market context, the analysis equips decision-makers with a more realistic assessment of cost trajectories and procurement risk.
Well Completion Equipment Market
What the Report Delivers: An Executive Toolkit for 2026 Decisions
This market research is designed as an operational decision-support asset, not a passive overview. It translates broad market movement into a structured intelligence framework that can be applied to budgeting, procurement strategy, technology evaluation, and competitive benchmarking. The report integrates historical performance data, forecast modeling, segmentation analysis, competitive profiling, and market-structure indicators into a single coherent narrative. Its objective is to give executives and planning teams a clearer view of where demand is building, which equipment categories are gaining functional relevance, and how regulatory and material conditions are reshaping the cost and performance equations.
Readers will find detailed segmentation analysis that clarifies how equipment categories and application environments diverge in demand behavior, without reducing the market to simplistic share rankings. The study also examines regional demand patterns, mapping the distribution of activity across major geographic zones to highlight where market intensity is concentrated and where growth opportunities may develop. Competitive profiling extends beyond corporate descriptions, placing each key participant within the context of product focus, recent strategic moves, and market influence. This approach allows users to assess not only who leads today, but how competitive dynamics are likely to evolve as technology adoption, regulatory compliance, and regional expansion continue to reshape the field.
Importantly, the report is structured to support scenario-based planning. Forecast data, market concentration metrics, and equipment-level trends are presented in a way that allows leadership teams to test assumptions about capital deployment, supplier selection, and technology investment. Whether the priority is optimizing completion efficiency, managing compliance exposure, or identifying suppliers with proven capability in demanding well environments, the research provides the contextual foundation needed to make informed, forward-looking decisions.
Conclusion: Positioning for Durable Advantage
The well completion equipment market is entering a period where performance, compliance, and strategic agility will separate resilient organizations from those reacting to short-term cycles. With a forecast trajectory extending through 2032, a concentrated competitive landscape, and evolving regulatory and material conditions, the sector rewards those who can read structural signals early and align equipment strategy with long-term operational goals. This research study is built to support that objective. It offers a disciplined, data-grounded perspective on market scale, segmentation, competitive dynamics, and the external forces shaping procurement and technology choices.
For leadership teams preparing 2026 capital plans, supplier evaluations, and completion strategy reviews, the report delivers the analytical depth required to move beyond surface-level market narratives. Detailed segmentation breakdowns, equipment-level demand drivers, regional activity patterns, and full competitive profiling are available in the complete study. Explore the full market intelligence framework to access the precise data, forecasts, and strategic assessments needed to guide your next decisions with confidence.
For detailed analysis of this topic, please visit the official page: Well Completion Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


