



PW Consulting Report: Trailer Refrigeration Market Hits $544.07 Million in 2025, Projected 5.67% CAGR to 2032

Navigating the Cold Chain: Strategic Imperatives in the Trailer Refrigeration System Market (2026–2032)
The global supply chain stands at a critical inflection point. As logistics networks strive for greater resilience, efficiency, and environmental compliance, the trailer refrigeration system market has emerged as a vital enabler of modern cold chain integrity. From temperature-sensitive pharmaceuticals to perishable food shipments crossing continents, the reliability of transport refrigeration directly influences product safety, regulatory adherence, and commercial viability. PW Consulting's latest in-depth market analysis, Trailer Refrigeration System Market: Global Industry Outlook 2026–2032 , offers a comprehensive strategic roadmap for executives, investors, and supply chain leaders seeking to navigate this rapidly evolving landscape.
Trailer Refrigeration System Market
This report is engineered not merely as a statistical compendium, but as a decision-support instrument. Drawing on rigorous primary research, proprietary modeling, and granular competitive intelligence, the study quantifies market trajectories, dissects segment-level value drivers, and evaluates the operational and regulatory forces reshaping the industry. For organizations operating in 2026, when capital allocation, product roadmapping, and compliance strategy demand precision, this analysis delivers the contextual clarity needed to move beyond reactive tactics and toward sustained competitive advantage.
Market Trajectory: A Decade of Measured Expansion
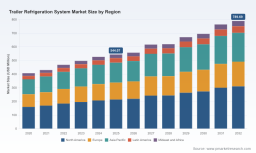
The historical trajectory of the trailer refrigeration system market reflects a sector characterized by steady organic growth, punctuated by technological modernization and regulatory evolution. Between 2020 and 2025, global revenue expanded from approximately 406.5 million USD to 544.1 million USD, demonstrating consistent demand absorption across developed and emerging logistics corridors. This upward momentum is projected to continue through the 2026–2032 forecast horizon, with the market expected to surpass 789.7 million USD by the close of the decade.
At the core of this expansion lies a compound annual growth rate of 5.67 percent, a figure that signals more than nominal market scaling. It indicates structural demand amplification driven by cold chain formalization, e-commerce fulfillment requirements, and the ongoing transition toward temperature-controlled freight solutions. For industry participants, this growth profile carries strategic weight: it suggests a market that is neither saturated nor speculative, but rather one where disciplined investment, product differentiation, and regional execution discipline can yield meaningful returns.
The forecast period also reveals nuanced dynamics that warrant executive attention. Growth is not uniform; it is being reshaped by shifting equipment preferences, ambient performance expectations, and the accelerating adoption of connected refrigeration platforms. Organizations that align their strategy with these underlying currents will be better positioned to capture share in a market where incremental operational efficiencies translate directly into margin preservation and customer retention.
Strategic Segmentation: Where Value Is Created and Captured
The report's segmentation framework is designed to illuminate how revenue flows through distinct equipment configurations, application verticals, and geographic corridors. Rather than treating the market as a monolith, the analysis isolates the structural factors that determine unit economics, competitive positioning, and long-term growth potential.
- Equipment Architecture: The market continues to be shaped by a diversified mix of power architectures, including electric, diesel, and hybrid configurations. Each pathway presents distinct trade-offs in total cost of ownership, emissions performance, grid dependency, and operational range. The analysis examines how fleet operators weigh these variables against deployment environments, regulatory exposure, and sustainability commitments, offering insight into where capital is naturally gravitating as infrastructure and policy conditions mature.
- Application End-Market Demand: Food and beverage logistics remain the dominant commercial driver, reflecting the scale and frequency of perishable goods movement. Simultaneously, pharmaceuticals and chemicals represent a high-value, compliance-intensive segment where temperature excursion risk carries disproportionate financial and reputational consequences. The report evaluates how these verticals differ in procurement behavior, service expectations, and receptivity to advanced monitoring and electric platform adoption.
- Regional Demand Patterns: Geographic distribution of demand is influenced by freight volume concentration, cold chain maturity, regulatory intensity, and local manufacturing or assembly ecosystems. The analysis maps how these factors intersect to create uneven but predictable growth pockets, helping stakeholders prioritize market-entry sequencing, service-network design, and partnership strategies without relying on blunt regional generalizations.
By contextualizing segmentation through an operational lens, the study equips readers to identify which sub-markets offer the most favorable risk-adjusted opportunities, where product specifications must evolve to meet segment-specific requirements, and how pricing architecture should adapt to preserve value across heterogeneous customer bases.
Road Transport Refrigeration Equipment Market
Competitive Dynamics: Incumbents, Innovation, and Consolidation Signals
Market structure analysis reveals a moderately concentrated landscape, with the top three participants collectively accounting for nearly half of total industry revenue and the leading five firms representing over 71 percent of market value. This concentration underscores the competitive advantage held by established players with scaled manufacturing capacity, broad service networks, and deep engineering heritage. Yet concentration alone does not dictate competitive outcomes; it intensifies the premium on differentiation, compliance readiness, and ecosystem integration.
Several core participants define the current competitive baseline. Carrier Transicold, headquartered in Charlotte, North Carolina, maintains a comprehensive portfolio spanning single-temperature and multi-temperature trailer refrigeration units, electric and stationary configurations, and heating platforms, reinforced by its ecoForward sustainability technologies. Thermo King, based in Woodridge, Illinois, competes with its Precedent trailer solutions, T-90 Series architecture, ConnectedSuite telematics capabilities, and TriPac auxiliary power units, while expanding its all-electric and e-reefer offerings with an emphasis on emissions-compliant performance. Polar King Mobile, operating from Fort Wayne, Indiana, has carved a distinct position with all-electric compact refrigerated trailers engineered for modular deployment, E-Track readiness, and NATM compliance, utilizing refrigeration systems capable of maintaining precise temperature bands across demanding transit conditions.
The competitive narrative is further shaped by recent product and regulatory milestones that illustrate how the market is evolving in real time. In early 2026, Utility Trailer Manufacturing Company and Cargobull North America introduced next-generation hybrid transport refrigeration units designed for enhanced cooling performance and efficiency within their 3000R refrigerated trailer lineup. Around the same period, Polar King previewed fresh trailer innovations at a major industry expo, signaling continued product iteration in the compact electric segment. These developments unfold against a backdrop of tightening regulatory architecture, including updated cold appliance emissions standards and refrigerant guidance that increasingly steer procurement decisions toward lower-global-warming-potential solutions and zero-emission transition pathways.
For corporate strategists, the implication is clear: competitive advantage in this market is increasingly determined by how effectively firms integrate regulatory foresight into product design, align service and telematics capabilities with fleet customer expectations, and communicate verifiable sustainability performance without sacrificing operational reliability.
Regulatory and Technological Currents Reshaping the Market
No strategic assessment of the trailer refrigeration system market is complete without a rigorous examination of the regulatory environment. Compliance is no longer a peripheral concern; it is becoming a primary determinant of equipment eligibility, total cost of ownership, and long-term asset viability. Over the past several years, regulators have steadily tightened emissions expectations for transport refrigeration units, with particular emphasis on refrigerant global warming potential thresholds, particulate emission controls, and registration and reporting obligations for owners and large facilities.
These regulatory pressures are compounded by evolving refrigerant chemistry and component standards. The industry's shift toward lower-GWP refrigerant blends reflects a broader transition toward systems that can meet compliance mandates without compromising cooling capacity or serviceability. At the same time, telematics and connected monitoring are transitioning from value-added features to operational necessities, enabling fleet managers to track temperature excursions, optimize preventive maintenance, and demonstrate compliance documentation with greater precision.
The interaction between regulation and technology creates a distinctive strategic environment. Equipment that meets current compliance thresholds may still face retrofit risk or shortened service life if future amendments tighten standards further. Conversely, platforms designed with forward-looking architecture can reduce transition costs, preserve resale value, and strengthen supplier credibility with compliance-sensitive customers. The report evaluates these dynamics in detail, helping organizations distinguish between compliance-driven costs and strategic investments that build durable market positioning.
What This Report Delivers for 2026 Decision-Makers
PW Consulting's market study is structured to convert complex industry data into actionable strategic intelligence. The analysis extends beyond high-level sizing to address the operational and commercial questions that executives face when allocating resources, evaluating competitive threats, and planning product or service expansion. Key deliverables include:
- Market sizing and forecast architecture that provides a transparent view of historical performance and projected growth pathways, enabling scenario planning around demand sensitivity, adoption pacing, and external shocks.
- Segment-level evaluation that isolates the structural drivers behind equipment type preferences, application-specific procurement patterns, and regional demand concentration, supporting more precise go-to-market and investment decisions.
- Competitive profiling that maps the strategic positioning, product offerings, and recent activity of leading participants, with context on how innovation, service capability, and compliance readiness influence share dynamics.
- Regulatory and technology impact assessment that connects emissions standards, refrigerant transitions, telematics adoption, and enforcement trends to practical procurement, design, and service implications.
- Strategic recommendation frameworks tailored to manufacturers, component suppliers, fleet operators, and investors, helping each audience translate market signals into prioritized actions for capacity planning, R&D focus, partnership strategy, and risk mitigation.
By integrating quantitative forecasts with qualitative market intelligence, the report enables readers to stress-test assumptions, identify where consensus expectations may understate or overstate opportunity, and build strategies that remain robust across a range of plausible futures.
Conclusion: Turning Market Intelligence into Strategic Action
The trailer refrigeration system market in 2026 is defined by a convergence of forces: durable cold chain demand, accelerating sustainability mandates, technological differentiation in electric and hybrid platforms, and a competitive field where scale and service quality remain powerful advantages. Growth projections indicate that the sector will continue expanding toward the high-700-million-USD range by 2032, but the more consequential question for decision-makers is not simply how large the market will become, but how value will be distributed across segments, regions, and competitive tiers.
Organizations that treat this market as a purely mechanical equipment category risk overlooking the strategic levers that determine long-term performance: compliance architecture, telematics-enabled service differentiation, segment-specific product customization, and disciplined regional execution. Those that approach it as a strategically layered ecosystem will be better positioned to protect margins, win compliance-sensitive contracts, and build defensible relationships with fleet customers who increasingly evaluate suppliers on total value rather than unit price alone.
This report provides the depth, structure, and forward-looking context required to make those judgments with confidence. To access the full dataset, detailed segmentation analysis, competitive benchmarking, and scenario-based strategic guidance, we invite executives and research buyers to visit the source page for the complete PW Consulting market intelligence package.
For detailed analysis of this topic, please visit the official page: Trailer Refrigeration System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


