



PW Consulting Report: Compressor Blades Market Hits $12.5 Billion in 2025, Forecasts 5.2% CAGR Through 2032

Navigating the Next Phase of Growth: Strategic Intelligence for the Compressor Blades Market
In an era defined by rapid technological evolution and stringent regulatory oversight, the compressor blades sector stands at a critical inflection point. As propulsion systems demand higher efficiency, lighter weight, and enhanced durability, manufacturers and investors must move beyond surface-level trends to grasp the underlying structural drivers shaping the industry. This article outlines the strategic value of our latest market research, offering a preview of the comprehensive intelligence designed to support confident decision-making throughout the forecast horizon.
The global compressor blades market has demonstrated consistent expansion over the past half-decade, reflecting steady demand across aerospace and industrial energy sectors. Drawing on a robust historical dataset spanning 2020 through 2025 and extending forward to 2032, our analysis establishes a clear trajectory of sustained growth. The market has evolved from a baseline of 9.57 billion USD in 2020 to an estimated 12.5 billion USD in 2025, with projected revenues reaching 17.82 billion USD by 2032. This expansion corresponds to a compound annual growth rate of 5.2 percent across the forecast period, underscoring a mature yet dynamically evolving industry landscape.
Worldwide Gas Turbine Turbine Blades Market
Such macroeconomic momentum is not uniform; it is propelled by intersecting technological, regulatory, and operational forces that require nuanced strategic interpretation. Our research dissects these drivers to reveal where capital allocation, supply chain optimization, and product development efforts will yield the highest marginal returns. Rather than presenting static figures, the report contextualizes growth within real-world operational constraints, procurement cycles, and engineering imperatives that define competitive advantage.
Decoding Market Architecture Through Actionable Segmentation
To translate broad market trajectories into executable strategy, our report constructs a multidimensional segmentation framework that isolates the structural components of demand. The analysis examines compressor blade categories differentiated by operational pressure profiles, highlighting how high-pressure variants and low-pressure alternatives serve distinct engineering requirements and procurement cycles. Each category carries unique material specifications, manufacturing tolerances, and lifecycle considerations that influence pricing dynamics, lead times, and aftermarket opportunities.
Similarly, the application landscape is dissected across aviation engines, industrial gas turbines, and turbocharger systems. These segments operate under divergent performance benchmarks, regulatory environments, and replacement cadences. By mapping demand intensity, technological readiness, and procurement predictability across these applications, the report equips strategists with the clarity needed to prioritize product roadmaps and market entry initiatives without relying on oversimplified generalizations.
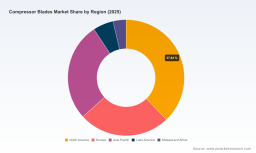
Regional dynamics are explored with equal rigor, examining how established aerospace hubs, emerging manufacturing corridors, and defense procurement centers contribute to overall market momentum. The geographic breakdown illuminates disparities in supply chain maturity, local content requirements, and infrastructure readiness, enabling organizations to calibrate their operational footprint and risk exposure accordingly. Throughout this analysis, the report deliberately reserves granular percentage splits and region-specific revenue figures for the full dataset, ensuring that strategy teams engage with the complete intelligence package before committing to allocation decisions.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The compressor blades industry exhibits a moderately consolidated structure, with the top three players commanding approximately 45.6 percent of market revenue and the top five collectively controlling 62.3 percent. This concentration reflects the high barriers to entry inherent in precision aerospace manufacturing, including advanced metallurgy capabilities, certified quality management systems, and long-cycle customer relationships. Yet beneath this consolidated core lies a diverse ecosystem of specialized manufacturers, repair providers, and component integrators that compete on precision, lead time, and niche engineering expertise.
Our competitive analysis profiles a broad spectrum of incumbent leaders and specialized operators, mapping their strategic positioning across commercial aviation, military propulsion, and industrial applications. Organizations such as GKN Aerospace, Rolls-Royce Holdings, and Safran S.A. anchor the high-end aerospace segment, leveraging advanced composites, titanium alloy production, and integrated gas turbine designs to sustain performance leadership. RTX Corporation and Pratt & Whitney reinforce their positions through engine program integration, spanning commercial platforms and military series such as the F100 family, while MTU Aero Engines and IHI Corporation extend their reach across both aircraft and industrial gas turbine applications.
The competitive field also includes precision manufacturers and supply chain specialists that enable agility and cost efficiency across a range of platforms. Howmet Aerospace, Chromalloy, Hi-Tek Manufacturing, TURBOCAM International, Moeller Aerospace, Doncasters Group, Farinia Group, Stork B.V., Blades Technology, Pacific Sky Supply, and Collins Aerospace each contribute distinct capabilities, from titanium alloy precision machining to aftermarket repair and component substitution services. Mitsubishi Heavy Industries rounds out the landscape with dual-use aero and industrial competence. By evaluating these players through lenses of technology ownership, vertical integration, geographic reach, and aftermarket competency, the report reveals where consolidation pressure may intensify, where partnership opportunities are most viable, and where new entrants could capture niche share.
Importantly, the report does not merely catalog competitors; it assesses the strategic implications of their product architectures, procurement dependencies, and capacity utilization patterns. This enables executives to benchmark their own positioning, identify vulnerability in single-source dependencies, and evaluate potential consolidation or joint development scenarios with a clear understanding of market concentration dynamics.
Regulatory Pressures and Operational Dynamics Reshaping Demand
Beyond structural segmentation and competitive positioning, the compressor blades market is increasingly shaped by regulatory mandates, sustainment contracts, and in-service durability considerations. Recent regulatory activity illustrates how safety-driven interventions can rapidly alter demand patterns and procurement timelines. In November 2025, the FAA announced plans to mandate the replacement of specific V2500 high-pressure compressor stage 3 rotor blades to address durability issues identified in operational service. This enforcement trajectory highlights the direct link between airworthiness oversight and replacement demand, reinforcing the importance of aftermarket readiness, traceability, and rapid response manufacturing capabilities.
Parallel defense procurement activity further illustrates the interplay between regulatory programming and component demand. In August 2025, the Defense Logistics Agency Aviation issued contract SPRTA1-25-R-0356, requiring procurement of compressor blade sets for F100-229 engines with delivery scheduled by May 31, 2026. Shortly thereafter, in January 2026, the Air Force Sustainment Center solicited support for TF33 first-stage compressor blade repair, with a due date in early February 2026. These actions underscore the persistent demand generated by military sustainment cycles, engine modernization programs, and the operational necessity of maintaining readiness across legacy and current-generation platforms.
These developments are integrated into the report’s market dynamics section, where regulatory trajectories, procurement calendars, and durability-driven replacement cycles are analyzed as strategic levers rather than isolated events. Organizations that internalize these patterns can better align production scheduling, inventory positioning, and repair network investments with the rhythm of mandated replacements and defense procurements. The research deliberately abstracts away from exposing specific contract values or segment-level percentages, preserving the analytical edge of the full report while demonstrating its relevance to near-term operational planning.
What the Full Study Delivers: A Practical Toolkit for Decision-Makers
While this overview signals the strategic scope of the research, the complete study provides an operational toolkit designed for cross-functional deployment. The report integrates historical performance analysis with forward-looking scenario modeling, enabling teams to test assumptions around capacity expansion, material sourcing, and aftermarket service growth. Decision-makers gain access to a structured examination of manufacturing technologies, including precision machining, titanium alloy processing, and composite integration, alongside an evaluation of how these capabilities influence cost structures, cycle times, and qualification pathways.
The study also maps supply chain architecture across raw material inputs, subcomponent fabrication, assembly, and repair ecosystems. By illuminating concentration risks, lead-time variability, and regional sourcing constraints, the report helps organizations design more resilient procurement strategies and evaluate vertical integration or supplier diversification options. In addition, the analysis includes an assessment of aftermarket dynamics, where replacement cycles, repairability thresholds, and airworthiness compliance converge to shape recurring revenue opportunities and service-level commitments.
Strategists will also find dedicated attention to product development implications. The report evaluates how performance requirements across aviation engines, industrial gas turbines, and turbocharger applications influence airfoil design, cooling architectures, and material selection, translating engineering priorities into commercially relevant investment guidance. Throughout, the research maintains a disciplined focus on actionable insight, ensuring that every analytical module connects to a decision context—whether that involves capacity planning, market entry, partnership evaluation, or risk mitigation.
To preserve the integrity of this intelligence and encourage rigorous strategic application, certain granular data points are reserved for the full report. This includes segment-specific revenue contributions, regional value splits, detailed company-level capability matrices, and proprietary scenario outputs. The intent is not to withhold value, but to ensure that the depth of analysis is experienced in its complete form, allowing executives and analysts to draw conclusions with full context rather than fragmented snapshots.
Compressor Blades Market
Strategic Imperatives for 2026 and Beyond
As organizations enter the 2026 planning cycle, the compressor blades market presents a landscape where disciplined intelligence can differentiate resilient strategies from reactive maneuvers. The convergence of steady top-line growth, concentrated competition, regulatory-driven replacement demand, and sustainment procurement creates a multi-layered environment that rewards analytical precision. Companies that align their product portfolios with durability mandates, fortify their supply chains against regional and material constraints, and calibrate their aftermarket capabilities to replacement cycles will be best positioned to capture value across the forecast window.
This research is designed to support that alignment. By combining macro trajectory analysis with segment-level architecture, competitive dynamics, regulatory context, and operational supply chain evaluation, the report delivers a comprehensive vantage point for strategy formulation. The 5.2 percent compound annual growth pathway to 2032 is not merely a headline figure; it is a signal of sustained demand intensity that must be interpreted through the lenses of application specificity, pressure-class differentiation, and geographic readiness.
For leadership teams seeking to translate market momentum into concrete plans, the full study offers the structured evidence base required to reduce uncertainty and accelerate decision velocity. We invite executives, strategy directors, and industry analysts to engage with the complete dataset, where the detailed segmentation splits, proprietary competitive assessments, and forward scenario tools are available in their entirety. In a market where precision, compliance, and timing determine outcomes, comprehensive intelligence is not an optional enhancement—it is the foundation of durable competitive strategy.
For detailed analysis of this topic, please visit the official page: Compressor Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


