



PW Consulting: B Flam Retardants Market to Hit $1,695M by 2032, 7.65% CAGR

Strategic Imperatives in the BDP Flame Retardants Market: A 2026 Outlook
The global chemical landscape is undergoing a seismic shift. As industries pivot toward sustainability and stringent safety protocols, the demand for high-performance materials has never been more critical. Within this complex ecosystem, Bisphenol A bis(diphenyl phosphate), commonly known as BDP, has emerged as a cornerstone solution for halogen-free flame retardancy. For stakeholders navigating the chemical value chain, understanding the trajectory of the BDP market is not merely an academic exercise but a fundamental requirement for strategic planning in 2026 and beyond.
PW Consulting is pleased to introduce our comprehensive market research study on the BDP Flame Retardants Market. This document serves as a strategic overview, highlighting the macroeconomic currents, competitive dynamics, and regulatory pressures that are defining the sector. While this preview outlines the structural framework of the industry, the full report provides the granular intelligence necessary to capitalize on emerging opportunities.
Market Trajectory and Macroeconomic Context
The BDP Flame Retardants Market has demonstrated remarkable resilience and growth over the past five years. Our analysis tracks historical performance from 2020 through 2025, establishing a robust baseline for forecasting future trends. During this historical window, the industry has navigated supply chain disruptions, raw material volatility, and shifting regulatory landscapes to achieve consistent expansion.
Looking ahead, the forecast period spanning 2026 to 2032 paints a picture of sustained momentum. The market is projected to grow at a compound annual growth rate (CAGR) of 7.65 percent throughout this forecast horizon. This growth trajectory suggests that the industry will expand significantly beyond its current valuation, driven by the dual engines of electrification in transportation and the stringent safety requirements in electrical and electronics sectors.
Fiscal milestones in the near term indicate steady consolidation of market value. By 2026, the market is expected to reach a valuation of approximately 1062.38 Million USD. This upward curve continues as we move through the late 2020s, with projections suggesting the market will surpass 1504.22 Million USD by 2030. Ultimately, the sector is poised to approach 1695.0 Million USD by the end of the forecast period in 2032. These figures underscore the long-term viability of BDP as a critical chemical intermediate and finished additive.
Such macroeconomic indicators are essential for capacity planning and investment decisions. However, top-line numbers only tell part of the story. To truly leverage this growth, enterprises must understand the specific drivers within material types, application sectors, and geographic regions, all of which are dissected in the full PW Consulting report.
Industry Dynamics: The Shift Toward Halogen-Free Solutions
The fundamental force propelling the BDP market is the global regulatory crackdown on halogenated flame retardants. For decades, brominated compounds served as the industry standard due to their efficacy and cost structure. However, environmental persistence and toxicity concerns have triggered a regulatory wave that is reshaping procurement strategies across multiple industries.
Recent industry intelligence highlights a stark divergence in cost structures between traditional brominated solutions and phosphorus-based alternatives like BDP. Specifically, the price of decabromodiphenyl ethane, a common brominated flame retardant, has seen significant escalation, rising from approximately 30,000 yuan/ton in 2017 to around 60,000 yuan/ton in recent years. This price inflation is largely attributable to policy restrictions that have constrained production and increased compliance costs for brominated manufacturers.
In contrast, the PC+BDP system is gaining traction due to its economic advantages. Recent data indicates that the PC+BDP system offers a cost advantage of roughly 0.18 million yuan/ton compared to ABS+bromine alternatives. This economic efficiency, combined with performance parity, makes BDP an increasingly attractive option for compounders and OEMs looking to optimize material costs without compromising safety standards.
Furthermore, the raw material landscape supports this transition. Global ABS production capacity currently stands at 7.35 million tons, whereas PC capacity is at 5.56 million tons. Despite the capacity differential, the strategic advantage of integrating BDP into PC-based alloys lies in the ability to meet UL94 V0 compliance standards efficiently. This dynamic is forcing downstream expansion, not just due to policy mandates, but because cost factors are actively driving increased demand for phosphorus-based flame retardants.
Competitive Landscape and Key Players
The BDP market is characterized by a moderately concentrated competitive environment. Analysis indicates that the top three companies hold a CR3 of 35.2 percent, while the top five players command a CR5 of 42.8 percent. This structure suggests that while large players dominate significant market share, there is ample room for specialized manufacturers to capture niche segments through technological differentiation and supply chain reliability.
BDP Flame Retardants Market
Several key enterprises are actively shaping the market through production capacity expansion, product innovation, and strategic marketing. Oceanchem Group Limited, based in Weifang, Shandong, stands out as an active supplier of phosphorus-based halogen-free flame retardants. With a substantial production capacity of 40,000 tpa, Oceanchem focuses on BDP used in PC/ABS and engineering plastics for UL94 V0 compliance. Their recent activity includes updating product data sheets to clarify application details for fire-retardant use, signaling a commitment to technical transparency.
In the Zhejiang province, Hangzhou Mei Wang Chemical Co., Ltd. has been particularly active in 2025. They manufacture Mflam BDP specifically for PC/ABS resins, typically requiring a 10-15 percent dosage to achieve UL94 V0 at 1.6 mm thickness. Their market presence was highlighted by successful participation in major industry events such as K Show 2025 in Düsseldorf and KOPLAS 2025 in South Korea. These exhibitions showcased innovative flame retardant solutions, emphasizing their role in pioneering solutions for challenging PC/ABS systems. Additionally, their participation in ChinaPlas Shenzhen 2025 marked the introduction of latest flame retardant products to the market.
Other notable manufacturers include Jining Green Mountain Chemical Co., Ltd., which supplies BDP non-halogen flame retardants for engineering plastics including PC/ABS, PPO/HIPS, and ABS, emphasizing low volatility and high thermal stability. Ningbo Haopu Chemical Co., Ltd. produces BDP for a wide range of engineering plastics and thermoplastics alloys, including ABS, HIPS, PC, and PPO. International presence is maintained by DAI HACHI Chemical Industry Co., Ltd. in Japan, which manufactures CR-741 (BDP) phosphorus flame retardant for plastics. Additionally, Sinobio Chemistry operates as a key manufacturer and supplier of BDP Bisphenol A bis(diphenyl phosphate) CAS 5945-33-5 for halogen-free applications.
These companies are not merely producing chemicals; they are engaging in active collaboration and development. Presentations at 2025 K-SHOW focused on future development and collaboration opportunities for halogen-free flame retardants, indicating a shift toward partnership-driven innovation rather than isolated manufacturing.
Segmentation and Application Drivers
Understanding where the demand originates is crucial for targeted market entry. The BDP market is segmented by type, application, and region. In terms of material type, the market is driven by specific engineering plastic systems. PC/ABS blends represent a significant portion of demand, leveraging BDP for flame retardancy without sacrificing mechanical properties. PCB/Epoxy systems and Polyphenylene Oxide Alloys also constitute vital segments, each requiring tailored formulation strategies to achieve optimal performance.
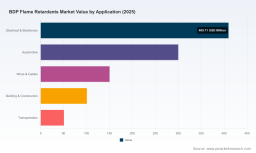
By application, the Electrical & Electronics sector remains a primary consumer of BDP flame retardants. As devices become more compact and powerful, the need for materials that prevent fire propagation without releasing toxic halogenated smoke becomes paramount. The Automotive sector is another critical growth vector, driven by the electrification of vehicles where battery enclosures and interior components require high-level fire safety. Wires & Cables, Building & Construction, and Transportation sectors also contribute to the aggregate demand, each with unique regulatory and performance requirements.
Geographically, the market is well-distributed. North America, Europe, and Asia Pacific each represent significant shares of the global revenue landscape. Asia Pacific, in particular, reflects the manufacturing hub status of the region, while North America and Europe are key markets for high-end engineered solutions driven by strict safety regulations. Latin America and the Middle East and Africa represent emerging territories with growing industrialization needs.
To fully understand the nuance of these segments, including specific growth rates and volume distributions for each category, stakeholders require the detailed breakdown provided in our full analysis. The aggregate data suggests a balanced but dynamic growth pattern across these verticals.
Strategic Recommendations for 2026 Decision Making
For corporate strategists and procurement leaders, the 2026 outlook for BDP Flame Retardants presents both risks and opportunities. The clear trend is away from halogenated chemistry and toward phosphorus-based systems. Companies that fail to adapt their supply chains to accommodate halogen-free alternatives may face regulatory hurdles and cost inefficiencies as brominated materials become increasingly expensive and scarce.
Procurement strategies should focus on securing stable partnerships with manufacturers who have demonstrated capacity and technical competence, such as those detailed in our competitive landscape analysis. With CR3 concentration at 35.2 percent, diversification of supply sources is advisable to mitigate risk, while also engaging with specialized players who offer superior technical support for specific polymer systems like PC/ABS.
Furthermore, R and D investments should align with the cost advantages identified in recent raw material analyses. The economic benefit of PC+BDP systems over traditional alternatives provides a strong business case for material substitution in new product designs. Companies should evaluate their current material portfolios against the latest regulatory standards and cost structures to identify immediate areas for optimization.
Market entry timing is also critical. With the forecast period extending to 2032, early movers who establish supply relationships and product specifications now will be better positioned to capture market share as the total market size expands toward 1695.0 Million USD. Waiting until regulatory pressures peak may result in higher input costs and limited supplier availability.
Accessing Complete Market Intelligence
This article provides a strategic framework for understanding the BDP Flame Retardants Market in the context of 2026 planning. We have explored the macroeconomic growth trajectory, the regulatory shift away from brominated compounds, the competitive dynamics among key manufacturers, and the segmentation drivers that define demand. However, successful execution requires data depth that goes beyond these high-level summaries.
Fire Retardant Additives Market
PW Consulting's full BDP Flame Retardants Market Report offers the granularity needed to make informed, high-stakes decisions. From detailed historical data series covering 2020 to 2025 to precise forecasts through 2032, our research provides the numerical backbone for your strategic models. The report delves into specific volume splits, regional nuances, and company-level profiling that cannot be fully disclosed in this preview.
To secure your competitive edge and gain access to the complete dataset, including detailed segmentation splits and comprehensive company profiles, we invite you to visit the source webpage for this study. Equip your organization with the precise intelligence needed to navigate the evolving flame retardant landscape.
For detailed analysis of this topic, please visit the official page: BDP Flame Retardants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


