



PW Consulting: Novel Drug Delivery Market to Hit $213.89B by 2032, CAGR 5.7%

Navigating the Next Frontier: Strategic Insights into the Novel Drug Delivery Systems Market for 2026 and Beyond
The pharmaceutical landscape is undergoing a paradigm shift, driven by the urgent need to enhance patient compliance, improve therapeutic efficacy, and enable decentralized care models. At the forefront of this transformation is the Novel Drug Delivery Systems Market. As we move through 2026, this sector represents more than just technological innovation; it is a critical battleground for competitive advantage, portfolio optimization, and long-term revenue stability. Our latest comprehensive market research report, "Novel Drug Delivery Systems Market: Strategic Forecast 2026–2032," provides the intelligence necessary for stakeholders to navigate this complex environment.
This article serves as a strategic primer to the full study, outlining the macroeconomic trajectory, competitive dynamics, and structural challenges that define the industry. While visibility into high-level trends is essential, the granularity required for actionable decision-making demands deeper access. The following analysis highlights the strategic value embedded within our full dataset, helping executives understand where to focus resources for maximum impact.
Worldwide Novel Vaccine Delivery Systems Market
Macroeconomic Trajectory and Growth Dynamics
Understanding the top-line market potential is the first step in strategic planning. The Novel Drug Delivery Systems Market has demonstrated resilience and consistent expansion over the past decade, transitioning from a niche interest to a core component of pharmaceutical value chains. Our analysis of historical performance from 2020 through 2025 reveals a steady upward curve, culminating in a robust market valuation at the end of the base year. This historical momentum sets the stage for the forecast period, where compound growth is expected to accelerate as technologies mature and regulatory pathways become clearer.
For 2026, the market is positioned to cross significant thresholds. The initial forecast year marks a transition point where early adopters begin to reap returns on substantial research and development investments made during the previous lifecycle. Looking further ahead to 2032, the projection indicates sustained expansion, suggesting that novel delivery mechanisms will not remain a supplemental strategy but will instead become integral to next-generation therapeutics. The Compound Annual Growth Rate (CAGR) calculated for the forecast period underscores a moderate yet reliable growth trajectory, characteristic of a maturing high-value sector.
However, aggregate figures only tell part of the story. The true strategic opportunity lies in understanding how this growth is distributed across segments, geographies, and technology types. Market concentration remains high, indicating that skimming strategies require precise positioning rather than broad market appeals. For detailed breakdowns of revenue pools by specific technology type, application area, product form factor, and regional hubs, our full report provides the segmented revenue tables necessary for accurate bottom-up modeling.
Novel Drug Delivery Systems Market
Segmentation: Where Value is Concentrated
Strategic resource allocation depends on identifying high-value niches. The market is fragmented across various delivery technologies and therapeutic applications, each with distinct adoption curves and reimbursement challenges. In our full research study, we dissect the market into detailed segments to reveal where profit pools are deepest and competition is most ferocious.
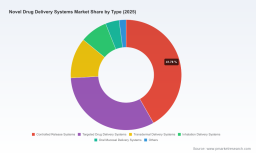
- By Technology Type: Controlled release and targeted delivery systems continue to dominate the value chain, reflecting the industry's focus on pharmacokinetic optimization. However, emerging categories such as transdermal and inhalation systems are gaining traction due to their alignment with home-care trends.
- By Therapeutic Application: Chronic disease management represents the largest revenue driver. Oncology remains a critical pillar due to the need for precise dosing and reduced systemic toxicity. Cardiovascular and diabetes segments follow closely, driven by the demand for patient-friendly administration methods that improve adherence.
- By Product Form: The shift from traditional injectables toward advanced carriers like liposomes and nanoparticles is evident. Microspheres and patches are also carving out significant shares, particularly in markets demanding sustained release profiles.
- By Region: Established markets in North America and Europe continue to hold substantial revenue share, leveraging mature regulatory frameworks and high healthcare expenditure. Meanwhile, the Asia Pacific region presents a high-growth opportunity, fueled by generic formulation advancements and increasing local manufacturing capabilities.
While these categories provide a framework, the specific revenue contributions, growth rates, and relative market shares for each segment are detailed exclusively in the downloadable dataset. Accessing these specific figures allows firms to benchmark their pipeline against the most lucrative segments and identify white spaces before competitors do.
Competitive Landscape and Innovation Hubs
The market is characterized by a mix of established pharmaceutical giants and agile technology specialists. Our competitive analysis maps the strategic moves of key players who are reshaping the delivery ecosystem through acquisitions, partnerships, and novel product launches. Success in this environment requires more than just product efficacy; it requires connectivity, patient-centric design, and robust supply chain resilience.
Technology Enablers and Specialists: Companies like Satio, Inc. are pushing the boundaries of home-based care. Their Digital SatioRx system exemplifies the trend toward telehealth-enabled settings, utilizing a low-cost, motor-driven applicator with hollow microneedle cartridges for intradermal delivery. This approach aligns with broader regulatory pushes, such as ARPA-H SBIR contracts, which support the development of novel intradermal systems to enable home-based care with reduced costs. Similarly, ZIM Laboratories Limited focuses on proprietary technology-based solutions for oral formulations, including taste-masked powders and oral thin films for sustained release, addressing compliance issues in generic markets. SQ innovation contributes to the wearable device landscape with reusable infuser systems for subcutaneous administration of heart failure drugs.
Big Pharma and Biologics: Established players are leveraging novel delivery to extend the lifecycle of blockbuster therapies. Johnson & Johnson has been active with IMAAVY™, a monoclonal antibody approved for subcutaneous administration in generalized myasthenia gravis. In 2025, they secured FDA approval for this formulation, and by early 2026, they submitted supplemental applications for additional indications like warm autoimmune hemolytic anemia. Argenx is similarly expanding its footprint with FcRn blocker monoclonal antibodies, utilizing hyaluronidase for subcutaneous delivery. Recent approvals in 2026 have expanded label indications to include all adult patients with generalized myasthenia gravis, signaling strong commercial momentum.
Manufacturing and Digital Integration: The integration of digital health with drug delivery is a key differentiator. Merck KGaA recently received recognition for a connected autoinjector system that integrates smart injection devices with cloud-based data and patient mobile apps. This convergence of hardware and digital monitoring addresses payer resistance by generating real-world data to support coverage decisions. Bayer AG is exploring cellular therapies using implantation techniques for Parkinson's disease, highlighting the diversification into cell-based delivery methods.
The competitive intensity is underscored by high market concentration levels. A small number of entities control a significant portion of the market value, making market entry challenging without distinct technological advantages or strategic partnerships. Our full report profiles these companies in detail, analyzing their pipeline strategies, recent developments, and potential market share trajectories.
Industry Dynamics and Structural Challenges
Navigating the growth trajectory requires a clear understanding of the headwinds and tailwinds influencing market expansion. Our analysis identifies several critical dynamics that will shape decision-making in 2026 and beyond.
Regulatory Environment: The regulatory landscape is becoming more accommodating for innovation, yet complexity remains. In 2025, FDA novel drug approvals included dozens of new drugs, with multiple novel delivery systems advancing through priority review designations and accelerated pathways. This suggests a favorable environment for well-prepared submissions. However, regulatory clarity varies by region and technology type, requiring nuanced go-to-market strategies.
Reimbursement and Evidence Generation: Payers are increasingly resistant to reimbursing newer platforms without strong clinical evidence. The sector analysis indicates that real-world data is becoming a prerequisite for coverage decisions regarding advanced delivery systems. Companies must plan for robust post-market surveillance and data generation to ensure commercial viability. High development spending and specialized materials also result in elevated production costs compared to conventional formulations, pressuring margins unless premium pricing can be justified.
Supply Chain and Cost Pressures: Global supply disruptions and API availability challenges have caused backlogs impacting the production and availability of novel drug delivery systems. These logistical constraints can delay launches and increase operational costs. Firms must evaluate supply chain resilience as part of their strategic planning, considering geographic diversification and inventory management strategies.
Strategic Imperatives for 2026 Decision-Makers
As organizations plan their moves for the remainder of the decade, several strategic imperatives emerge from our research. First, investment in patient-centric delivery technologies that enable home care and improve adherence is likely to yield higher returns as healthcare systems shift toward value-based care. Second, digital integration is no longer optional; connected devices that provide data feedback loops will be critical for satisfying payer requirements and differentiating products. Third, collaboration between technology specialists and pharmaceutical developers will be essential to navigate the high costs and regulatory hurdles associated with novel platforms.
The window for establishing market leadership in specific niches is narrowing. With market concentration remaining high and major players actively expanding their indications and technologies, late entrants face significant barriers. Early movers who secure intellectual property, establish reimbursement pathways, and build supply chain resilience will be best positioned to capture the projected growth through 2032.
Accessing Detailed Intelligence
This overview provides a high-level strategic context, but effective execution requires granular data. To support precise financial modeling, competitive benchmarking, and segmentation analysis, organizations need access to the full dataset underlying this study. Our complete report offers detailed revenue figures, CAGR calculations for every sub-segment, and deep-dive profiles of key market players and their specific technologies.
For leaders ready to translate market intelligence into actionable strategy, the full "Novel Drug Delivery Systems Market: Strategic Forecast 2026–2032" study is available for review. Secure access to the complete database to unlock the specific numbers and insights required to drive your enterprise forward in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Novel Drug Delivery Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


