



PW Consulting: Gyrocopter Market Hits $166M in 2025, Projected to Reach $271M by 2032 at 7.3% CAGR

Strategic Horizons in the Gyrocopters Market: A 2026 Executive Perspective
Navigating a Maturing Aerial Mobility Sector
The global gyrocopters market stands at a pivotal inflection point as it enters 2026. Over the past half-decade, the industry has transitioned from a niche recreational curiosity into a structured, certification-driven segment of light aviation. Our latest comprehensive research study maps this transformation across a seven-year forecast window, providing executives, investors, and operational strategists with the analytical rigor required to navigate an increasingly complex competitive landscape. The sector has demonstrated consistent expansion, with market revenue climbing steadily from approximately 120.0 million USD in 2020 to a projected 166.0 million USD in 2025. This trajectory reflects not only sustained enthusiast demand but also the gradual institutionalization of gyroplane operations across commercial, training, and specialized aerial applications. As we project forward through 2032, the market is anticipated to follow a disciplined growth curve, reaching an estimated 271.0 million USD by the end of the forecast period. This represents a compound annual growth rate of 7.3 percent, a figure that underscores both the resilience of the underlying demand drivers and the incremental but meaningful structural shifts currently reshaping procurement, certification, and operational deployment strategies.
For corporate decision-makers, the strategic question is no longer whether gyrocopters will gain broader operational relevance, but rather how to position portfolios, supply chains, and go-to-market frameworks to capture value in a market that is simultaneously expanding and fragmenting. The 2026 edition of our market intelligence report is designed precisely to answer that question. Rather than offering a superficial snapshot, the study dissects the operational, regulatory, and competitive forces that will determine which manufacturers, distributors, training providers, and service integrators will capture disproportionate share in the coming years. Executives who approach this sector with the same analytical discipline applied to higher-volume aviation segments will uncover asymmetric opportunities in certification pathways, regional deployment strategies, and application diversification that less prepared competitors will overlook.
Macro Trajectory and the Architecture of Growth
Examining the historical baseline from 2020 through 2025 reveals a market that has matured with remarkable consistency. The progression from 127.81 million USD in 2021 to 133.62 million USD in 2022, followed by a step-up to 143.2 million USD in 2023 and 156.04 million USD in 2024, reflects an ecosystem that has moved beyond post-pandemic recovery dynamics and into a phase of structural consolidation. By 2025, the market had reached 166.0 million USD, setting a robust foundation for the forecast horizon. The projected climb to 183.95 million USD in 2026, 194.71 million USD in 2027, and 203.03 million USD in 2028 indicates sustained momentum, while the larger forward estimates of 213.91 million USD in 2029, 229.39 million USD in 2030, 251.46 million USD in 2031, and 271.0 million USD in 2032 suggest that the market is positioning itself for a more meaningful acceleration as certification frameworks mature and application diversification takes hold.
This growth architecture is not merely a function of unit volume expansion. It reflects a broader recalibration of how gyrocopters are perceived within the light aviation ecosystem. Historically constrained by fragmented certification regimes and limited commercial applicability, gyroplanes are increasingly being evaluated through the lens of operational efficiency, short-field performance, and lower total cost of ownership relative to comparable fixed-wing or rotary alternatives. The 7.3 percent CAGR embedded in our forecast reflects the compounding effect of these dynamics: incremental regulatory clarity, expanding pilot licensing pathways, and a growing recognition of gyrocopter utility in training, tourism, and specialized commercial operations. For strategists, the implication is clear. Market expansion will not be evenly distributed across all participants. Companies that align their product roadmaps, service networks, and compliance capabilities with the contours of this growth curve will be best positioned to translate macro momentum into durable competitive advantage.
The 2026 Decision Framework: Why This Study Matters
The strategic value of this research lies in its deliberate alignment with the operational realities facing executive teams in 2026. Market entry, portfolio optimization, supplier selection, and partnership structuring all require a granular understanding of how demand is distributed across applications, how regional maturity differs, and how regulatory evolution is reshaping the commercial viability of gyroplane operations. Our report is structured to provide exactly that decision-grade intelligence. It moves beyond high-level sizing to examine the operational mechanics that drive procurement cycles, the certification milestones that unlock new revenue streams, and the competitive maneuvers that are redefining market positioning across Europe, North America, and emerging regional markets.
Executives evaluating investment in gyrocopter-related ventures, whether through direct manufacturing, distribution agreements, training infrastructure, or service-network development, will find the study particularly relevant. The forecast window through 2032 allows leadership teams to model scenario-based outcomes, stress-test assumptions around certification timing, and identify the inflection points where early positioning yields disproportionate returns. Equally important, the report is designed to function as a living reference for ongoing strategic planning. By synthesizing historical performance, forward-looking projections, and the latest regulatory and product developments into a single analytical framework, the study equips decision-makers with the contextual depth required to move from reactive market monitoring to proactive strategy formulation.
Helicopter Simulator Market
Regulatory Catalysts and the Reconfiguration of Market Dynamics
The regulatory environment has emerged as one of the most consequential drivers of market evolution. Recent policy developments across major aviation jurisdictions are systematically reducing the friction that historically constrained gyrocopter commercialization. In December 2025, the European Union Aviation Safety Agency issued ED Decision 2025/022/R, which introduced updated flight crew licensing requirements for private pilot licenses under a newly defined air mobility category specifically tailored to gyrocopters. This regulatory clarification is significant because it streamlines the pathway for pilot certification, reduces ambiguity around operational eligibility, and aligns gyroplane training with broader light aviation mobility frameworks. For manufacturers and training organizations, the decision expands the addressable base of qualified pilots and strengthens the commercial case for scaled deployment.
On the other side of the Atlantic, the Federal Aviation Administration’s July 2025 modernization of Special Airworthiness Certification rules amended the regulatory framework governing the manufacture, certification, operation, maintenance, and alteration of light-sport aircraft, with explicit inclusion of gyrocopters. This update is expected to enhance procedural clarity for builders and operators, reduce compliance uncertainty, and facilitate more predictable certification timelines. Together, these regulatory shifts are not merely administrative adjustments; they are structural enablers that lower barriers to commercial adoption and encourage more disciplined investment in product development, service infrastructure, and operational scaling. The cumulative effect is a market environment in which certification competence, rather than novelty, becomes the primary differentiator.
Beyond jurisdictional rule-making, certification milestones at the manufacturer level are further reshaping competitive dynamics. Leading producers have increasingly pursued dual certification pathways that bridge recreational and commercial operational categories, enabling aircraft to be deployed across a broader set of use cases. The pursuit of recognized airworthiness standards, including alignment with ASTM and EASA frameworks, has become a strategic imperative for companies seeking to validate product credibility, expand market access, and support operators who require regulatory certainty for commercial deployment. These certification developments are not isolated technical achievements; they are market signals that indicate where the industry is heading and which capability sets will be most valuable in the years ahead.
Competitive Architecture and the Battle for Positioning
The competitive landscape is defined by a concentrated but strategically diverse set of manufacturers, each pursuing distinct positioning strategies across performance, certification, regional presence, and application focus. Market concentration metrics indicate a notably fragmented top tier, with the top three participants collectively holding approximately 25.5 percent of revenue and the top five reaching roughly 32.4 percent. This distribution suggests a market in which no single entity exerts dominant control, leaving substantial room for differentiated positioning, regional specialization, and application-specific innovation.
AutoGyro, headquartered in Friedrichshafen, Germany, remains the largest gyrocopter manufacturer globally and has built its reputation on a broad portfolio that includes the MTOsport, Cavalon, Calidus, and related models. With over 2,000 aircraft delivered worldwide, the company’s strategic advantage lies in its comprehensive certification footprint, spanning UK BCAR Section T, ASTM, EASA Part 27, and FAA Primary Category approvals. This multi-jurisdictional certification capability positions AutoGyro to serve both recreational and commercially oriented operators, while its ongoing product updates and certification refreshes signal a deliberate effort to maintain regulatory and market relevance. The company’s scale and certification breadth make it a benchmark against which competitors measure their own market-access strategies.
Magni Gyro, based in Besnate, Italy, represents a different strategic archetype. With a fifty-year heritage in ready-to-fly gyroplanes, the company emphasizes safety, reliability, and performance across both work and leisure applications. Its lineup, including the M26 Victor and M16 Extreme, reflects a focus on operational dependability and long-standing manufacturer credibility. Magni’s participation in major industry events, such as its showcase at the France Air Expo 2026 in Lyon, underscores a continued commitment to visibility, customer engagement, and product demonstration in key European markets. For buyers and partners, Magni’s value proposition centers on institutional experience and a disciplined approach to engineering and operational consistency.
ELA Aviation, operating from Córdoba, Spain, has carved out a distinct performance-oriented position. Its product range, encompassing the Business Class, Sport Line, and Professional line gyrocopters including the Eclipse EVO, REVO, and ELA-07, is associated with industry-leading short takeoff distances and high-speed certified autogyro performance. This engineering emphasis on operational efficiency and performance extremes appeals to operators who prioritize field flexibility and speed characteristics. ELA’s positioning demonstrates how product differentiation around measurable flight performance can serve as a powerful competitive lever in a market where operational utility is increasingly scrutinized.
Aviation Artur Trendak, headquartered in Jaktorów, Poland, occupies a strategically important position in the European manufacturing base. As a leading producer of piston-powered gyrocopters, its Taifun series, often paired with Rotax 916 engines, has achieved remarkable domestic market penetration, with approximately 90 percent of Polish registered gyrocopters attributed to Trendak models. The company’s side-by-side configurations for commercial and leisure applications illustrate a flexible approach to use-case design. Trendak’s dominance in its home market highlights the importance of regional manufacturing credibility, localized support ecosystems, and product familiarity in driving sustained adoption.
Airgyro Aviation, based in Utah, USA, extends the competitive field into the North American context by offering U.S.-based warranty coverage, certified gyrocopters built on Trendak-derived designs with Rotax engines, and a localized support, training, and service network outside Poland. This model reflects a strategic emphasis on reducing geographic and service barriers for North American buyers, aligning product availability with regional after-sales expectations. Airgyro’s approach illustrates how cross-border manufacturing relationships can be combined with localized service infrastructure to address market-specific procurement and operational concerns.
Beyond Unit Economics: Application Diversity and Strategic Optionality
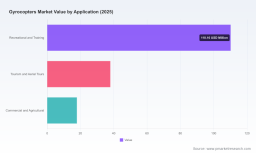
One of the most strategically significant dimensions of the market is the widening spectrum of applications across which gyrocopters are being evaluated. Demand is no longer confined to a single use case. Instead, it spans recreational and training operations, tourism and aerial tours, and commercial or agricultural deployments, each with distinct procurement drivers, regulatory considerations, and service expectations. Training and recreational demand continues to form a foundational pillar of the market, supported by evolving licensing pathways and a growing base of qualified pilots. Tourism and aerial tour operators represent a second major demand cluster, where short-field capability, low operating cost, and passenger experience considerations intersect to create viable business models in suitable geographic markets. Commercial and agricultural applications, while currently smaller in relative scale, offer some of the most compelling long-term optionality, particularly where operators seek efficient, cost-sensitive aerial platforms for specialized tasks.
The strategic implication for market participants is that application diversification is becoming a central competitive variable. Manufacturers and service providers that can align product configurations, certification profiles, and support structures with multiple application pathways will be better positioned to buffer against cyclical demand shifts and capture value across different customer segments. Conversely, strategies that remain overly dependent on a single application vertical may face greater exposure to regulatory, economic, or operational disruptions. Our report examines these application dynamics in detail, helping executives understand where demand is most structurally supported, where marginal growth is likely to emerge, and how competitive positioning should adapt to capture cross-application opportunities.
Report Scope: The Operational Intelligence You Will Gain
This study is structured to deliver actionable intelligence rather than abstract market commentary. It provides a comprehensive assessment of market sizing, growth trajectories, and the structural factors shaping demand across the 2026 to 2032 forecast period. The analysis integrates historical performance data from 2020 through 2025 with forward-looking projections, enabling leadership teams to benchmark past trends against anticipated market evolution. Beyond aggregate sizing, the report examines how competitive forces, regulatory developments, and application-level demand are interacting to shape procurement behavior and market access strategies.
Readers will gain a clear understanding of the competitive architecture, including manufacturer positioning, certification strategies, regional presence, and the extent to which market concentration is influencing pricing, service expectations, and product differentiation. The study also explores the regulatory catalysts currently reconfiguring the operating environment, translating policy updates into practical implications for product planning, certification investment, and commercial deployment. Importantly, the analysis is designed to support scenario-based strategic planning. Executives can use the framework to evaluate market entry timing, partnership structures, regional expansion priorities, and product-roadmap alignment with emerging demand patterns. The report is intended to serve as a decision-support instrument for executives who need to move from high-level market awareness to precisely calibrated strategic action.
Why 2026 Is the Right Moment to Act
The convergence of regulatory clarity, certification maturation, application diversification, and sustained revenue growth makes 2026 a strategically sensitive year for gyrocopter market participants. Companies that delay strategic positioning until the market’s growth trajectory becomes unmistakably obvious will likely face higher entry costs, tighter competitive windows, and reduced flexibility in supplier and partnership selection. Those that act now can shape their market presence proactively, aligning product offerings, service capabilities, and compliance investments with the structural trends that will define the next several years of industry development.
Gyrocopters Market
Our full market research report provides the depth, granularity, and strategic framing required to make those decisions with confidence. It is built for executives who require more than headline figures and generic growth narratives. If your objective is to understand where value is being created, which competitive capabilities matter most, and how to structure your approach for the 2026 through 2032 window, the complete study offers the comprehensive intelligence necessary to move forward with precision. We invite you to access the full report to explore the detailed segmentation, regional breakdowns, competitive assessments, and forward-looking scenario analysis that will support your next strategic move.
For detailed analysis of this topic, please visit the official page: Gyrocopters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


