



PW Consulting: Marine Propulsion Engines Market Hits $152M in 2025, Forecast 4.37% CAGR to 2032

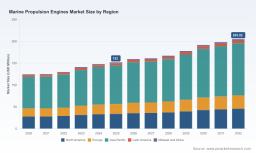
Navigating the Currents: Strategic Imperatives in the Marine Propulsion Engines Market (2026–2032)
The marine propulsion engines sector stands at a critical inflection point. As global shipping networks recalibrate around efficiency mandates, decarbonization timelines, and shifting trade corridors, engine original equipment manufacturers, vessel integrators, and procurement leaders face a complex landscape of technological transition and regulatory pressure. PW Consulting’s latest market research on the Marine Propulsion Engines Market translates this complexity into a structured, decision-ready intelligence framework. For executives charting capital allocation, product development roadmaps, or regional expansion strategies in 2026, the study offers more than retrospective tracking—it delivers a forward-looking architecture for evaluating where value will compound over the next seven years.
Drawing on a six-year historical baseline and an eight-year forward projection, the analysis establishes a clear growth trajectory for the sector. The global market surpassed the 150-billion threshold in the base year, with incremental expansion reflecting steady fleet modernization, replacement-cycle demand, and intensifying competition among tier-one propulsion suppliers. The forecast window through 2032 underscores a sustained, mid-single-digit compound annual growth rate, signaling that the industry’s expansion will be driven less by intermittent commodity spikes and more by structural shifts in hull design, fuel readiness, and emissions-compliance engineering. For strategists, this baseline is not merely a top-line figure; it is the foundation for scenario modeling, capacity planning, and partnership prioritization.
What the Research Delivers: A Decision-First Intelligence Architecture
Heavy marine equipment markets rarely yield to surface-level trend summaries. Procurement cycles span years, certification pathways are jurisdiction-specific, and competitive positioning hinges on after-sales service networks as much as on core engine performance. The PW Consulting study is designed to compress that complexity into actionable clarity. The report integrates revenue tracking, technology segmentation, regional demand mapping, and competitive profiling into a unified analytical model that responds directly to the questions fleet operators, engine manufacturers, and investment committees are asking in 2026.
Readers will find a multi-layered segmentation framework that isolates how propulsion architectures are evolving across commercial, defense, and specialized operational profiles. The analysis maps the relative weight of traditional diesel platforms against emerging hybrid configurations and gas turbine applications, providing a structured view of where incumbents are protecting share and where new entrants are carving out niches. Rather than presenting segmentation as a static snapshot, the study contextualizes it within regulatory timelines, fuel-infrastructure readiness, and vessel-class adoption patterns, enabling readers to anticipate which propulsion pathways will gain commercial traction in specific operational environments.
At the operational level, the report dissects the market into practical components that decision-makers can immediately integrate into planning cycles. These include demand-driver analysis, constraint mapping, supplier capability benchmarking, and distribution-channel assessment. Each component is tied back to the broader market mechanics, ensuring that tactical insights—such as where replacement demand is concentrated, how re-powering cycles influence engine specifications, or which vessel classes are most sensitive to fuel and emission cost shifts—are anchored in a defensible macro framework. The result is a reference document that supports both strategic foresight and near-term execution.
Competitive Positioning and the 2026 Innovation Cycle
The competitive landscape in marine propulsion is defined by a blend of global scale players, regional specialists, and technology-focused innovators. PW Consulting’s research profiles the enterprises shaping this environment, examining how their product portfolios, geographic footprints, and certification strategies position them within current demand channels. The analysis captures a market structure that is moderately concentrated, with leading players occupying distinct lanes across commercial shipping, workboat operations, recreational segments, and defense applications. This concentration pattern matters: it signals where pricing resilience is likely to persist, where service-network advantages translate into share protection, and where integrator relationships can become decisive differentiators.
Several profiled manufacturers illustrate the breadth of strategic motion currently reshaping the sector. Cummins continues to broaden its variable-speed propulsion portfolio, with recent visibility around market-ready marine diesel engines tailored for commercial, government, and recreational deployments across the Asia Pacific region. Volvo Penta is extending its inboard diesel, hybrid IPS, and outboard motor offerings across a wide model range, while also preparing to introduce next-generation hybrid yacht propulsion systems that align with growing operator interest in efficiency and operational flexibility. Perkins Engines has moved new compact marine diesel series into distributor channels, reinforcing its position in new-build and re-power applications with certified engine lines designed for marine classification requirements.
On the heavy-duty and large-vessel side, Caterpillar Marine supplies commercial propulsion engines, high-performance options, and generator sets for offshore and demanding marine settings, while MAN Energy Solutions maintains a full engine program for commercial shipping with a strong emphasis on emission-compliant variants. Rolls-Royce Marine contributes mtu Series 4000 platforms certified for commercial vessels, emphasizing extended overhaul intervals that matter for total-cost-of-ownership calculations. ABC Engines targets medium-speed propulsion and auxiliary gensets for heavy-duty commercial and workboat applications, with active exhibition and catalog activity reinforcing its focus on tugboat and specialized vessel segments. Weichai Group and Yanmar continue to serve commercial and recreational channels with certified diesel platforms, the latter demonstrating alignment with stringent regional emission standards. Hanwha Engine rounds out the competitive picture with a focus on low-speed, large-vessel propulsion and a clear orientation toward dual-fuel and methanol-enabled systems—reflecting the broader industry pivot toward future-ready fuel pathways.
Beyond portfolio descriptions, the research connects these company-level moves to the 2026 innovation cycle. Recent showcases, launches, distributor rollouts, and technical exhibitions are treated not as isolated news items but as signals of where engineering emphasis is shifting. Hybridization, certification readiness for stricter regional standards, and dual-fuel preparedness are emerging as recurring themes. For strategists evaluating partnership opportunities or competitive threats, the report provides the context needed to distinguish short-term marketing momentum from durable capability advantages.
Regulatory Pressure, Input Costs, and the Forces Shaping Demand
No marine propulsion strategy is complete without a clear view of the external forces that will compress margins, accelerate adoption, or redirect investment. The market research situates the sector within a dense regulatory and input-cost environment that is already influencing engineering choices and procurement timing. In several jurisdictions, vessels with keels laid on or after early 2026 face tighter nitrogen oxide and sulfur limits within designated emission control areas, raising the compliance bar for newbuilds and major refits alike. At the same time, specific marine engine families have been listed under recognized Tier 4 and Tier 3 certification frameworks, reinforcing the operational importance of emissions-compliant propulsion in both commercial and recreational channels.
These regulatory shifts interact directly with technology selection. Operators evaluating hull systems, engine specifications, and fuel strategies must now weigh compliance exposure alongside performance and lifecycle cost. The study maps how certification pathways, regional enforcement patterns, and fuel-availability assumptions create different demand profiles across vessel classes and geographies. For engine suppliers, this environment rewards platforms that can demonstrate compliance without sacrificing serviceability or total-cost efficiency. For fleet buyers, it elevates the importance of forward-looking specification decisions that avoid stranded assets as standards tighten.
On the cost side, the research accounts for input volatility that affects manufacturing economics across the value chain. Fluctuations in steel and aluminum prices have direct implications for engine casings, structural components, and ancillary hardware. In a market where competitive positioning increasingly depends on reliability, fuel efficiency, and after-sales support, material-cost pressure can influence not only margins but also the pace at which suppliers can invest in next-generation platforms. PW Consulting integrates these dynamics into a broader assessment of market constraints and enablers, helping readers understand where pricing power will be contested and where operational efficiency will determine share retention.
Marine Propulsion Engines Market
How to Use This Intelligence for 2026 Decision-Making
The strategic value of this research lies in its applicability across multiple decision contexts. For engine manufacturers and technology developers, the study supports portfolio prioritization by identifying where emission-compliant diesel platforms remain dominant, where hybrid and alternative-fuel pathways are gaining serious consideration, and how regional certification timelines shape product introductions. For vessel integrators and fleet operators, it provides a basis for evaluating re-powering cycles, total-cost-of-ownership trade-offs, and specification choices that balance near-term compliance with long-term fuel flexibility. For investors and corporate development teams, the analysis offers a structured view of competitive concentration, geographic demand distribution, and the operational factors that separate durable market positions from transient momentum.
Because the marine propulsion sector is shaped by long procurement cycles and high switching costs, early and well-grounded decision-making carries disproportionate value. The PW Consulting report is designed to reduce ambiguity in exactly those areas where uncertainty is most expensive: technology adoption timing, compliance-driven specification changes, regional demand shifts, and the competitive implications of recent manufacturer activity. By pairing macro trajectory with granular operational context, the study enables leaders to test assumptions, benchmark positioning, and align strategy with the market’s actual mechanics rather than surface narratives.
The complete intelligence package extends well beyond the synthesis presented here. Detailed segmentation breakdowns, regional demand mapping, company capability assessment, regulatory-timeline implications, and scenario-sensitive forecast ranges are available in the full report. For teams preparing 2026 investment decisions, product plans, or market-entry evaluations, the complete dataset provides the depth required to move from directional understanding to precise execution. Readers seeking the full analytical foundation are invited to access the complete Marine Propulsion Engines Market research on the PW Consulting source page, where the full segmentation detail, competitive profiles, and forward projections can be reviewed in context.
Marine Propeller Market
For detailed analysis of this topic, please visit the official page: Marine Propulsion Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


