



PW Consulting: Dump Trucks Market Hits $5.3B in 2025, Poised for 6.0% CAGR Through 2032

Navigating the Tides of Heavy Haulage: Strategic Insights for the Mining Dump Trucks Market (2026-2032)
The global mining dump trucks market stands at a critical inflection point. As we move into 2026, the convergence of operational efficiency demands, decarbonization mandates, and shifting geopolitical resource strategies is redefining the heavy-duty hauling landscape. For executives, investors, and strategic planners in the mining and construction machinery sectors, understanding the trajectory of this segment is not merely about tracking equipment sales; it is about anticipating the backbone of global material transport infrastructure. This article serves as a strategic primer, drawing from our latest comprehensive market research to outline the macro-economic forces, competitive dynamics, and technological disruptions that will define the forecast period from 2026 to 2032.
Our recent analysis indicates that the market is poised for steady expansion, driven by sustained commodity prices and the need to replace aging fleets with higher-capacity, more efficient machinery. However, beneath the surface of aggregate growth lies a complex web of segmentation, regional variance, and intensifying competition. This overview highlights the strategic value embedded in our full report, offering decision-makers a glimpse into the depth of intelligence available to navigate the coming years.
Electric Dump Truck Market
Macro-Economic Trajectory: Growth Drivers and Forecast Horizon
The financial backbone of the mining dump trucks sector demonstrates resilience. According to our latest data, the overall market revenue, denominated in USD billions, has exhibited a consistent upward trend over the historical review period from 2020 to 2025. Starting from a baseline of 3.96 billion in 2020, the sector navigated through global supply chain disruptions and economic volatility to reach 5.3 billion by 2025. This historical performance sets a robust foundation for the forecast period extending through 2032.
Projecting forward, the market is expected to expand from approximately 5.79 billion in 2026 to 7.97 billion by 2032. This trajectory corresponds to a Compound Annual Growth Rate (CAGR) of roughly 6.0 percent over the forecast horizon. For strategic planners, this suggests that while the market is mature, it is far from stagnant. Growth is being fueled by increased mining output in key resource-rich regions, the modernization of older haulage systems, and the introduction of trucks with higher payload capacities that reduce the total number of trips required per ton of material moved.
Mining Dump Trucks Market
It is crucial for stakeholders to recognize that these headline numbers represent the aggregate value of a highly specialized ecosystem. The revenue streams are not uniform across all equipment types or end-use applications. Understanding where the value is generated requires a granular examination of the product mix and the specific operational contexts in which these machines are deployed. Our full report dissects these layers to reveal which segments are outpacing the average growth rate and which are facing headwinds.
Market Segmentation: The Strategic Divide
The structure of the mining dump trucks market is defined by distinct categorical splits that influence procurement strategies and capital expenditure decisions. Our analysis categorizes the market primarily by vehicle type, application, and geographic region. Each division carries unique implications for manufacturers and mining companies alike.
Type and Application Dynamics
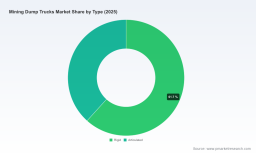
In terms of vehicle architecture, the market is split between rigid and articulated configurations. Rigid dump trucks dominate the landscape for large-scale surface mining due to their durability and load-bearing capacity, while articulated models remain essential for terrains requiring greater maneuverability, such as quarrying and certain underground operations. The balance between these two types is shifting slightly as mining sites become larger and more mechanized, favoring rigid haulers for primary haulage routes.
Application-wise, the demand is heavily skewed toward open-pit metal mining, which remains the primary driver of heavy haulage volume. Coal and lignite mining continues to be a significant segment, although its growth trajectory is influenced by regional energy transition policies. Meanwhile, quarrying and aggregates represent a steady, albeit smaller, portion of the market, driven by infrastructure development demands. The interplay between these applications dictates the specifications required by OEMs, from engine power to ground pressure and mobility features.
Regional Landscape
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific currently commands a substantial share of the market volume, reflecting the region's intensive mining activities and infrastructure investments. North America and Europe follow, with mature markets focused on fleet renewal and efficiency upgrades. The Latin America and Middle East and Africa regions offer emerging opportunities tied to specific resource discoveries and operational expansions. However, the relative weight of each region fluctuates based on commodity cycles and regulatory environments.
Detailed breakdowns of these segments, including precise revenue contributions and growth rates for each category, are critical for target market analysis. Our complete study provides the specific split values necessary for accurate regional and segment-level forecasting, enabling clients to allocate resources where the return on investment is highest.
Competitive Landscape: Concentration and Key Players
The mining dump trucks market is characterized by a high degree of concentration, which has significant implications for pricing power, innovation cycles, and supply chain resilience. Our research highlights a market environment where a select group of established giants controls a vast majority of the share. The top three companies collectively hold a CR3 of approximately 65 percent, while the top five expand this concentration to 85 percent. This oligopolistic structure suggests that market entry barriers are high, and competitive advantage is derived from technological differentiation, service networks, and total cost of ownership (TCO) performance rather than price competition alone.
Profiles of Dominant Forces
Several key companies define the competitive arena, each with distinct strategic positions:
- Caterpillar Inc. (Peoria, Illinois, USA): A perennial leader, Caterpillar continues to set the benchmark with its off-highway and mining dump trucks. Their Cat series, including the iconic 797F, exemplifies rugged engineering designed for heavy-duty hauling in the most demanding mining environments. Their strength lies in a comprehensive global service network and a reputation for reliability.
- Komatsu Ltd. (Tokyo, Japan): Komatsu is heavily invested in electrification and efficiency. Their electric drive mining trucks, such as the 930E-5 and 980E series, are tailored for large-scale open-pit operations. The company is also pushing the boundaries of alternative propulsion technologies.
- Hitachi Construction Machinery Co., Ltd. (Tokyo, Japan): Focusing on rigid dump trucks like the EH AC-5 series, Hitachi supports large-scale mining resource transport. They are expanding their manufacturing footprint, with decisions to begin full-scale production of dump trucks at specific facilities during the forecast period, signaling capacity growth.
- BelAZ (Zhodino, Belarus): As one of the world's largest manufacturers of heavy-duty mining dump trucks, BelAZ is known for massive payload capacity. Their 75710 series represents the upper echelon of haulage capability, serving operations that require moving immense volumes of ore.
- Volvo Construction Equipment AB (Gothenburg, Sweden): Volvo offers a mix of rigid haulers and articulated dump trucks. Notably, their strategy is evolving; recent announcements indicate a shift in focus toward rigid hauler innovation, with plans to close certain articulated hauler business lines to streamline their portfolio.
- Liebherr-International AG (Bulle, Switzerland): Liebherr serves high-payload hauling needs with series like the T 264, T 274, and T 282. They are actively integrating advanced systems into their diesel-electric trucks, including trolley-assist technologies that improve efficiency on specific mine routes.
- XCMG Group (Xuzhou, Jiangsu, China): XCMG is expanding its footprint with off-highway wide-body and electric drive dump trucks. Their XDE series targets open-pit mining, and recent deliveries in Oceania highlight their growing international reach.
- SANY Group (Changsha, Hunan, China): SANY provides off-highway mining trucks, including their SKT and SRT series. They compete in both wide-body and articulated applications, leveraging China's manufacturing scale to offer competitive solutions.
- Terex Corporation (Norwalk, Connecticut, USA): Through its Terex Trucks brand, the company focuses on rigid dump trucks built for tough mining conditions, emphasizing durability and flexibility.
- GHH Group GmbH (Germany): GHH specializes in articulated dump trucks for underground mining and tunneling, addressing niche but critical operational needs where space and maneuverability are paramount.
The strategic interactions between these players, including potential partnerships, product launches, and market share shifts, are analyzed in depth within our report. Understanding the specific offerings and strategic moves of each competitor is essential for positioning new products or assessing supplier risk.
Industry Dynamics: Technology, Regulation, and Strategic Shifts
The period from 2026 to 2032 will be defined by rapid technological evolution and regulatory pressure, particularly regarding emissions and operational efficiency. Several recent developments underscore the direction of the industry:
- Electrification and Alternative Fuels: The push for decarbonization is accelerating. Komatsu initiated proof-of-concept tests in early 2025 for the world's first large dump truck equipped with a hydrogen combustion engine, signaling a potential future beyond diesel-electric and battery-electric solutions. This highlights the experimentation phase occurring across the sector.
- Trolley-Assist and Efficiency Systems: Liebherr delivered a new generation of diesel-electric mining haul trucks equipped with trolley-assist systems to Collahuasi mine operations in early 2026. Such technologies allow trucks to draw power from overhead lines on gradients, significantly reducing fuel consumption and emissions during high-load segments of the haul cycle.
- Production and Portfolio Adjustments: Hitachi Construction Machinery decided to begin full-scale production of dump trucks in fiscal year 2026 at its dedicated manufacturing facility, expanding its capacity and market presence. Conversely, Volvo CE announced plans to close its Rokbak articulated hauler business by Q3 2026, redirecting focus to rigid hauler innovation. This indicates a strategic consolidation where companies are exiting segments that do not align with their core competencies or future technology roadmaps.
- Global Supply and Delivery: XCMG Group delivered a batch of XDE260 double-bridge rigid dump trucks for open-pit mine operations in Oceania in late 2024. This exemplifies the increasing competitiveness of non-traditional major players expanding into key markets outside their home regions.
These dynamics illustrate that the market is not static. Regulatory frameworks in various jurisdictions are tightening regarding particulate matter and greenhouse gas emissions, forcing manufacturers to innovate. Simultaneously, mining companies are under pressure to reduce their carbon footprints, creating demand for trucks that can operate with lower specific fuel consumption or alternative energy sources. Our report evaluates how these factors influence procurement cycles, total cost of ownership calculations, and long-term fleet planning.
Strategic Implications for 2026 Decision-Makers
For executives and strategic planners, the data points and dynamics outlined above point to several key considerations for 2026 and beyond. First, the high market concentration suggests that supply chain security and long-term service agreements with major OEMs are critical. Relying on a narrow supplier base carries risk, but the dominance of top players also ensures a level of technological sophistication and support infrastructure that smaller vendors may struggle to match.
Second, the growth trajectory of 6.0 percent CAGR should not be interpreted as a uniform opportunity. The value is unevenly distributed. Segments aligned with metal mining and regions with active infrastructure and mining projects will likely outperform others. Procurement strategies must be segmented accordingly, balancing the need for high-capacity rigid trucks for primary haulage with articulated solutions for secondary or complex terrain tasks.
Third, technology adoption is becoming a differentiator. The moves toward hydrogen combustion, trolley-assist, and electric drive systems are not just regulatory compliance measures; they are potential sources of operational cost savings and competitive advantage for mining companies. However, the right technology depends on the specific mine layout, gradient, and logistics. A generalized approach will not suffice.
Our full market research report provides the detailed intelligence required to act on these insights. It offers precise segmentation data, competitive benchmarking, and scenario analysis that allows organizations to model the impact of different strategic choices. From detailed revenue splits by type and application to region-specific growth forecasts, the report is designed to support capital allocation, product development, and market entry decisions with confidence.
In an industry where equipment lifecycles are long and capital investments are substantial, foresight is a valuable asset. The mining dump trucks market of 2032 will look different from that of 2026, shaped by the strategic decisions made today. We invite stakeholders to delve deeper into our findings to secure a comprehensive understanding of the opportunities and challenges ahead.
For detailed analysis of this topic, please visit the official page: Mining Dump Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


