



PW Consulting: Polyacrylonitrile Market to Reach $9.59B in 2032 at 3.3% CAGR

Strategic Imperatives in the Global Polyacrylonitrile Market: Navigating Growth, Volatility, and Competitive Consolidation
The polyacrylonitrile (PAN) market stands at a critical inflection point where traditional textile demand intersects with rapidly expanding advanced materials applications. For corporate strategists, procurement leaders, and investment committees operating in 2026, understanding the nuanced trajectory of this sector is no longer optional-it is a prerequisite for resilient supply chain design, capacity planning, and competitive positioning. The latest PW Consulting market research on polyacrylonitrile provides a comprehensive, data-grounded roadmap through this complex landscape, translating historical performance and forward-looking projections into actionable intelligence. This analysis draws exclusively from proprietary modeling and primary industry engagement to equip decision-makers with the clarity required to navigate raw material volatility, regulatory pressure, and accelerating technological substitution.
Market Trajectory and Structural Evolution
Historical performance from 2020 through 2025 reveals a market characterized by steady expansion punctuated by periodic supply disruptions and input cost fluctuations. Revenue progression across this six-year window demonstrates a consistent upward trajectory, with total global market value crossing the seven-billion-dollar threshold and stabilizing at approximately 7,545 million by the end of 2025. This foundational baseline establishes the starting point for the current forecast cycle, which projects continued expansion through 2032. The medium-term outlook anticipates the market scaling to nearly 8,000 million in 2026, followed by sustained growth that pushes valuations toward the mid- to upper-nine-billion range by the end of the decade.
The central growth catalyst across the forecast horizon is a compound annual growth rate of 3.3 percent. While this figure may appear moderate on the surface, its strategic significance lies in the underlying composition of demand drivers. Growth is not uniformly distributed across all application verticals; rather, it is increasingly concentrated in high-performance precursor segments and specialized filtration grades, while traditional textile volumes face margin compression and regional demand oscillations. The trajectory also reflects a market that has matured past its early expansion phase, entering a period where efficiency, formulation optimization, and supply chain integration become the primary differentiators. Companies that fail to align capacity investments with these shifting demand centers risk exposure to overcapacity in legacy segments and underinvestment in high-margin precursor pathways.
Temporal demand modeling within the research framework further highlights the importance of scenario planning. The projected sequence of annual valuations through 2032 illustrates a market that does not grow in a straight line but rather responds dynamically to macroeconomic cycles, feedstock pricing, and regulatory implementation timelines. Decision-makers who rely on single-point forecasts are particularly vulnerable to misallocated capital and misaligned inventory strategies. Our analysis emphasizes dynamic range modeling and stress-testing against input cost shocks, ensuring that strategic plans remain viable across multiple plausible futures.
Demand Architecture and Segment Interplay
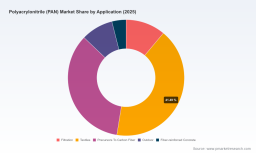
The structural composition of PAN demand is fundamentally bifurcated between conventional textile applications and advanced industrial precursors. Traditional acrylic staple fiber and tow grades continue to command substantial volume, driven by apparel, home textiles, and industrial fabric markets. However, the growth narrative is increasingly anchored in specialized applications where PAN serves as a critical enabler of next-generation materials. Precursor-to-carbon-fiber grades represent a growing share of total market value, supported by sustained aerospace build rates, automotive lightweighting mandates, and expanding wind energy compounding requirements.
Filtration applications present another distinct demand node, leveraging PAN's chemical resistance and thermal stability for industrial liquid and gas processing environments. Meanwhile, outdoor and fiber-reinforced concrete applications, though smaller in aggregate volume, demonstrate specialized growth trajectories tied to infrastructure modernization and durability requirements in harsh environmental conditions. The interplay between these segments creates a complex demand matrix where volume shifts in one vertical can rapidly translate into pricing and capacity adjustments across the broader value chain.
From a segmentation perspective, the market exhibits clear structural boundaries across geographic distribution, product typology, and end-use application. Regional demand concentration reflects established manufacturing footprints and localized downstream processing capabilities, while product-type splits highlight the divergence between staple fiber production, tow intermediates, and top-grade specialty formulations. Application-level demand patterns further underscore the transition from commodity-driven consumption toward performance-specified procurement. These structural splits are not static; they evolve in response to capacity additions, trade flow adjustments, and regional compliance mandates. The research framework captures these dynamics through granular modeling that tracks how shifts in one segment propagate through the broader market equilibrium.
Competitive Landscape and Strategic Consolidation
The competitive architecture of the PAN market is defined by a concentrated yet geographically diverse participant base. Market concentration metrics indicate that the top three players collectively command approximately 26 percent of total revenue, while the top five extend their combined share to roughly 30 percent. This moderate concentration level suggests that while scale advantages exist, the market remains sufficiently fragmented to allow specialist players to compete on formulation quality, regional integration, and customer-specific precursor engineering.
Polyacrylonitrile (PAN) Market
The participant landscape spans integrated chemical manufacturers, fiber specialists, and advanced materials conglomerates. Turkish producers have reinforced their regional positioning through ownership restructuring and vertical integration, most notably through the acquisition of remaining equity stakes in joint carbon fiber ventures and the subsequent rebranding of operations to unify precursor and fiber production under a single corporate identity. This move illustrates a broader industry trend toward tighter integration between PAN precursor supply and downstream carbon fiber processing, reducing transactional friction and improving formulation consistency.
European manufacturers continue to emphasize dry-spun fiber technologies and specialized PAN grades tailored for both textile and precursor applications, leveraging established process engineering capabilities and strong compliance infrastructure. In East Asia, major chemical and composite companies maintain significant production footprints, with some operating fully integrated polymerization, spinning, and precursor oxidation workflows under proprietary brand architectures. These vertically aligned operations provide distinct advantages in cost structure, quality control, and supply reliability for aerospace and industrial composite customers. South Korean and Taiwanese participants similarly contribute meaningful capacity, with several firms expanding precursor-grade production to support domestic and export-oriented carbon fiber manufacturing. Japanese specialty chemical suppliers add further depth to the competitive field, focusing on advanced composite precursor grades and collaborative development with end-user composite fabricators.
Recent strategic activity reinforces the consolidation and integration narrative. Ownership transitions, exhibition showcases, and industry day participations have collectively signaled a market preparing for heightened scrutiny around circularity, precursor efficiency, and application-specific performance validation. These developments are not isolated; they reflect a coordinated push by leading participants to align PAN production capabilities with evolving downstream specifications, particularly in carbon fiber precursor markets where consistency, oxidation behavior, and impurity control directly determine final composite performance.
Operating Environment Pressures and Risk Factors
Beyond structural demand and competitive positioning, the PAN operating environment is shaped by persistent input cost volatility, regulatory compliance burdens, and supply chain fragility. Acrylonitrile remains the dominant cost component in PAN manufacturing, representing roughly two-thirds of total production expenses. Price movements in this feedstock therefore transmit rapidly into producer margins, pricing strategies, and end-customer negotiations. Recent quarters have demonstrated sustained elevation in global acrylonitrile pricing, with early-2026 increases largely attributed to rising propylene feedstock costs. In specific regional markets, price surges have been more pronounced, driven by inventory drawdowns and tighter availability of both propylene and ammonia, the upstream inputs that dictate acrylonitrile production economics.
These raw material pressures are compounded by regulatory dynamics. Environmental compliance requirements governing acrylonitrile production in the European Union have increased operational costs for PAN producers, adding a measurable compliance premium to European manufacturing footprints. Such regulatory shifts do not merely affect cost structures; they influence location decisions, capacity expansion timelines, and the competitive balance between regions with differing compliance regimes. Producers with integrated feedstock access, advanced process efficiency, or flexible sourcing strategies are better positioned to absorb these incremental costs without compromising margin targets.
Supply chain resilience has also emerged as a critical operational theme. Historical production disruptions linked to raw material shortages in key manufacturing regions have demonstrated how quickly localized feedstock constraints can cascade into broader output reductions. Facilities exposed to concentrated supplier dependence or single-region feedstock sourcing have experienced production curtailment, reinforcing the strategic importance of diversified procurement, inventory buffering, and demand-forecast alignment. The market research framework incorporates these risk vectors explicitly, enabling planners to evaluate exposure across multiple procurement scenarios and assess the financial implications of input price shocks and regulatory cost escalations.
What the Research Delivers for Decision-Makers
The PW Consulting polyacrylonitrile market study is designed to function as a practical decision-support instrument rather than a static statistical compendium. The research architecture is structured to provide strategic teams with the granularity required to evaluate capacity investments, procurement strategies, competitive positioning, and regional market entry or expansion plans. Core deliverables span multi-period market sizing, segment-level demand modeling, competitive profiling, and operating environment analysis, all calibrated to the current forecast cycle and grounded in primary data collection and proprietary analytical methods.
The report provides detailed segmentation analysis across regional distribution, product typology, and end-use application, enabling users to isolate growth centers, assess volume-to-value translation, and identify segments where margin dynamics diverge from headline growth rates. Competitive intelligence components map incumbent capabilities, strategic movements, and integration trajectories, offering context for partnership evaluation, benchmarking, and threat assessment. Operating environment sections synthesize raw material cost behavior, regulatory impact trajectories, and supply chain vulnerability indicators, equipping procurement and risk management teams with the inputs necessary to design resilient sourcing and pricing strategies.
Strategic planners will find particular value in the scenario-based modeling framework, which translates macro-level trends into actionable planning ranges. Rather than presenting a single deterministic path, the research outlines plausible demand and cost trajectories under varying macroeconomic, feedstock, and regulatory conditions. This approach supports more robust capital allocation, inventory planning, and supplier negotiation strategies. Additionally, the inclusion of recent industry developments and corporate activity timelines provides forward-looking context for interpreting competitor behavior and anticipating shifts in market participation.
Isophthalonitrile (INP) Market
Why 2026 Decisions Require Precision Intelligence
The current market environment demands a higher standard of strategic precision. Growth is real, but it is uneven. Input costs remain volatile, and regulatory costs are incrementally reshaping regional competitiveness. Competitors are consolidating, integrating, and rebranding to align precursor supply with downstream composite requirements. In this context, decisions made in 2026 will determine not only near-term margin performance but also long-term capacity relevance and supplier credibility.
Organizations that treat the polyacrylonitrile market as a static commodity sector will miss the structural shifts occurring in precursor demand, regional cost differentials, and application-specific procurement behavior. Conversely, teams that ground their planning in detailed, scenario-aware market intelligence will be better positioned to time capacity adjustments, optimize procurement contracts, identify partnership opportunities, and anticipate competitive moves before they reshape pricing and availability. The difference between reactive adaptation and proactive strategy often comes down to the quality and timeliness of the underlying intelligence.
Accessing the Full Strategic Picture
This overview captures the structural logic, competitive dynamics, and operating environment pressures that define the polyacrylonitrile market as of 2026. However, the full strategic value of the research lies in its detailed segmentation modeling, comprehensive competitive profiling, scenario-driven planning tools, and precise quantification of demand shifts across regions, product types, and applications. Core growth sensitivities, segment-level valuation trajectories, regional concentration dynamics, and competitor capability assessments are developed in depth within the complete report, providing the quantitative backbone necessary for confident capital allocation, procurement strategy design, and market positioning.
For executives, analysts, and supply chain leaders who require verified market sizing, granular segmentation breakdowns, competitive benchmarking, and forward-looking operating environment analysis, the complete PW Consulting Polyacrylonitrile Market research offers the comprehensive intelligence needed to convert complexity into clarity. Access the full report to obtain the detailed data, scenario frameworks, and strategic assessments that will inform your 2026 and beyond planning decisions.
For detailed analysis of this topic, please visit the official page: Polyacrylonitrile (PAN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


