



PW Consulting: Global Mineral Water Market to Reach $8.23 Billion by 2032, Growing at 3.2% CAGR

Strategic Intelligence for the 2026 Boardroom: Navigating the Global Mineral Water Market
As organizations calibrate their strategies for the 2026 fiscal year, the global mineral water sector stands at a complex inflection point. Long viewed as a stable consumer staples segment, the industry now faces converging pressures from regulatory recalibration, supply-chain reconfiguration, and shifting retail architectures. Decision-makers operating in beverage, retail, logistics, and private equity require more than directional commentary; they need a rigorously benchmarked, forward-looking intelligence framework that translates macro trajectories into executable positioning. The latest Mineral Water Market research deliverable from PW Consulting was designed to serve precisely that function. By bridging historical settlement patterns with a structured outlook through 2032, this analysis equips leadership teams with the analytical scaffolding necessary to time capital deployment, assess competitive vulnerabilities, and anticipate structural shifts before they become priced into the market.
A Market Maturing Into Measured Expansion
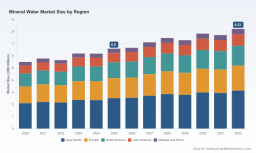
Over the review horizon of 2020 through 2025, the global mineral water revenue base demonstrated the hallmarks of a category transitioning from hyper-growth to disciplined compounding. Trailing valuations moved from approximately 5.5 billion USD in 2020 to an estimated 6.6 billion USD by 2025, with intermediate years reflecting the familiar volatility of commodity-adjacent consumer goods, supply chain adjustments, and regional demand oscillations. Rather than signaling stagnation, this pattern underscores a market that is consolidating around verified demand drivers: sustained health-conscious consumption, preference for traceable sourcing, and incremental premiumization in mature urban markets. Looking toward the forecast window of 2026 through 2032, the research projects a compound annual growth rate of approximately 3.2 percent, with revenue scaling toward an estimated 8.23 billion USD by the terminal forecast year. The implication for strategic planners is nuanced. A mid-single-digit CAGR is neither a runaway expansion narrative nor a contraction warning; it is a signal that value capture will increasingly depend on share defense, mix optimization, and operational efficiency rather than on aggregate volume tailwinds. Organizations that treat this trajectory as a backdrop for portfolio tuning, rather than a generic growth prophecy, will be better positioned to allocate marketing spend, negotiate distribution terms, and evaluate M&A targets with precision.
Regulatory Architecture and the Redefinition of Market Access
One of the most consequential themes emerging for 2026 strategy is the intensification of regulatory scrutiny across multiple jurisdictions. Standards that once functioned as baseline hygiene requirements are evolving into differentiated market-access levers, altering the cost of compliance and the speed of new-product introductions. In Europe, the latest amendment framework issued by the Irish Ministry of Health in May 2025 tightened definitions around water sampling, clarified market-entry conditions, and formalized officials’ sampling procedures for bottled and containerized waters. While the change originates within a single jurisdiction, its structural logic often influences regional harmonization debates and supplier qualification expectations across broader European supply chains. In parallel, Asia’s regulatory posture is moving toward tighter contaminant thresholds and testing discipline. Japan’s Consumer Affairs Agency proposed combined limits of 50 ng/L for PFOS and PFOA in sterilized or disinfected mineral water products, deliberately aligning bottled standards with tap water benchmarks during early 2025. Meanwhile, India’s FSSAI removed the mandatory BIS certification requirement for packaged drinking water and mineral water effective October 2024, replacing it with a new compulsory Scheme of Testing covering source water, microbiological safety, packaging, and hygiene beginning January 1, 2026. The shift illustrates a broader global pattern: regulators are less interested in blanket certification stamps and more focused on verifiable process integrity, contamination surveillance, and traceability. For corporate strategists, these developments are not merely legal footnotes. They influence plant audit cycles, supplier onboarding timelines, labeling architecture, and the risk profile of short-term capacity expansion. A market study that integrates regulatory trajectory analysis allows leadership to anticipate where compliance costs will concentrate, which product formats face heightened scrutiny, and how certification velocity could affect time-to-market for new SKUs.
Competitive Restructuring and the Strategic Signal of Recent Moves
The competitive landscape is being reshaped not only by long-term brand positioning but by discrete corporate events that reveal where incumbents see structural value, risk concentration, and portfolio fit. Several recent developments warrant close boardroom attention because they offer early indicators of sector consolidation logic and operational recalibration. Nestlé’s separation of its water and premium beverages activities into a standalone business, effective January 1, 2025, reorganized global mineral water brands into a focused entity and set the stage for a formal sale process initiated in January 2026, with the business valued at approximately 5 billion EUR. This sequence signals a strategic intention to unlock balance-sheet flexibility, sharpen category focus, and invite external capital or acquirer architectures into a legacy portfolio encompassing Perrier, San Pellegrino, Acqua Panna, Vittel, and Contrex. For competitors and potential buyers, such a process creates both opportunity and uncertainty: brand portfolios may shift ownership, distribution relationships may be renegotiated, and pricing frameworks may be reset under new ownership mandates. Coca-Cola’s recent operational actions around Topo Chico illustrate a different but equally instructive dynamic. A voluntary recall in mid-2025 involving limited quantities of carbonated Topo Chico in 16.9-ounce glass bottles, attributed to potential Pseudomonas bacterial contamination, emphasized the criticality of microbiological control and traceability in premium packaged water. Followed by a production pause in early 2026 for facility upgrades at the source and manufacturing site in Mexico, with product expected to return to shelves later in 2026, this sequence highlights how supply integrity, source-facility readiness, and brand trust are tightly coupled in the mineral water segment. Even strong global marketers must weather operational interruptions when contamination risk or infrastructure readiness is questioned. Beyond these specific events, the report profiles a focused set of category-leading enterprises including Danone, with its Evian and Volvic portfolio orientation; Nestlé Waters and its global premium still and sparkling lineup; The Coca-Cola Company’s expanding presence through Topo Chico; Fiji Water Company’s premium volcanic-source positioning; and Gerolsteiner Brunnen GmbH & Co. KG with its German sparkling and still offerings. Together, these players represent a cross-section of strategic postures: legacy European provenance, aggressive international distribution, premium brand cultivation, and regional scale advantages. The research examines how these organizations are navigating overlapping imperatives: brand trust maintenance, source protection, retail negotiation leverage, and the balance between natural mineral positioning versus man-made alternatives. The estimated revenue composition underscores this tension, with natural mineral water commanding a substantially larger revenue share than man-made variants. That structural imbalance matters for strategy. It directs attention to provenance storytelling, geological authenticity, and certification narratives, while leaving room for niche positioning around blended or processed offerings in specific price or functional segments.
Demand Pathways, Retail Rearchitecture, and Distribution Strategy
Market access in mineral water is increasingly dictated by channel evolution as much as by product characteristics. The forecast period is being shaped by the reorganization of grocery retail, the expansion of convenience-oriented purchasing, and the continued integration of digital commerce into everyday beverage procurement. Hypermarkets and supermarkets remain a dominant revenue gateway, reflecting the enduring importance of mass retail in driving repeat purchase behavior and basket placement. Yet strategic nuance lies in how this channel interacts with convenience stores, independent grocery stores, e-commerce platforms, and miscellaneous outlets. Convenience retail, in particular, continues to capture incremental impulse and on-the-go demand, while e-commerce provides a structurally smaller but strategically important route for subscription models, premium packs, and regional reach extension. For 2026 planning, the strategic question is not which channel is largest in absolute terms, but how each channel’s margin architecture, shelf dynamics, fulfillment cost, and consumer frequency profile align with a company’s brand tier and geographic footprint. A premium provenance brand may over-index on selective distribution and controlled e-commerce presentation, while a mass-positioned offering may rely more heavily on high-velocity supermarket resets and convenience visibility. The report maps these channel dynamics without reducing them to simplistic share rankings, because effective distribution strategy requires an understanding of purchase rhythm, pack-size economics, and the cost-to-serve associated with each route.
Why This Research Is Built for 2026 Decision-Making
A market study earns its place in the executive workflow when it converts data points into decision architecture. This Mineral Water Market research was constructed around that principle. It is designed not merely to describe where revenue has traveled, but to help leadership teams determine where to commit resources, what assumptions to stress-test, and which risks to structure around. The deliverable integrates several practical components that support operational planning and strategic evaluation. It provides a structured historical baseline through 2025, establishing the demand and revenue context against which the forecast period can be judged. It extends a forward view through 2032, allowing teams to model medium-term capacity, brand investment, and channel development with a common time horizon. It contextualizes regulatory developments as strategic variables rather than background noise, enabling compliance and sourcing teams to align with upcoming testing, sampling, and certification expectations. It profiles the competitive set with attention to brand architecture, recent corporate actions, and operational incidents that reveal underlying vulnerabilities or strengths. It further maps channel dynamics and product-type structure so that managers can align portfolio choices with market access realities. Most importantly, the analysis deliberately preserves the granularity necessary for actionable planning within the full report framework. Macro trajectories, concentration signals, and directional splits are presented to establish scope and credibility, while the detailed regional and application-level figures, exact revenue attributions, and scenario-level sensitivity analysis are reserved for the complete study. This structure reflects a practical reality: the executive summary builds confidence and strategic orientation, but the operational decisions around territory prioritization, pack architecture, supplier selection, and channel investment require the full analytical depth that the report is built to deliver.
Reading Concentration as a Strategic Variable
Market concentration is often treated as a static statistic, but in practice it is a strategic diagnostic. The sector’s estimated CR3 and CR5 concentration levels indicate a landscape that is competitive but not fully fragmented, suggesting that scale players command meaningful influence while still leaving substantial space for regional specialists and premium niche positioning. For a 2026 strategist, this creates a dual imperative. On one side, competing against consolidated brands requires clarity on differentiation: source authenticity, packaging distinction, sustainability storytelling, and channel-specific value propositions. On the other side, the presence of meaningful headroom below the top tier means that targeted regional plays, private-label partnerships, and specialized distribution agreements can still generate attractive returns if they are matched to the right local demand patterns and compliance conditions. Concentration data therefore functions as a map of where to defend, where to attack, and where to avoid direct confrontation until a superior cost or brand position is established.
From Insight to Action: How to Use the Outlook in 2026
Strategists can translate this market outlook into near-term action across several dimensions. First, portfolio reviews should account for the reality that aggregate growth is moderate, meaning that revenue improvement will likely come from mix, pricing precision, and channel optimization rather than from waiting for market-wide expansion. Second, supply-chain and quality assurance planning should incorporate the regulatory direction observed across Europe, Japan, and India, especially the movement toward more rigorous testing, contamination monitoring, and sampling discipline. Third, corporate development teams should monitor ownership transitions and operational adjustments among leading players, since portfolio sales, production pauses, and recall episodes can alter distribution leverage and shelf availability within a single fiscal year. Fourth, brand and communications planning should recognize the structural preference for natural mineral positioning, using provenance, source integrity, and certification narratives as strategic assets rather than optional branding elements. Finally, channel strategy should be calibrated to each route’s economic profile, with deliberate choices about which formats, pack sizes, and fulfillment models fit supermarket velocity, convenience visibility, grocery selectivity, and e-commerce subscription potential.
Conclusion: A Deliberate Market Deserving Deliberate Strategy
The mineral water market entering 2026 is best understood as a category in disciplined evolution. It is large enough to matter for portfolio strategy, dynamic enough to reward those who monitor regulatory and competitive signals early, and concentrated enough to demand clear differentiation rather than undifferentiated scale play. With revenue projected to move from an estimated 6.67 billion USD in 2026 toward an estimated 8.23 billion USD by 2032 at a compound annual growth rate of roughly 3.2 percent, the sector offers steady but procurement-sensitive expansion for organizations prepared to treat it as a strategic platform rather than a passive cash category. The full Mineral Water Market research from PW Consulting provides the detailed segmentation, regional and application-level revenue intelligence, company-specific strategic profiling, and regulatory mapping required to convert this high-level orientation into a concrete 2026 action plan. For executive teams seeking to align capital allocation, brand strategy, supply integrity, and channel execution with the realities of the next forecast cycle, the complete report offers the level of proprietary detail and scenario-ready structure that boardroom decisions demand.
Mineral Water Market
Coconut Water Market
For detailed analysis of this topic, please visit the official page: Mineral Water Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


