



PW Consulting: Blood Purification Equipment Market Hits $15.5B in 2025, Projected to Reach $22.55B by 2032

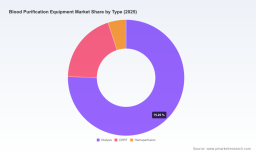
Strategic Intelligence for the Blood Purification Equipment Market: Navigating 2026 and Beyond
The global blood purification equipment market stands at a critical inflection point heading into 2026. For executives, investors, and clinical leaders, the choice is no longer whether to monitor this space, but how to extract actionable intelligence from a landscape defined by shifting regulatory frameworks, evolving reimbursement structures, and accelerating technological differentiation. PW Consulting's latest market research on Blood Purification Equipment delivers precisely that intelligence. This report is designed to serve as a foundational strategic asset for decision-makers who require more than surface-level trends. It provides a rigorous, data-grounded view of where the market has been, where it is heading, and how to position organizations to capture value across the forecast horizon.
The market's trajectory over the past half-decade tells a story of resilience and structural growth. Valued at approximately 13,000 million USD in 2020, the industry navigated a period of fluctuation before reestablishing a clear upward path. By 2023, valuation had climbed to roughly 14,500 million USD, and the momentum carried through 2024 and 2025, reaching an estimated 15,500 million USD at the close of the base year. Looking forward, our forecast models project the market will surpass the 16,000 million USD threshold in 2026, continuing through a defined 2026-2032 forecast period to reach over 22,500 million USD by the terminal year. The implied compound annual growth rate of 5.5 percent sits comfortably above broader medical device benchmarks, signaling sustained demand driven by demographic shifts, expanded clinical indications, and the modernization of care delivery models. For any enterprise operating in this domain, these figures are not abstract statistics. They represent the scale of opportunity and the urgency of strategic planning.
Why 2026 Demands a Precision Strategy
The year 2026 is not merely another data point on a growth curve. It is a year where regulatory clarity, reimbursement adjustments, and technological adoption cycles intersect in ways that will materially alter competitive dynamics. Organizations that enter 2026 relying on outdated assumptions about market segmentation, product positioning, or geographic prioritization risk misalignment at precisely the moment when capital allocation and R&D focus need to be sharpest. Our research is built to prevent that misalignment. It provides a structured framework for understanding how macro trends translate into operational realities, from procurement behavior to clinical adoption patterns.
Several dynamics underscore the strategic urgency. Regulatory authorities have refined their classifications to better address evolving device capabilities, with recent guidance establishing new controls for hemodialyzers featuring expanded solute removal profiles. Simultaneously, manufacturing standards have been tightened, including updated GMP expectations concerning equipment and detection systems for blood purification products. On the reimbursement side, state-level programs are updating coverage codes and maintenance provisions for dialysis-related equipment, directly influencing provider purchasing behavior and total cost of ownership calculations. These developments do not operate in isolation. They compound, creating a landscape where compliance, clinical efficacy, and economic viability must be evaluated together. Our report maps these interconnections explicitly, enabling leadership teams to anticipate ripple effects rather than react to them after the fact.
Inside the Report: Structure, Depth, and Strategic Utility
PW Consulting's Blood Purification Equipment market research is structured to function as both a reference document and a decision-support tool. Rather than offering a single aggregated view, the analysis is organized to allow readers to drill into the dimensions that matter most to their specific mandates. The report balances macro-level context with granular operational insights, ensuring that strategy teams, product leaders, and market access professionals can each find relevant, actionable content.
The core analytical framework examines the market across multiple axes, including product type, clinical application, and regional dynamics. For each dimension, the report traces historical performance, identifies structural drivers, and projects forward-looking trajectories. Importantly, the analysis avoids the trap of presenting segmentation as a static snapshot. Instead, it contextualizes each segment within the broader ecosystem, examining how drivers such as chronic disease prevalence, acute care requirements, and the growing emphasis on home-based and decentralized treatment models interact to shape demand. Readers will find quantified assessments of how these forces are expected to play out across the forecast period, with careful attention to the timing and magnitude of shifts that could influence purchasing patterns and product mix.
Beyond segmentation, the report includes a comprehensive competitive landscape evaluation. This section goes beyond ranking players by market share to examine how leading companies are differentiating themselves through technology, service models, geographic expansion, and regulatory strategy. The analysis captures recent product introductions, clearance milestones, and commercial rollouts that signal where incumbents and challengers are placing their bets. It also assesses the structural characteristics of the market, including concentration levels and the strategic implications of a landscape where a relatively small group of firms commands a disproportionate share of revenue. Understanding these concentration dynamics is essential for gauging pricing power, partnership opportunities, and barriers to entry.
Competitive Dynamics and the Emerging Innovation Frontier
The competitive environment in blood purification equipment is characterized by a blend of established multinational leadership and specialized innovators pushing the boundaries of what extracorporeal therapies can achieve. Long-standing players have built formidable positions through integrated portfolios that span dialysis machines, disposables, and related consumables, often supported by global service networks and deep regulatory expertise. Their scale advantages are significant, yet the market has not become dormant. Instead, it is being reshaped by companies that are targeting specific clinical needs with novel mechanisms, advanced materials, and differentiated treatment protocols.
Blood Filter Market
Recent industry activity illustrates this dual dynamic. Major incumbents have continued to advance their flagship platforms, with notable rollouts expanding the availability of high-volume hemodiafiltration systems and extending their commercial footprint across key markets. Parallel to these moves, innovators have secured important regulatory clearances that open new avenues for patient access. One prominent example involves the clearance of a dialysis system designed to support high dialysate flow across the full spectrum of end-stage renal disease care, including home use. Such developments point to a broader trend: the blurring of traditional boundaries between institutional and home-based care, and the corresponding need for equipment that can perform reliably across varied settings.
At the same time, a distinct wave of technology-driven entrants is exploring new modalities for blood purification. This includes devices and consumables designed for targeted removal of pathogens and toxins, advanced hemadsorption cartridges aimed at critical care applications, and experimental systems leveraging magnetic nanoparticle approaches for sepsis and other high-acuity indications. These efforts reflect a growing recognition that blood purification is not a monolithic category. Rather, it encompasses a spectrum of clinical challenges, each with distinct performance requirements, regulatory pathways, and reimbursement considerations. Our report analyzes how these emerging players fit into the broader ecosystem, what differentiates their value propositions, and where the most consequential competitive threats and partnership opportunities may arise.
The geographic footprint of competition is equally important. Leading manufacturers are headquartered across multiple regions, each bringing different strengths in engineering, clinical validation, and market access. The interplay between regional innovation clusters and global commercialization strategies shapes how quickly new technologies reach diverse patient populations. By examining the profiles and strategic posturing of key companies, readers gain a clearer understanding of who is likely to lead in specific subsegments and which organizational capabilities will be most valuable in the years ahead.
Market Structure and the Implications for Positioning
Understanding the architecture of the market is essential for effective strategy. The research highlights a concentrated competitive environment in which a core group of firms accounts for a substantial share of industry revenue. This concentration has meaningful implications. For incumbents, it underscores the importance of defending share through continuous innovation, service excellence, and strategic portfolio management. For challengers and new entrants, it points to the need for clear differentiation, whether through technology, niche application focus, cost structure, or partnership models that allow rapid penetration of specific channels.
The report also examines how segmentation intersects with market structure. Certain product categories and clinical applications represent the bulk of current revenue, while others, though smaller today, carry disproportionate strategic significance due to their growth profiles, unmet clinical needs, or alignment with evolving care delivery models. The analysis does not simply enumerate these segments. It evaluates them in terms of strategic relevance, examining the drivers that could accelerate or constrain growth and the competencies required to compete effectively within each. This approach ensures that readers can distinguish between segments that offer incremental volume and those that could fundamentally reshape product strategy and resource allocation.
Supply-side considerations are addressed with equal rigor. Manufacturing standards, quality assurance expectations, and regulatory compliance obligations are no longer peripheral concerns. They are central to commercial viability, particularly as authorities refine guidance for equipment and related production processes. Organizations that anticipate these requirements and embed them into product development and operational planning will be better positioned to navigate audits, maintain market access, and protect brand integrity. The report integrates these factors into its strategic assessment, helping leaders connect regulatory and operational realities to competitive positioning.
From Insight to Execution: How Leaders Should Use This Research
A market research report is only as valuable as the decisions it informs. PW Consulting has designed this study to be practical from the outset. It is intended to support a range of strategic use cases, including portfolio prioritization, market entry evaluation, competitive benchmarking, pricing and reimbursement strategy, and long-range planning. The emphasis throughout is on clarity, comparability, and relevance to executive decision-making.
Several principles guide the report's design. First, it grounds all projections in a rigorous methodology that accounts for historical performance, structural drivers, and forward-looking indicators, rather than relying on simplistic trend extrapolation. Second, it situates quantitative findings within qualitative context, explaining not just what is expected to happen but why it matters and how different scenarios could alter outcomes. Third, it maintains a focus on actionability, ensuring that insights can be translated into concrete next steps, whether that means refining a product roadmap, identifying target geographies, assessing partnership candidates, or stress-testing a commercialization plan against evolving regulatory and reimbursement conditions.
For organizations preparing for 2026 and the broader 2026-2032 forecast period, the research offers a unified reference point. It allows leadership teams to align around a shared understanding of market size, growth trajectory, competitive dynamics, and structural shifts. That alignment is critical. In a market where regulatory updates, reimbursement changes, and technological breakthroughs can alter the calculus quickly, a common strategic baseline reduces the risk of fragmented decision-making and helps ensure that resources are directed toward the highest-value opportunities.
The Strategic Imperative for the Next Phase of Growth
The blood purification equipment market is entering a phase in which scale, technology, and regulatory sophistication will increasingly separate winners from the rest. Growth to more than 22,500 million USD by 2032, supported by a 5.5 percent CAGR, is not automatic. It will be captured by organizations that can read the signals in the data, anticipate the impact of regulatory and reimbursement shifts, and align their capabilities with the evolving needs of clinicians and patients. The window for strategic positioning is open now, but it will not remain wide indefinitely.
Blood Purification Equipment Market
This report is intended to equip leaders with the intelligence required to act with confidence. It combines macro-level market sizing with detailed competitive and structural analysis, delivering a comprehensive view of an industry in transformation. Yet the full depth of the analysis, including the most granular segmentation data, scenario-based forecasts, and proprietary competitive assessments, is reserved for the complete study. For executives and strategy teams who need to make high-stakes decisions in 2026, the complete report provides the level of detail and context necessary to convert insight into execution.
The market will not pause for indecision. Blood purification equipment is central to the care of millions of patients, and the companies that define the next era will be those that combine clinical understanding with commercial discipline. PW Consulting's research is built to help you navigate that future with precision, clarity, and strategic advantage.
For detailed analysis of this topic, please visit the official page: Blood Purification Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


