



PW Consulting: Phosphorus Pentasulfide Market Hits $470M in 2025, Eyes $640.8M by 2032

Strategic Intelligence for the Phosphorus Pentasulfide Market: Navigating Growth, Supply Constraints, and Competitive Dynamics Through 2032
Why This Study Matters for 2026 Decision-Makers
The Phosphorus Pentasulfide (P2S5) market is entering a period of structural recalibration. Demand drivers are diverging across end-use sectors, feedstock volatility is reshaping cost architectures, and regulatory regimes are tightening across major trade corridors. For executives planning capital allocation, procurement strategy, and geographic expansion in 2026, surface-level market narratives are no longer sufficient. What is required is a structured, evidence-based view of how the market is likely to evolve across the forecast horizon, where margin pressure will concentrate, and which competitive positions will prove defensible as the industry matures.
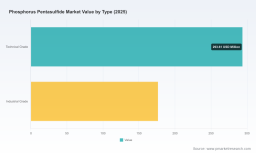
This research study is designed to provide that strategic clarity. Built on a rigorous historical baseline spanning 2020 through 2025 and extended forward across a multi-year forecast period, the analysis translates macro trajectory into decision-ready intelligence. The overall market has demonstrated a steady expansion path over the past half-decade, with revenue progressing from approximately 382.5 million USD in 2020 to an estimated 470.0 million USD in 2025. The forward trajectory suggests continued growth, with the market projected to advance toward the 640 million USD range by the end of the forecast window, supported by a compound annual growth rate of 4.6 percent. While these headline figures establish the scale of the opportunity, the real strategic value lies in understanding the forces shaping growth dispersion, the cost dynamics affecting supply resilience, and the competitive maneuvers that will define market leadership.
This study has been developed specifically to help organizations move beyond generic industry summaries. It is intended for strategy leaders, procurement executives, product managers, and investment analysts who need a coherent framework for interpreting phosphorus pentasulfide market behavior in 2026 and beyond. Rather than offering a static snapshot, the analysis connects demand-side shifts, supply-side constraints, and regulatory pressures into a single interpretive lens. The result is a research asset that can inform internal planning, support external engagement, and sharpen the questions teams should be asking as they evaluate growth options.
A Multi-Dimensional View of Market Structure and Trajectory
Effective strategy depends on segmentation that reflects how value is actually created and consumed. This study examines the phosphorus pentasulfide market through multiple analytical dimensions, enabling readers to assess not only how the market is composed today, but how segmentation logic is likely to influence competitive positioning and demand evolution over time.
The report maps the market across regional landscapes, product-grade distinctions, and application-based demand patterns, then integrates those views with broader industry context. This structure matters because P2S5 is not a uniform commodity market. Different grades serve different technical and commercial requirements, and demand patterns vary meaningfully by application and geography. By analyzing these layers together, the study provides a more credible basis for prioritizing markets, anticipating substitution pressure, and identifying where supply reliability or specification performance will become a decisive differentiator.
Readers will find detailed attention to the kinds of structural questions that often determine execution risk: which segments are expanding on the strength of technical demand rather than volume alone, where application portfolios are diversifying, and how regional demand profiles interact with production geography and logistics constraints. The analysis avoids oversimplified conclusions and instead frames each segment within the operational realities of handling, transportation, and downstream integration. This approach is especially relevant for organizations that must reconcile growth ambitions with the practical complexities of hazardous chemical supply chains.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The phosphorus pentasulfide market is characterized by a concentrated competitive structure, with a relatively small group of established players accounting for a substantial share of overall revenue. This concentration has important strategic implications. It suggests that pricing behavior, capacity decisions, and product differentiation are likely to be influenced by a limited set of players whose investments and market moves can shape sector-wide expectations. For buyers and competitors alike, understanding who holds capability, where capacity is located, and how firms are positioning themselves across grades and applications is essential.
Phosphorus Pentasulfide Market
The study profiles the market’s most consequential participants, including Trecora LLC, Perimeter Solutions, Prasol Chemicals Pvt Ltd, Hubei Xingfa Chemicals Group Co., Ltd., Shandong Sinchem Group Corporation, Liaoning Ruixing Chemical Group Co., Ltd., and Excel Industries Ltd. These companies represent a cross-section of operating models, geographic footprints, and product strategies. Some are oriented toward high-purity or specialty-grade supply for lubricant additives and advanced industrial applications; others compete primarily on scale and cost-competitive industrial-grade volumes across lubricants, agrochemicals, mining reagents, and related intermediate markets.
The strategic significance of these profiles goes beyond corporate description. The study uses them to illustrate how capability, plant footprint, and application focus shape competitive advantage in practice. For example, producers with specialized high-purity offerings are positioned to serve customers where specification reliability, safety, and downstream performance are paramount. At the same time, large-scale industrial-grade producers play a central role in meeting volume demand across lubricant, mining, and agrochemical value chains, where cost efficiency and supply consistency are often the primary drivers. By examining these distinctions, the report helps readers evaluate which types of suppliers are most relevant to their operating context and where supplier diversification or qualification strategies may be warranted.
The competitive analysis also accounts for recent market-moving developments. Notable activity includes the launch of top-grade phosphorus pentasulfide for lubricants with improved packaging designed to address handling and safety considerations, as well as capacity expansion efforts in Asia-Pacific aimed at strengthening supply availability while reducing environmental impact. Such developments are not isolated events; they signal how incumbents are responding to demand evolution, regulatory pressure, and shifting customer expectations. The study places these moves in context so that readers can interpret them as indicators of broader strategic direction rather than as isolated news items.
Industry Dynamics: Cost Structures, Regulation, and Supply Chain Risk
No phosphorus pentasulfide strategy can be built on demand outlooks alone. The market is shaped by a set of operational and regulatory realities that influence cost, availability, and risk exposure across the value chain. This study integrates those dynamics directly into its analytical framework so that decision-makers can assess not just where growth may occur, but how difficult it may be to capture profitably and reliably.
Worldwide Organic Polysulfide Market
One of the most persistent structural pressures comes from feedstock volatility. Fluctuations in the pricing of elemental yellow phosphorus and sulfur create cost uncertainty for producers and can complicate procurement planning for downstream users. Because these inputs are fundamental to phosphorus pentasulfide production, even moderate price movement can influence margins, sourcing decisions, and the economics of capacity utilization. The report examines how these raw material dynamics interact with supply resilience and what they imply for procurement timing, contract structures, and risk mitigation.
Regulatory complexity adds another layer of strategic importance. In Europe, stringent REACH requirements govern the handling and use of hazardous phosphorus compounds, adding compliance costs and shaping how products can be marketed and used across applications. At the same time, phosphorus pentasulfide is classified as a hazardous material under major transport regulations, including ADR, IATA, and IMDG frameworks, which imposes logistics cost burdens and constrains supply chain flexibility in global trade. Environmental and occupational safety rules further require tighter controls on reactivity with air and water in multiple jurisdictions. These factors collectively influence where production is viable, how products move across borders, and what compliance overhead must be built into commercial models.
Taken together, these dynamics underscore why market participation in this sector is not simply a function of demand visibility. It also depends on operational readiness, regulatory competence, and the ability to manage hazardous-material handling at scale. The study addresses these issues in a practical way, helping readers distinguish between markets that appear attractive on paper and those that can be served sustainably within existing operational and compliance capabilities.
What the Study Delivers: Practical Intelligence for Internal and External Decisions
This research report is structured to support a wide range of business decisions without overwhelming readers with undifferentiated data. It provides a comprehensive yet accessible foundation for analyzing the phosphorus pentasulfide market from both strategic and operational perspectives.
Key elements of the study include:
- A detailed market sizing and forecast framework that situates historical development within a forward-looking trajectory, giving executives a credible baseline for scenario planning and investment prioritization.
- A segmentation-oriented analysis that clarifies how the market is structured across regions, grades, and applications, enabling more precise evaluation of demand opportunities and exposure to segment-specific risk.
- In-depth company profiles of leading participants, with emphasis on product focus, geographic presence, and strategic orientation, so that readers can interpret competitive behavior in context rather than in isolation.
- An assessment of industry dynamics, including feedstock cost exposure, regulatory burdens, and transportation constraints, that links market structure to real-world execution challenges.
- A synthesis of recent developments and evolving market signals, helping teams understand how current activity reflects longer-term strategic shifts in product quality, safety, packaging, capacity, and regional supply strategy.
The report is designed to be actionable. It can support procurement strategies by clarifying where supply reliability, grade specification, and supplier diversification matter most. It can inform product and market planning by showing how application and regional demand patterns are likely to evolve. It can strengthen competitive intelligence by revealing how major players are positioning themselves across value chains and what that may imply for pricing, availability, and differentiation over time. For investors and analysts, the study provides a structured basis for interpreting market momentum and assessing the durability of competitive advantages.
Why the Full Report Is Essential for 2026 Planning
The phosphorus pentasulfide market is large enough to matter and complex enough to reward disciplined analysis. High-level numbers can indicate direction, but they do not reveal where competitive intensity will intensify, which segments will depend on technical performance rather than price alone, or how regulatory and logistics constraints will shape the practically accessible market. Those questions require deeper segmentation, company-level insight, and a clear treatment of the forces that influence cost and risk.
This study is built to provide that depth while remaining focused on strategic relevance. It is intended to help organizations move from observation to action: to refine market entry thinking, calibrate procurement strategy, anticipate competitive responses, and prepare for the operational realities that accompany participation in a hazardous-chemical value chain. The detailed segmentation data, regional and application-level breakdowns, and company-specific intelligence that support these conclusions are presented in full within the complete research report.
For teams responsible for 2026 planning, the difference between informed strategy and reactive decision-making often comes down to the quality of the underlying intelligence. This study is designed to close that gap by offering a rigorous, internally coherent view of where the phosphorus pentasulfide market stands today and how it is likely to develop across the forecast period. The complete report provides the detailed market framework, segmentation evidence, and competitive analysis needed to translate these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Phosphorus Pentasulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


