



PW Consulting: Popcorn Market Hits $7.5B in 2025, Poised for 6.85% CAGR Through 2032

Popcorn Market Strategic Outlook 2026: Navigating Growth, Innovation, and Regulatory Shifts
The global popcorn market stands at a critical inflection point as we move through 2026. What was once viewed as a stable snack category with predictable seasonal patterns has evolved into a dynamic landscape shaped by shifting consumer preferences, intensifying regulatory scrutiny, and rapid innovation in packaging and product formats. For executive teams, category managers, and strategic planners, the ability to anticipate these forces is no longer optional. It is a competitive necessity. Our latest market research publication, the Popcorn Market Analysis, is designed to provide the analytical rigor and forward-looking perspective required to make informed decisions in this evolving environment.
Market Trajectory and Macro Growth Context
Historical data underscores the category resilience and steady expansion that have characterized the popcorn sector over the past half-decade. Between 2020 and 2025, global revenue climbed from USD 5.0 billion to USD 7.5 billion, reflecting a compound trajectory that has outpaced many adjacent packaged food segments. The forecast period extending through 2032 projects continued upward momentum, with market value expected to reach USD 11.69 billion by the close of the forecast window. This growth path is anchored by a forecasted compound annual growth rate of 6.85 percent, a figure that signals sustained demand expansion rather than a temporary cyclical surge.
The scale of this expansion carries direct implications for capital allocation, capacity planning, and channel strategy. Companies that treat popcorn as a legacy commodity risk underestimating the structural shifts driving volume and value migration. The research delves into the underlying demand drivers, consumption frequency patterns, and format preferences that are reshaping the category baseline. Rather than presenting a static snapshot, the analysis maps the inflection points where strategic intervention can yield outsized returns. Readers seeking granular regional breakdowns, format-level revenue contributions, and channel-specific growth differentials will find those details within the full report, where the data is structured to support precise scenario modeling and investment prioritization.
Competitive Landscape and Strategic Positioning
Incumbent Players and Portfolio Architecture
The market remains characterized by a relatively concentrated competitive structure, with the top three players commanding a combined share that reflects the durable influence of established brands and vertically integrated supply chains. The top five competitors collectively hold a substantial majority of category revenue, creating a landscape where scale, distribution access, and brand equity function as powerful barriers to entry. Several incumbent organizations continue to anchor the market through well-recognized microwave and ready-to-eat portfolios.
Peanuts Market
ConAgra Brands, headquartered in Chicago, Illinois, remains a defining presence through its Orville Redenbacher's and Act II lines, brands that have long set consumer expectations for taste, texture, and convenience in the microwave segment. American Pop Corn Company, based in Iowa, sustains its market position through the Jolly Time brand, which spans both kernel and microwave offerings and carries significant retail penetration. Snyder's-Lance, operating under the Pop Secret brand, continues to compete aggressively in the microwave space with a focus on flavor innovation and tangency with broader snacking trends.
Beyond the branded microwave players, specialized and vertically integrated producers occupy strategic niches. Weaver Popcorn Company, operating from Illinois, supplies bulk popcorn kernels tailored for commercial, theater, and gourmet applications, serving a channel that underpins much of the out-of-home consumption experience. Princeton Popcorn Company, also based in the United States, has built its reputation on mushroom and specialty popcorn varieties, emphasizing a differentiated product architecture that appeals to premium and niche positioning. These operators illustrate how the competitive field is not monolithic; rather, it is stratified across value, premium, specialty, and ingredient-supply tiers, each with distinct margin profiles and growth vectors.
Recent Operational Events and Risk Signaling
The competitive environment is not static, and 2026 has already produced operational events that carry strategic lessons. Food safety and quality control remain paramount, as evidenced by a series of voluntary recalls that have surfaced in recent months. Jonco Industries, Inc. initiated a voluntary recall of certain consumer-sized white cheddar seasoning products in May 2026 due to potential Salmonella contamination, a reminder that seasoning and flavor systems introduce distinct risk vectors beyond the kernel itself. In April 2026, Prospector Popcorn, LLC conducted a voluntary recall of its Belgian Chocolate Toffee Popcorn due to potential contamination, highlighting the vulnerabilities that can accompany specialty flavor extensions and co-manufacturing arrangements.
Associated Food Stores expanded the scope of risk awareness in May 2026 by initiating a recall of 6,480 containers of Red Button Movie House Buttered Popcorn for possible foreign material contamination, an event that underscores the importance of supply chain visibility and traceability across private-label and licensed movie-theater formats. These incidents, drawn from FDA and industry recall notices, are not isolated anomalies; they are stress tests that reveal where quality systems, supplier qualifications, and recall readiness must be strengthened. The full research report maps these events within a broader risk management framework, offering structured guidance on how to assess vendor resilience, build redundancy into flavor and packaging supply chains, and align quality assurance protocols with the realities of scale and speed.
Simultaneously, product innovation continues to push the category forward. In April 2026, Gold Medal Products Co. announced the launch of ReadyServe Jr., a compact self-serve popcorn dispenser targeted at sports bars, convenience stores, and entertainment venues. This development signals a deliberate push to capture out-of-home and on-the-go consumption occasions with hardware-enabled distribution models. The research evaluates such innovations not merely as product launches but as strategic bets that reshape channel economics, consumer interaction points, and the boundary between packaged goods and equipment-based concession solutions.
Regulatory and Supply Chain Dynamics
The 2026 decision environment is being reshaped as much by regulatory and input-side factors as by consumer demand. On the raw material front, US corn production reached 1.23 billion metric tons in the 2024/2025 season, providing a robust feedstock base for popcorn kernel supply. This scale of agricultural output supports stable input availability, but it also invites scrutiny of price volatility, crop quality consistency, and the geographic concentration of supply. The report examines how kernel sourcing strategies intersect with processor margins, contract structures, and the risk of regional supply disruptions.
Regulatory change is equally consequential. In May 2025, the US FDA proposed a front-of-package nutrition labeling rule that would require simplified indicators for saturated fat, sodium, and added sugars on most packaged foods, including popcorn. For a category that spans lightly seasoned kernels, butter-flavored microwave bags, and indulgent ready-to-eat formats, this proposal has direct implications for packaging design, product reformulation, and consumer communication. The research explores how leading players are modeling the potential impact on shelf placement, brand perception, and the relative competitiveness of healthier versus indulgent segments.
Packaging regulation is advancing on multiple fronts. As of January 2025, PFAS-containing grease-proofing substances used in food contact packaging no longer hold effective FDA food contact notifications, altering the compliance landscape for microwave popcorn bags and other coated packaging formats. At the state level, jurisdictions such as Louisiana and Texas enacted 2025 laws requiring PFAS restrictions in food packaging materials, creating a patchwork of requirements that complicates multi-state distribution and sourcing. In Europe, the Packaging and Packaging Waste Regulation entered force in 2025, mandating recyclable packaging with labeling for recycling and reusability on food products, including popcorn. These overlapping requirements introduce cost, design, and timeline pressures that directly affect product roadmaps and supplier selection. The full report provides a structured analysis of how these regulations interact with product formats, regional rollout strategies, and the economics of packaging transitions.
Popcorn Market
Demand Architecture and Channel Evolution
Understanding where and how popcorn is purchased is essential for any strategy that aims to capture growth efficiently. The category is distributed across a mix of retail and convenience channels, each with distinct consumer behavior, margin structures, and promotional dynamics. Supermarkets and hypermarkets represent the largest distribution conduit, reflecting the category's role as a staple pantry and impulse snack within the broader grocery basket. Convenience stores contribute a meaningful share, driven by grab-and-go consumption, solitary snacking occasions, and the channel's sensitivity to flavor innovation and pack size optimization. Online retail, while smaller in absolute terms, continues to expand as e-commerce penetration deepens and consumers increasingly use digital channels for replenishment and discovery.
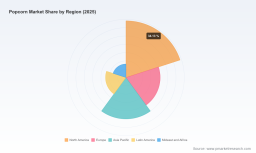
Format preferences further complicate the demand picture. Ready-to-eat popcorn and microwave popcorn each serve distinct usage occasions, with different expectations around convenience, portion control, flavor variety, and preparation experience. The research disentangles these format-driven behaviors and examines how they interact with channel selection, pricing architecture, and promotional effectiveness. Rather than treating format and channel as independent variables, the analysis models their intersection to reveal where white space exists for line extensions, pack rationalization, and channel-specific assortment strategies. Detailed segmentation contributions and region-level revenue distributions are provided in the complete report, enabling teams to prioritize the markets and formats that align with their specific growth objectives.
Strategic Implications for 2026 Decision-Making
The 2026 landscape demands a strategy that is simultaneously ambitious and disciplined. Growth is available, but it is increasingly distributed across formats, channels, and regional dynamics that reward precision over broad-stroke assumptions. Several strategic priorities emerge from the research framework.
- Align product portfolios with regulatory trajectories. Front-of-package labeling, PFAS restrictions, and packaging recyclability mandates are not distant contingencies; they are active forces shaping packaging costs, reformulation timelines, and shelf positioning. Companies that integrate regulatory forecasting into portfolio planning will reduce exposure and capture first-mover advantages in compliant design.
- Strengthen supply chain resilience and quality assurance. The recall events of early 2026 illustrate the cost of vulnerability in seasoning systems, specialty flavor extensions, and foreign-material controls. Strategic investment in supplier qualification, traceability, and recall readiness should be treated as a margin protection and brand trust imperative.
- Exploit channel and format intersections. The largest demand pools are not uniform. Supermarket, convenience, and online channels each reward different pack sizes, flavor profiles, and pricing strategies. Ready-to-eat and microwave formats serve different occasions and require distinct innovation and merchandising approaches. Segmentation-aware planning enables more efficient resource allocation.
- Monitor competitive signaling from incumbents and niche players. The concentration of revenue among leading brands does not eliminate disruption risk. Vertical integrators, specialty variety producers, and equipment-enabled concession innovations can alter channel economics and consumer expectations. Continuous competitive intelligence is necessary to distinguish temporary noise from structural shifts.
- Ground decisions in scenario-based forecasting. The forecast period through 2032 projects a market trajectory that supports long-term investment, but the path is influenced by input costs, regulatory timing, and consumer response to labeling and packaging changes. Scenario modeling that stress-tests assumptions across these variables improves the quality of capital and inventory decisions.
What the Full Research Delivers
This article serves as a strategic preview, but the complete Popcorn Market research publication provides the depth required for execution-level planning. The report integrates historical performance data, forecasted market sizing, and structured segmentation analysis across regions, product types, and distribution channels. It includes detailed profiles of key market participants, an evaluation of recent operational events and their implications for quality and supply chain management, and a regulatory and raw material context that maps the forces shaping cost structures and compliance timelines.
Beyond data presentation, the research translates analysis into actionable frameworks. Readers will find scenario models that connect market growth to strategic choices, channel and format assessments that support assortment and pricing decisions, and competitive landscape mapping that clarifies positioning opportunities and threat vectors. The objective is to equip decision-makers with a coherent view of where growth is concentrated, where risk is accumulating, and where intervention can create durable advantage.
For teams preparing 2026 planning cycles, the full report is designed to function as a reference point for capital allocation, product roadmap prioritization, channel strategy, and risk mitigation. We invite you to access the complete publication to explore the segmentation breakdowns, regional revenue distributions, and detailed competitive and regulatory analyses that underpin the strategic recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Popcorn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


