



PW Consulting: Respiratory Humidifying Equipment Market Hits $7B in 2025, Poised for $11.6B by 2032

Strategic Intelligence for the Respiratory Humidifying Equipment Market: Navigating the 2026 Decision Landscape
The respiratory humidifying equipment market stands at a critical inflection point. As healthcare systems worldwide recalibrate around patient outcomes, supply chain resilience, and sustainable procurement, the devices that deliver optimal airway hydration have evolved from routine clinical accessories to strategically decisive assets. For executives, procurement leaders, and medical technology strategists, the weeks leading into 2026 demand more than generalized market briefings. They require structurally sound, forward-looking intelligence capable of informing capital allocation, R&D prioritization, competitive positioning, and regulatory compliance roadmaps.
Our latest comprehensive study, Respiratory Humidifying Equipment Market, is engineered to meet that exact requirement. Spanning a rigorous historical retrospective from 2020 through 2025 and projecting systematically across the 2026–2032 forecast horizon, the analysis translates complex clinical, regulatory, and commercial signals into actionable executive guidance. This overview outlines the strategic architecture of the report, demonstrates how macroeconomic and tactical data are synthesized, and clarifies the executive decisions the study is designed to support.
Executive Context: Why the Market Now Demands Precision Intelligence
The structural drivers shaping respiratory humidification are no longer confined to incremental clinical adoption. They intersect with regulatory recalibration, reimbursement architecture, material science breakthroughs, and consolidation pressures within the medical device supply chain. Organizations that continue to rely on fragmented market snapshots or backward-looking incident reports risk misallocating development budgets, underestimating compliance timelines, and misreading competitive velocity.
Respiratory Humidifying Equipment Market
The research is grounded in a disciplined quantitative foundation. Tracking the market’s progression from approximately 5,200 million USD in 2020 to a 2025 baseline of 7,000 million USD, the study documents a trajectory defined by sustained clinical demand, technology maturation, and gradual geographic expansion. The forecast period extends to 2032, reflecting a compound annual growth rate of 7.75 percent. By anchoring analysis in this extended horizon, the report enables decision-makers to evaluate not only near-term operational impacts but also multi-year capacity planning, product portfolio evolution, and strategic partnership timing. Importantly, the narrative treats top-line magnitude and growth velocity as directional compasses rather than isolated metrics, always threading them into the operational conditions that actually determine commercial execution.
Report Architecture: Operational Intelligence Over Abstract Market Commentary
A distinguishing feature of this study is its emphasis on execution-ready content. Rather than cataloguing broad trends, the analysis dissects the operational levers that determine procurement cycles, product roadmaps, and pricing architecture. The report integrates rigorous segmentation perspectives across product architecture, clinical environment, and geographic deployment, while deliberately preserving analytical depth that supports scenario modeling and internal stakeholder alignment.
Worldwide Active Humidifier Devices Market
Product Architecture and Clinical Deployment Dynamics
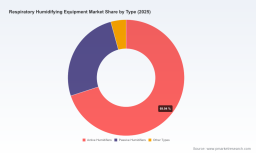
The study examines how humidifier design philosophies are diverging across clinical workflows. Active heated systems, passive condensation-management configurations, and ancillary accessory categories are analyzed not merely as discrete revenue pools, but as responses to distinct clinical demands, sterilization requirements, and integration constraints. The research explores how product architecture decisions influence procurement frequency, service intensity, and total cost of ownership across acute care, extended-stay facilities, and decentralized care environments.
Equally critical is the report’s treatment of application pathways. By mapping how humidification technologies are deployed across institutional settings, long-term care environments, homecare programs, and specialized respiratory support contexts, the analysis identifies where adoption velocity is being accelerated by workflow integration, reimbursement alignment, or care-delivery restructuring. This application-level perspective helps organizations anticipate where channel strategy, clinical validation, and service infrastructure must be synchronized to capture durable demand.
Geographic Exposure and Regional Commercial Architecture
Market opportunity is not uniformly distributed, and neither is the operational complexity of capturing it. The research builds a regional framework that examines how healthcare infrastructure maturity, procurement governance, regulatory cadence, and distribution ecosystems shape market penetration. By evaluating how different regions absorb product introductions, navigate sterilization and maintenance logistics, and respond to reimbursement mechanisms, the report enables firms to prioritize market-entry sequencing, localization investments, and partnership strategies with greater precision.
Competitive Architecture: Positioning in a Concentrated but Dynamic Field
Concentration in the respiratory humidifying equipment market is substantial, with the three largest participants collectively commanding a dominant share and the top five consolidating an even broader portion of total revenue. Yet concentration does not equate to stagnation. The field remains tactically active, with incumbents upgrading integrated humidification platforms, challengers pursuing regulatory clearances, and component specialists expanding sustainable material capabilities.
The report provides a structured evaluation of the companies defining this competitive environment. Profiles extend beyond descriptive summaries to examine each organization’s product philosophy, integration strategy, geographic footprint, and recent commercial moves. The analysis covers firms with distinct strategic identities: organizations anchoring their position in advanced heated humidification systems for hospital and homecare respiratory support; manufacturers focused on mechanical ventilation gas humidification and patient respiratory support components; suppliers of active heated humidifiers and breathing systems for hospital respiratory care; developers of heated humidification systems for clinical respiratory support; ventilator-integrated humidifier manufacturers serving ICU and respiratory applications; providers of CPAP and NIV humidification systems for sleep and respiratory therapy; companies embedding humidification within BiPAP and ventilator ecosystems; suppliers of humidifiers tailored to intensive care and neonatal respiratory care; firms integrating humidification with adult and pediatric ventilator platforms; developers of respiratory humidification circuits and accessories oriented toward sustainable care; and manufacturers of respiratory care humidification solutions designed for both hospital and homecare environments.
Recent company-level developments illustrate the contours of this competitive dynamism. In late 2025, one manufacturer announced a next-generation humidifier designed to minimize condensate for advanced respiratory support, signaling continued emphasis on workflow efficiency and airway management. Around the same period, a separate medical company secured regulatory clearance for a respiratory humidifier unit, reinforcing the importance of compliance milestones in sustaining commercial momentum. Meanwhile, a component and circuit specialist advanced a series of sustainability-focused milestones, including the launch of a bioplastic-based breathing circuit and humidification component showcased at a major industry trade fair, alongside multiple certifications intended to strengthen quality standards and sustainable innovation credentials within respiratory humidifying equipment. These developments are not presented as isolated announcements; they are interpreted as indicators of how product differentiation, regulatory timing, and material sustainability are converging into competitive advantage.
Market Dynamics: The Operational Forces Shaping Commercial Execution
Commercial outcomes in this sector are increasingly determined by the interplay of regulation, reimbursement, material economics, and infrastructure realities. The report treats these forces not as background context but as primary variables in the competitive equation.
Regulatory and Standards Evolution
The regulatory environment is tightening the operational boundaries within which humidification devices are designed, validated, and deployed. Updated safety and performance specifications are redefining compliance expectations for respiratory humidifiers in medical settings. At the same time, guidance emphasizing proper disinfection, performance testing, and sterilization control standards reinforces the clinical and legal importance of documented hygiene protocols. For manufacturers and procurement organizations alike, these measures alter development timelines, validation burdens, and lifecycle management expectations, making regulatory readiness a strategic asset rather than an administrative task.
Reimbursement Architecture and Commercial Access
Reimbursement structures directly influence adoption speed and procurement predictability. Specific billing codes continue to serve as the operational mechanism for reimbursement of respiratory humidifiers and heated humidifiers under Medicare policies. Understanding how these code categories function, where they facilitate access, and where they create administrative friction is essential for forecasting demand stability and designing commercially viable product configurations. The study examines these reimbursement pathways as enablers or constraints on segment-level growth, especially in settings where cost justification must withstand structured review.
Material Economics, Sterilization, and Procurement Cycles
Material selection and processing costs have become decisive factors in both product design and procurement behavior. Elevated raw material costs intersect with the demand for biocompatible, sterilizable materials featuring antimicrobial coatings, influencing not only production economics but also replacement cycles and service frequency. In parallel, sterilization and maintenance costs remain a persistent constraint, particularly for smaller hospitals and homecare adoption, where operational budgets are tighter and service infrastructure is less centralized. The report analyzes how these cost pressures affect purchasing intervals, product longevity expectations, and the competitive appeal of systems that reduce total lifecycle burden.
Strategic Implications for 2026 Decision-Making
For organizations operating in or entering this market, 2026 is a year of structural choices. Should product strategy prioritize integration with mechanical ventilation and critical care platforms, or expand into decentralized respiratory support and homecare ecosystems? How should R&D resources be divided between performance enhancement, condensate management, and sustainable material adoption? Where should commercial teams concentrate regulatory preparation, reimbursement alignment, and distribution partnerships to minimize time-to-value?
The research is designed to support these decisions through scenario-based interpretation rather than static snapshots. By combining historical trajectory, forward demand projections, segmentation logic, competitor movement analysis, and operational constraint mapping, the study enables leaders to stress-test assumptions. Companies can evaluate how product launches, regulatory updates, certification milestones, and reimbursement clarity may shift competitive positions. Procurement leaders can better anticipate where sterilization, maintenance, and material constraints will influence supplier selection. Strategy teams can identify which geographic and application opportunities warrant earlier investment versus more cautious monitoring.
The report also recognizes that market advantage increasingly depends on anticipating secondary effects. A new product announcement may matter less for its headline presence than for what it reveals about rival engineering priorities. A certification achievement may signal not just compliance status but readiness to expand into regulated channels. A standards update may reshape procurement specifications long before a purchasing cycle formally opens. By reading these signals together, executives can convert market complexity into timing advantage.
How to Use This Study for Enterprise Planning
The study is structured to serve multiple internal audiences without diluting analytical precision. Executive leadership can use the forecast horizon and macro growth trajectory to frame capital allocation and portfolio review. Product and engineering teams can leverage the segmentation architecture, material considerations, and standards developments to prioritize feature roadmaps and manufacturing requirements. Commercial and market access teams can draw on the competitive landscape, reimbursement context, and application-level deployment analysis to refine channel strategy and pricing logic. Regulatory and quality teams can integrate the compliance and sterilization expectations into planning calendars and documentation workflows.
To preserve the strategic integrity of the analysis while ensuring operational relevance, the full report moves beyond directional commentary into detailed segmentation splits, revenue breakdown structures, regional deployment profiles, product-type contributions, application-level demand distribution, and company-specific performance indicators. Those datasets form the quantitative backbone required for board-level reviews, investor communications, go-to-market planning, and competitive benchmarking.
Closing Perspective
The respiratory humidifying equipment market is being reshaped by the convergence of clinical performance expectations, regulatory rigor, reimbursement discipline, and sustainability-driven product innovation. In that environment, strategic decisions made in 2026 will set the trajectory for the remainder of the decade. Organizations that rely on incomplete market narratives risk reacting late to compliance shifts, misreading competitive intent, and underpositioning against evolving procurement economics.
This study provides the depth, structure, and forward orientation necessary to move from reactive awareness to deliberate strategy. By translating historical momentum, forecast growth, competitive maneuvers, and operational constraints into a unified executive framework, it equips decision-makers to align product, commercial, and compliance strategies with the realities of the market ahead. The full intelligence set—segment-level breakdowns, regional deployment figures, application distribution detail, and company-specific indicators—completes the analytical picture required for high-stakes planning.
For leaders seeking to secure a decisive informational advantage, the complete report is available through our official market research portal, where the full dataset, segmentation detail, and competitive profiles can be reviewed in their entirety and integrated directly into enterprise strategy workflows.
For detailed analysis of this topic, please visit the official page: Respiratory Humidifying Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


