



PW Consulting: Automotive Vacuum Pump Market to Hit $3.04B by 2032 with 6.5% CAGR

The Automotive Vacuum Pump Market: Strategic Intelligence for 2026 and Beyond
The automotive industry is navigating a structural transformation defined by electrification, stringent emissions regulations, and evolving safety architectures. At the intersection of braking performance, engine management, and thermal integration, the automotive vacuum pump market has emerged as a critical subsystem category. This report provides a comprehensive, decision-ready analysis of market trajectory, competitive positioning, and technology migration patterns across the forecast period from 2026 to 2032.
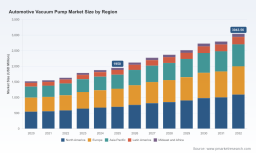
Our baseline assessment situates the market within a broader historical context spanning 2020 through 2025. Over this six-year window, the global market advanced from 1,520.0 million USD to a projected 1,950.0 million USD in 2025, reflecting sustained adoption of electric vacuum pumping solutions, integration into brake-by-wire architectures, and demand from hybrid and electric vehicle platforms. Looking forward, the forecast window projects continued expansion, with the market reaching 2,121.39 million USD in 2026 and progressing toward 3,043.56 million USD by 2032. This trajectory implies a compound annual growth rate of 6.5 percent, underscoring a market that is not merely growing in absolute terms but is also evolving in capability, supplier concentration, and application complexity.
For executive teams, product planners, procurement leaders, and investment analysts, these figures are not isolated statistics. They represent a signal of where value is moving within the powertrain and chassis subsystems landscape. The market is no longer defined by a linear replacement cycle. Instead, it is being reshaped by regulatory mandates, electrified brake architectures, and the need for on-demand vacuum generation in engine-off and start-stop conditions. Understanding this shift is essential for 2026 planning cycles, supplier negotiations, platform allocation decisions, and long-term portfolio strategy.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will be judged against how well organizations anticipated the convergence of electrification, braking safety, and emissions compliance. The automotive vacuum pump market is no longer a peripheral component category. It sits at the core of brake assist reliability, hybrid energy management, and advanced driver assistance functionality. This research is designed to help leaders cut through short-term noise and focus on durable structural drivers.
The study translates market growth into actionable intelligence. Rather than presenting numbers in isolation, the analysis ties valuation trends to product substitution patterns, architecture shifts, and supplier capability profiles. Decision-makers can use this framework to assess where demand is most likely to intensify, which performance attributes will differentiate winning products, and how supplier ecosystems are consolidating or expanding around key vehicle programs. The report also supports scenario planning by linking technology deployment logic to real-world operational requirements such as low-noise operation, thermal load management, and rapid vacuum buildup during engine-off phases.
Equally important, the report provides context for regulatory and safety developments that influence purchasing and engineering priorities. On-demand vacuum generation has become a relevant factor in meeting CO2 reduction targets, supporting downsized engine architectures, and ensuring brake assist continuity in hybrid and electric applications. At the same time, market participants have had to respond to field performance concerns, including notable recall actions that highlighted the importance of robust vacuum pump reliability in certain brake assist conditions. These events reinforce the strategic value of better data, tighter quality oversight, and more resilient supplier selection.
What the Report Delivers in Practice
This market research is built for operational use. It goes beyond headline figures and provides a structured foundation for product planning, competitive benchmarking, and market entry evaluation. The study is organized to support practical decision-making across multiple functional areas:
- Market sizing and forecast logic that connects historical performance with forward-looking demand assumptions across the 2026 to 2032 period
- Technology segmentation analysis that examines how different pump architectures are positioned across vehicle categories and subsystem requirements
- Application-level demand mapping that identifies where vacuum pumps are most critical within brake systems, engine management, HVAC systems, and emission control domains
- Regional demand context that highlights where volumes are developing and how regional vehicle mix, electrification pace, and OEM sourcing strategies shape opportunity
- Competitive landscape profiling that evaluates major incumbents and emerging contributors by technology focus, geographic footprint, and program relevance
- Recent product and deployment developments that track how suppliers are translating engineering intent into market-facing launches and modular platform strategies
- Regulatory and safety context that frames how compliance requirements and field performance issues influence design priorities and sourcing confidence
The report is intentionally constructed to support both strategic and tactical use cases. Product planners can assess where to allocate development resources. Procurement teams can better understand concentration risk and alternative sourcing options. Commercial teams can identify which applications and regions are likely to generate the strongest demand momentum. Investors and analysts can use the framework to interpret supplier commentary, program wins, and technology migration signals with greater precision.
Competitive Landscape and Technology Leadership
The competitive structure of the market reflects a concentrated but diversified supplier base. Market concentration metrics indicate that the top three participants account for approximately 25.8 percent of market revenue, while the top five participants represent about 35.2 percent. This structure suggests that while scale incumbents remain influential, there is meaningful room for specialist suppliers, regional players, and technology-focused entrants to compete on performance, integration, and program access.
Several European and Asian suppliers are defining the current pace of innovation. Continental AG has been advancing electric vacuum pump solutions for brake systems in passenger cars, commercial vehicles, and hybrid applications, with integration pathways into zone control and brake-by-wire architectures. Robert Bosch GmbH has expanded its electric vacuum pump platform across global SUV programs that rely on brake-by-wire for stable vacuum independent of engine operation, while also supporting modular deployments with adaptive control and regenerative braking compatibility. MAHLE GmbH has focused on high-efficiency electric vacuum pumps with integrated thermal management modules suited to 48V mild-hybrid and electric vehicle architectures.
Valeo SA supplies electric vacuum pumps for brake assist and emissions control in micro-hybrid and electric vehicles, including OEM supply relationships with major Asian manufacturers. Hella GmbH & Co. KGaA provides electric vacuum pump solutions for power brake boosters, including auxiliary and diaphragm-type models for hybrid and internal combustion engine braking systems. Rheinmetall Automotive AG, through its Pierburg division, supplies high-efficiency electric vacuum pumps for hybrid passenger vehicles, optimized for low noise, rapid buildup, and on-demand operation during engine-off phases.
From an Asia-Pacific and emerging-market perspective, Denso Corporation develops diaphragm-type electric vacuum pumps for hybrid and internal combustion engines with adaptive control intended to improve braking and fuel efficiency. Aisin Seiki Co., Ltd. supplies electric vacuum pumps for automotive brake systems integrated with advanced driver assistance and efficiency-related systems. Ningbo Tuopu Group Co., Ltd. produces electric vacuum pumps as part of intelligent brake systems, supporting mass production and OEM supply for passenger and commercial vehicles. Youngshin Precision Co., Ltd. manufactures electric vacuum pumps for automotive braking systems with an emphasis on quality and global OEM supply. Johnson Electric develops electric vacuum pumps for automotive applications including brake assist and hybrid systems. Advik Hi-Tech Pvt Ltd manufactures and supplies advanced electric vacuum pumps for passenger cars and commercial vehicles, including 48V ABS-related applications for hybrid and electric use.
The competitive picture is not static. Recent activity through early 2025 shows how supplier roadmaps are being executed in practice. In January 2025, Advik Hi-Tech unveiled a broader range of automotive components, including advanced electric vacuum pumps for passenger cars and commercial vehicles. Also in January 2025, Robert Bosch GmbH expanded deployment of its electric vacuum pump platform across multiple global SUV programs using brake-by-wire for stable vacuum independent of engine operation. In March 2025, Continental AG unveiled a high-performance electric vacuum pump for passenger internal combustion engines in Europe, featuring adaptive vacuum control for power efficiency and regenerative braking support. In April 2025, Pierburg under Rheinmetall Automotive launched an electric vacuum pump in Germany designed to reduce CO2 emissions and enhance hybrid and brake systems. In the same month, Denso Corporation launched a diaphragm-type electric vacuum pump in Asia-Pacific with adaptive vacuum control for hybrid and internal combustion engines to improve braking and fuel efficiency.
Vacuum Pumps Market
These developments matter because they demonstrate a shift from generic component supply toward application-specific optimization. Suppliers are increasingly designing for engine-off reliability, low parasitic loss, noise reduction, and integration with electrified brake and chassis control systems. That shift has direct implications for sourcing strategy, validation requirements, and long-term supplier partnerships.
Demand Drivers and Market Dynamics
The market's forward momentum is anchored in several reinforcing dynamics. First, electrification and hybridization continue to reshape vacuum requirements. In hybrid and electric vehicles, vacuum can no longer be assumed from a running engine in all operating conditions. Electric vacuum pumps enable on-demand brake vacuum generation, which supports brake assist performance and helps vehicle programs comply with CO2 reduction targets while maintaining safe and predictable braking behavior in downsized and electrified powertrains.
Second, brake-by-wire and advanced driver assistance deployment are increasing the importance of stable vacuum management during engine-off and start-stop events. In 2025, deployments of electric vacuum pumps in brake-by-wire systems have provided stable vacuum for advanced driver assistance functionality during those transitions. This is not merely an efficiency consideration; it is a safety and architecture consideration that influences which pump technologies are selected for next-generation vehicle programs.
Third, integration into 48V mild-hybrid architectures has created new design priorities. Electric vacuum pumps in these systems can reduce thermal load and parasitic losses while maintaining brake booster performance. At the same time, high-efficiency electric vacuum pumps for hybrid passenger vehicles are being optimized for low-noise operation and pulse-width-modulated control to minimize energy draw during intermittent engine phases. These engineering refinements indicate a market that is moving toward higher-performance, more tightly integrated solutions rather than commoditized replacements.
Fourth, safety and reliability scrutiny remains an important market factor. Field events such as the NHTSA recall action in August 2025, which addressed vacuum pump failure that could reduce brake assist performance under specific conditions, highlight the consequences of performance variability in critical brake systems. For sourcing and engineering teams, this reinforces the need for thorough validation, robust quality processes, and supplier selection criteria that account not only for cost and volume, but also for long-term durability and system-level reliability.
These dynamics collectively shape the market's next phase. Demand is not simply increasing; it is becoming more selective. Vehicle programs are increasingly evaluating vacuum pump solutions in the context of electrified braking architectures, thermal constraints, acoustic targets, and regulatory expectations. Suppliers that can demonstrate adaptive control, low energy consumption, rapid vacuum buildup, and integration-ready packaging are better positioned to participate in higher-value programs.
Where the Market Appears to Be Heading
Based on the trajectory documented in this study, the market is likely to continue expanding as vehicle electrification deepens and brake architectures become more dependent on electronically managed vacuum support. Growth is expected to be distributed across multiple application domains, with brake systems and engine management remaining central demand anchors while HVAC and emission control applications contribute additional volume and differentiation opportunities. The relative importance of electric vacuum pumps is expected to rise as hybrid and electric vehicle content increases and as braking safety requirements become more tightly integrated with advanced driver assistance and chassis control logic.
Regional variation will continue to influence market outcomes. Vehicle mix, electrification pace, OEM sourcing preferences, and regulatory exposure differ materially across regions, and these differences shape where demand scales most quickly and which supplier capabilities are most valued. The report examines these regional patterns without reducing them to simplistic rankings. Instead, it situates each region within the broader context of vehicle production, technology adoption, and program timing.
The competitive environment is also likely to evolve through a combination of consolidation, technology specialization, and program-level competition. Incumbents with strong brake system integration and global OEM relationships will continue to play a leading role, while regional and specialist suppliers may gain traction where they can demonstrate differentiated performance in noise, efficiency, packaging, or application-specific control. The market concentration structure suggests that scale matters, but it does not guarantee advantage unless supported by product relevance and reliability.
How to Use This Research in 2026 Planning
This report is intended to support concrete decisions rather than generic market awareness. In 2026, organizations can use the findings to align product roadmaps with demand where it is most likely to grow, assess supplier portfolios against performance and integration requirements, and anticipate how regulation and safety expectations will shape validation and sourcing criteria. The study also supports more disciplined interpretation of supplier announcements, program wins, and technology launches by placing them in a broader market context.
Automotive Vacuum Pump Market
For teams comparing opportunities across applications or regions, the report provides a structured basis for evaluating where vacuum pump demand is most strategically relevant and which technology attributes are gaining importance. For teams managing supplier relationships, it offers a framework for assessing concentration, differentiation, and program readiness. For analysts and investors, it provides a market narrative that connects sizing, growth, and competitive action to underlying automotive trends rather than short-term cycles.
Conclusion
The automotive vacuum pump market is entering a phase in which growth and technology transformation are intertwined. Historical expansion from 2020 through 2025 and the projected path toward 2032 indicate a market that is responding to electrification, brake system modernization, and emissions-driven design constraints. The market is not simply getting larger; it is becoming more performance-sensitive, more application-specific, and more dependent on supplier capability in areas such as adaptive control, thermal integration, and reliability under engine-off conditions.
This report translates that complexity into a usable strategic framework. It combines market sizing, segmentation logic, competitive profiling, and recent industry developments with the regulatory and safety context that influences sourcing and engineering decisions. For organizations preparing for 2026 and beyond, the value of the study lies in its ability to connect market movement with decision-relevant insight.
For the complete dataset, detailed segmentation analysis, regional demand breakdowns, application-level valuation, and full supplier profiles, please access the full report through the source page. The executive summary presented here is designed to demonstrate the scope and analytical depth of the study while preserving the proprietary segmentation and directional intelligence that support informed commercial, engineering, and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Vacuum Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


