



PW Consulting: Rheology Modifiers Market Hits $11.45B in 2025, Poised to Reach $15.27B by 2032

The Rheology Modifiers Market in 2026: Navigating Growth, Compliance, and Competitive Complexity
Executive Overview
The global rheology modifiers market has entered a decisive phase of structural expansion, shifting from a period of steady organic growth to one defined by regulatory pressure, raw material volatility, and accelerated formulation innovation. With a 2025 baseline valuation of USD 11.45 billion and a projected valuation of USD 12.17 billion at the close of 2026, the market is on a clear trajectory toward USD 15.27 billion by 2032. At a compound annual growth rate of 4.2 percent across the forecast window, the sector is no longer moving at the pace of incremental capacity additions or routine product refreshes. It is being reshaped by the simultaneous forces of sustainability mandates, performance-driven reformulation, and strategic supply chain repositioning.
For market participants, 2026 is not a simple continuation of historical momentum. It is a year in which segmentation decisions, geographic prioritization, and product portfolio alignment will determine which firms capture disproportionate value and which face margin compression from compliance costs and feedstock uncertainty. The latest Rheology Modifiers Market research from PW Consulting has been built to equip strategic decision-makers with the analytical rigor required to navigate this environment. This article outlines the strategic architecture of the study and explains why its findings should be treated as essential input for 2026 planning cycles.
From Steady Expansion to Structural Realignment: Why 2026 Is a Deviation Year
The historical record from 2020 through 2025 reveals more than a smooth revenue curve. It documents a market that absorbed pandemic-era disruptions, navigated supply bottlenecks, and successfully scaled production to support a rising demand base across coatings, personal care, adhesives, and specialty industrial applications. The journey from USD 9.32 billion in 2020 to USD 11.45 billion in 2025 reflects both volume growth and the increasing technical deployment of rheology modifiers in formulations where viscosity control, suspension stability, and application behavior directly influence end-product performance and regulatory compliance.
Yet the forecast period introduces a more nuanced picture. Growth through 2032 will not be evenly distributed across all segments, nor will it be immune to external pressure points. The forecast profile shows a market that continues to expand but also encounters inflection points tied to regulatory alignment, raw material cost structures, and regional manufacturing footprints. A 4.2 percent CAGR may appear moderate in isolation, but in a market of this scale and technical complexity, it implies substantial absolute value creation and intensifying competition for high-growth pockets within paints and coatings, personal care, and emerging bio-based formulation pathways.
This is precisely why the research has been designed not merely as a top-line forecast tool, but as a decision framework for 2026. Firms that treat 2026 as a year of routine execution risk misallocating R&D, production capacity, and commercial resources. Firms that use the study to anticipate segment acceleration, regional demand migration, and formulation shifts will be better positioned to act before market signals become obvious.
What the Study Delivers: Actionable Intelligence Beyond the Headline Numbers
The full report is structured to translate macro trajectory into operational guidance. It begins with the historical baseline and forward projection, but its greater value lies in the depth of its segmentation logic, competitive mapping, and scenario-ready insights. Decision-makers can expect to access an integrated analysis that connects market size evolution to the underlying demand drivers, formulation trends, and regional dynamics that will shape procurement strategies, capacity investment decisions, and product roadmap planning throughout the forecast horizon.
Rheology Modifiers Market
Specifically, the study addresses several dimensions that are often fragmented across separate analyses:
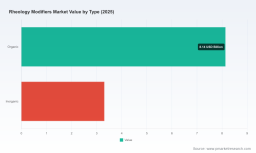
- A detailed review of market structure by type, including the relative positioning of organic and inorganic rheology modifier categories and their respective relevance to formulation requirements across major end-use industries.
- An application-level reading of demand concentration, highlighting where rheology modifiers are gaining share in core uses and where technical or regulatory friction is reshaping adoption velocity.
- A regional assessment that identifies where mature demand bases are stabilizing and where growth momentum is accelerating due to manufacturing expansion, regulatory transitions, and formulation modernization.
- An evaluation of market concentration and competitive intensity, offering context on how consolidated the landscape is and what that means for pricing behavior, differentiation, and supplier negotiation.
- A review of recent corporate developments, including product launches and capacity expansions, that signal where leading players are betting on future demand.
The report also integrates the external factors that are increasingly inseparable from market forecasts. Feedstock dynamics tied to crude oil price movements, evolving restrictions on synthetic polymer microparticles, VOC-related formulation shifts, and compliance demands linked to REACH, FDA, and food-contact considerations are addressed as market-shaping variables rather than peripheral noise. That means the analysis does not simply project demand; it places demand within the regulatory and cost environment that executives must actually manage.
Competitive Positioning: Where Leading Players Are Investing and Innovating
The competitive landscape is defined by a concentrated group of globally active chemical and specialty materials firms, each competing on technical performance, application specificity, regional presence, and sustainability alignment. The research provides a structured competitive scan of these players, with a focus on how product portfolios are being tailored to water-based, solvent-based, and solvent-free formulations, and how recent moves suggest broader strategic intent.
Among the firms profiled, BASF SE continues to build on a broad rheology modifier platform spanning RHEOVIS®, ATTAGEL®, ATTAFLOW®, and EFKA® products, with a clear emphasis on serving water-based, solvent-based, and solvent-free applications. The April 2025 announcement of a production line expansion for Rheovis HEUR thickeners in Nanjing, China signals a deliberate response to rising demand from architectural and industrial coatings markets. This type of capacity action is significant because it links product availability directly to regional growth dynamics rather than treating supply as a generic global function.
The Dow Chemical Company maintains a focused presence through ACRYSOL™ HASE rheology modifiers and PRIMAL™ RM-7 for latex coatings, positioning itself where performance consistency in latex-based systems remains a priority. Lubrizol Corporation is expanding in personal care and specialty Formulation through Solthix™ and Carbopol® rheology modifiers, and its May 2025 introduction of Arbalon® RC 76 cellulose liquid illustrates a continued push into cationic cellulose-derived solutions for personal care applications. These moves suggest that leading suppliers are not only defending core positions but also refining portfolios toward higher-value formulation niches.
Other major participants reflect similarly differentiated strategies. Elementis plc brings RHEOLATE® associative polyurethane thickeners and BENTONE® clay-based modifiers into competition, while Evonik Industries AG relies on AEROSIL® fumed silica and the TEGO® ViscoPlus series to articulate a performance-led value proposition. Clariant AG maintains a prominent personal care and coatings footprint with Hostagel™ and Aristoflex® lines, and its August 2025 launch of Aristoflex SUN underscores a recent focus on advanced sunscreen formulations with improved stability and SPF performance. Ashland Global Holdings Inc. continues to compete through Aquaflow™ nonionic synthetic associative thickeners and Natrosol® cellulosic products, reinforcing the breadth of its formulation support capabilities.
The competitive scan also includes firms that are shaping regional and application-specific demand with notable precision. Croda International Plc emphasizes high-performance rheology modifiers for aqueous and non-aqueous formulations. Münzing Chemie GmbH contributes TAFIGEL® PUR alongside HEUR/HASE associative modifiers. BYK-Chemie GmbH is active with fumed silica-based and associative additives. Arkema S.A. extends its offering with Coapur® and Rheostyl® waterborne modifiers. AkzoNobel N.V. competes in coatings and industrial applications with formulation-specific rheology solutions. San Nopco Co. rounds out the landscape with its SN-Thickener series polymer and associative modifiers. Taken together, these players illustrate that the market is not a simple contest of scale; it is one where technical differentiation, application specificity, and regional readiness increasingly determine commercial advantage.
The Regulatory and Cost Environment Reshaping Demand Signals
A defining feature of the 2026 outlook is that demand is being steered as much by compliance as by performance. In North America, EPA VOC limits for architectural coatings are accelerating the shift toward waterborne rheology modifiers with lower solvent content. This transition favors suppliers that can deliver effective thickening and suspension in waterborne systems without compromising application characteristics or dry-time behavior. In Europe, EU Regulation 2023/2055 on synthetic polymer microparticles is placing new constraints on certain associative thickeners, increasing the pull toward bio-based alternatives and more sustainable formulation architectures. At the same time, stringent restrictions on APEO-containing thickeners in both the EU and North America are pushing reformulation efforts toward options that satisfy environmental expectations while preserving performance.
Beyond regulation, raw material dynamics remain a critical planning variable. Volatility in crude oil prices directly influences feedstock costs for synthetic acrylic and polyurethane rheology modifiers used in coatings, making cost forecasting and formulation flexibility more important than ever. Meanwhile, escalating technical complexity across REACH and FDA compliance for food-contact applications means that product qualification cycles can become longer and more demanding. These factors do not eliminate growth; they reshape where growth is achievable and which suppliers can serve it efficiently.
This is why the research treats regulatory and feedstock conditions as integral inputs to the forecast environment rather than as disconnected background events. The analysis connects these pressures to operational implications: what they mean for reformulation roadmaps, how they alter the attractiveness of different product types, and where regional demand may shift as end-users adapt to new compliance realities.
Why the Study Is Strategic Input for 2026 Decision-Making
For executives, procurement leaders, R&D directors, and strategy teams, the value of this study lies in its ability to convert market trajectory into decision-ready context. In a market projected to rise from USD 11.45 billion in 2025 to USD 12.17 billion in 2026, and onward toward USD 15.27 billion by 2032, the immediate question is not whether growth exists. The question is where the most defensible growth will originate, which segments will face the steepest technical or regulatory barriers, and how competitive intensity will evolve as leading players align capacity and product portfolios with regional demand shifts.
Worldwide Rheology Modifier Coating Additive Market
The report is designed to support that decision process by clarifying the structural forces behind the numbers. It helps teams evaluate whether current portfolio exposure aligns with the fastest-moving application areas, assess which type categories are likely to gain relevance under evolving formulation and compliance conditions, and understand how regional dynamics may influence sourcing, production, and market-entry priorities. It also provides a competitive baseline that makes it easier to interpret new product launches, capacity announcements, and partnership activity as signals rather than isolated events.
In practical terms, the study supports a range of 2026 uses:
- Refining segment-level growth assumptions before committing to capacity, inventory, or commercial investment.
- Identifying formulation trends that may alter demand for organic versus inorganic rheology modifiers across core applications.
- Anticipating regional shifts tied to regulatory transitions and manufacturing expansion.
- Benchmarking competitive positioning against major global suppliers with differentiated product systems and recent market moves.
- Integrating regulatory and raw material risk into longer-term market planning rather than treating them as after-the-fact constraints.
Conclusion: Treat 2026 as a Year for Informed Strategic Positioning
The rheology modifiers market is entering 2026 with solid momentum, but also with heightened complexity. Growth is real, yet it is increasingly selective. Regulatory evolution is accelerating formulation change, feedstock volatility is complicating cost planning, and competitive players are responding with targeted capacity expansion and application-specific innovation. In this environment, broad market awareness is no longer enough. Decision-makers need a structured, evidence-based view of where value will be created, which segments will be most affected by external pressures, and how the competitive field is shifting beneath the headline numbers.
The full Rheology Modifiers Market research from PW Consulting provides that view. It combines historical context, forward-looking projections, segmentation insight, competitive profiling, and industry-context analysis into a single strategic framework intended for 2026 planning and beyond. The complete report contains the segmented detail, regional interpretation, application-level analysis, and executive recommendations necessary to turn market intelligence into action. For teams preparing for a year in which strategic precision matters more than ever, the research offers the depth required to move from observation to execution.
For detailed analysis of this topic, please visit the official page: Rheology Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


