



PW Consulting Report: Plastic Buckles Market Hits $534.1M in 2025, Projected 4.1% CAGR to $710M by 2032

Navigating the Plastic Buckles Market: Strategic Intelligence for 2026 Decision-Makers
In an era where supply chain resilience and material innovation dictate competitive advantage, the plastic buckles sector stands at a critical inflection point. As a senior strategic advisor at PW Consulting, I have witnessed how seemingly modest hardware components cascade into broader product performance, compliance readiness, and customer retention. Our latest market research on the Plastic Buckles Market delivers precisely the kind of actionable intelligence that procurement leaders, product engineers, and corporate strategists need to navigate the years ahead. Rather than offering static snapshots, this study maps the structural shifts, competitive pressures, and sustainability imperatives that will shape enterprise decisions throughout 2026 and beyond.
The global plastic buckles market has demonstrated steady, compounding growth over the past half-decade. Historical revenue tracking from 2020 through 2025 reveals a consistent upward trajectory, with total market size expanding from approximately 407.6 million USD at the start of the observation window to roughly 534.1 million USD by the base year of 2025. Building on this foundation, our forecast modeling projects the market to reach 569.62 million USD in 2026, accelerating toward a long-range valuation of 710.0 million USD by 2032. This progression reflects a compound annual growth rate of 4.1 percent across the 2026 to 2032 evaluation period. While headline figures establish a reliable baseline, the true strategic value of this research lies in unpacking the forces beneath the aggregate numbers: evolving end-use performance requirements, regional production realignments, and the rapid normalization of recycled polymer specifications. The report deliberately moves beyond surface-level sizing to equip executives with scenario-ready frameworks that inform capacity planning, supplier qualification, and product differentiation strategies.
Structural Segmentation and End-Use Evolution
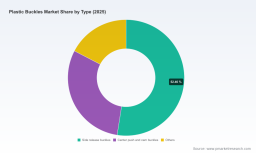
Market dynamics in the plastic buckles sector are increasingly defined by how different functional types align with specific application demands. Side-release mechanisms continue to command substantial market share, reflecting their dominant position across quick-detach fastening scenarios where reliability and user familiarity are paramount. Center-push and cam-style buckles maintain robust demand in applications requiring secure tension control and load-bearing consistency. Meanwhile, specialized and ancillary buckle variants serve niche but strategically important segments, often serving as differentiators in premium or highly regulated product lines. Understanding the interplay between these structural categories and their downstream utilization is essential for manufacturers designing for scale and specifiers evaluating total cost of ownership.
On the application side, the demand landscape spans diverse commercial environments. Outdoor and recreational equipment represents a major utilization channel, driven by growing consumer engagement in modular gear, adjustable harnesses, and weather-resistant accessories. The bags and luggage sector continues to exert significant pull, particularly as e-commerce logistics, travel recovery patterns, and premium carrying solutions reshape hardware specifications. Additional application verticals further diversify the revenue base, with industrial strapping, tactical equipment, and professional-use harnesses contributing meaningful volume. The research dissects how shifting product architectures, material weight targets, and performance certifications are altering the relative attractiveness of each application pathway, enabling enterprises to prioritize high-conviction segments without overcommitting to oversaturated niches.
Regional Dynamics and Supply Chain Reconfiguration
Geographic distribution of demand and manufacturing capacity has become a decisive factor in sourcing strategy. North America and Europe maintain mature, specification-driven markets where compliance rigor, brand reputation, and lifecycle durability heavily influence purchasing decisions. Asia Pacific, meanwhile, represents a substantial and rapidly evolving commercial zone, characterized by strong domestic consumption, expanding export-oriented manufacturing, and increasing localization of product development. Latin America and the Middle East and Africa collectively form an emerging demand layer, where infrastructure development, growing trade corridors, and cost-sensitive procurement practices create distinct entry and expansion considerations.
For enterprise leaders, the strategic question is no longer where demand exists, but how regional cost structures, logistics constraints, and trade accessibility intersect with product requirements. The report evaluates how production footprints, material availability, and regional regulatory expectations influence total landed cost and time-to-market. Businesses operating across multiple geographies will find the analysis particularly useful for balancing standardization against regional customization, optimizing supplier diversification, and anticipating where manufacturing capacity is likely to shift over the forecast horizon. Rather than presenting a static regional breakdown, the study emphasizes the operational implications of geographic variation and provides decision-makers with a framework for aligning sourcing strategies with long-range commercial priorities.
Competitive Landscape and Strategic Positioning
The plastic buckles market remains moderately concentrated, with a small group of diversified manufacturers holding outsized influence over pricing norms, specification standards, and sustainability expectations. The top three players account for approximately 55 percent of market revenue, while the top five collectively represent around 75 percent. This concentration does not imply uniform competition; instead, it reflects differentiated business models, varying engineering capabilities, and distinct approaches to regional coverage. Understanding where each incumbent competes, how they differentiate, and where they are investing provides crucial context for both incumbents defending share and new entrants evaluating positioning.
Nifco Inc., headquartered in Japan, has established a strong reputation in plastic side-release buckles, quick-release mechanisms, bungee cord locks, and industrial fasteners, with an increasingly visible commitment to sustainable materials and GRS-certified options. Its recent operational moves underscore a broader industry shift toward integrated environmental accountability. In December 2024, Nifco Taiwan completed the installation of a new solar roof to power its plastic buckle manufacturing processes, and by February 2025 the company launched next-generation bungee cord locks featuring ergonomic designs and sustainable materials. These developments are not isolated product updates; they signal an institutional alignment between manufacturing energy use, material sourcing, and final product performance. Nifco's plastic buckles and fasteners are also compliant with updated EU standards through the use of 100 percent recycled Nylon PA6 and 30 percent recycled POM, an important reference point for buyers navigatingEuropean regulatory expectations.
American Cord & Webbing Co., Inc. operates from the United States with continuous injection molding capabilities spanning military, industrial, and commercial markets. Its profile demonstrates the value of flexible capacity and broad specification coverage in sectors where lead time reliability and certification readiness matter as much as unit economics. ITW Nexus develops and manufactures standard plastic buckles and closure components, including cam, side-release, roller, and ladder types, with production distributed across the US, Europe, and Asia. This multi-regional manufacturing footprint provides an illustrative example of how scale, geographic reach, and standardized portfolios support stable supply in globally distributed product categories.
Plastic Buckles Market
YKK Corporation remains a recognized supplier of plastic buckles, zippers, and fastening solutions for apparel, outdoor gear, and medical devices, including its GreenRise biodegradable series. Its presence highlights how fastening hardware increasingly crosses into adjacent product ecosystems where material biodegradability, traceability, and brand trust carry strategic weight. In Taiwan, Shin Fang Plastic Industrial Co., Ltd. produces plastic side-release, quick-release, and center-release buckles alongside related hardware, maintaining ISO 9001:2008 certification across its production operations. BroadPlast Taiwan specializes in side-release, instant-release, and seat-belt style buckles for bags, straps, and industrial use, reflecting the competitive depth found within regional manufacturing hubs. The John Howard Company contributes Berry-compliant hardware and plastic buckles for outdoor, tactical, and industrial applications, illustrating how compliance profiles can define market access in regulated procurement environments.
Further reinforcing the breadth of the competitive field, Zhongshan Jimei Handbag Part Co., Ltd. manufactures handbag and luggage plastic buckles and fasteners, while KAM Garment Accessories supplies plastic buckles and garment accessories for apparel and fashion markets in Taiwan and across APAC. Duraflex, operating in the APAC region, produces plastic hardware and buckles for bags, pet straps, strapping, and webbing. These companies collectively demonstrate that competition in this market is not limited to large multinational players; it also includes specialized manufacturers that compete on application expertise, regional responsiveness, and price-to-performance calibration.
The report places these organizations within a structured competitive lens, examining how sustainability investments, certification portfolios, and manufacturing flexibility shape buyer preference. It also addresses the broader industry context: the increasing adoption of GRS-certified recycled plastics by multiple manufacturers, the role of ISO 9001:2008 certification in stabilizing quality perception, and the way energy and material initiatives are becoming embedded in supplier evaluation criteria. For commercial teams, these dynamics matter because they directly influence qualification cycles, cost modeling, and long-term supply continuity.
Material Innovation, Compliance, and Operational Resilience
Sustainability is no longer a peripheral consideration in the plastic buckles market; it is becoming a procurement prerequisite. Recycled polymer specifications, lifecycle documentation, and energy-efficient manufacturing are increasingly used as screening criteria by distributors, brand owners, and regulated procurement departments. The research explores how GRS-certified recycled content, recycled Nylon PA6, and recycled POM are transitioning from differentiators to baseline expectations in several key markets. At the same time, it acknowledges the practical complexities of adopting these materials at scale, including availability constraints, processing consistency, and the need to maintain mechanical performance under real-world load conditions.
Regulatory and certification environments further complicate decision-making. Updated EU standards, Berry compliance, and quality management certifications such as ISO 9001:2008 all play roles in shaping market access and buyer confidence. The study does not treat compliance as a one-time checkbox; instead, it examines how evolving standards interact with product design, supplier audits, and documentation requirements across multiple application segments. By integrating these considerations into a broader commercial framework, the report helps organizations anticipate where compliance exposure is likely to increase and where early adaptation can translate into competitive advantage.
What the Research Delivers for 2026 Planning
Our Plastic Buckles Market study is designed for leaders who need more than top-line projections. It delivers a structured, application-ready body of analysis that connects market sizing to operational reality. The report includes detailed examination of demand drivers, restraint factors, and growth catalysts across the 2026 to 2032 forecast period. It maps how different buckle types and application channels are expected to evolve, and it translates those trajectories into implications for sourcing, specification, and product development. The analysis also addresses competitive positioning, regional manufacturing dynamics, and the strategic role of sustainability credentials in supplier selection.
Plastic Caps Market
Practically, the study supports a range of decision-making scenarios: evaluating whether to standardize components across product lines or maintain region-specific variants; identifying where supplier diversification can reduce exposure to capacity or compliance risk; assessing how recycled material adoption may affect unit economics and qualification timelines; and determining which application segments offer the strongest balance of volume potential and specification differentiation. The report is structured to help both strategic planning teams and operational stakeholders connect market intelligence to concrete next steps.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Plastic Buckles Market is evolving in ways that reward foresight. Steady growth, shifting application requirements, regional supply realignment, and the normalization of sustainable material standards all point to a market where informed positioning will separate resilient operators from reactive followers. With a base year established at 2025, a forecast window spanning 2026 through 2032, and a projected CAGR of 4.1 percent, the commercial opportunity is real but increasingly conditional on execution quality. Success will depend on how well organizations can read structural change, qualify suppliers against future requirements, and align product architecture with durable demand signals.
This research has been built to serve that purpose. It provides the depth required to support credible decisions, while preserving the proprietary segmentation detail, scenario modeling, and granular market splits that give the full study its strategic edge. To access the complete dataset, regional and application-level breakdowns, and the full competitive profiling framework, we invite you to visit the source page and download the full report. In a market where timing, compliance readiness, and supplier strategy increasingly determine outcomes, having the complete intelligence landscape is not optional; it is the foundation of effective 2026 planning.
For detailed analysis of this topic, please visit the official page: Plastic Buckles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


