



PW Consulting: Animal Model Services Market Hits $367.7M in 2025, Expects 6.75% CAGR to 2032

Navigating Uncertainty: Strategic Intelligence in the Animal Model Services Market Through 2032
In an era where drug development timelines are compressing and regulatory landscapes are shifting beneath the feet of even the most established biopharmaceutical players, the choice of preclinical partners has never been more consequential. The animal model services sector stands at a critical inflection point. While the foundational role of in vivo models in drug discovery and toxicology remains undisputed, the market is being reshaped by parallel forces: escalating compliance costs, the rise of human-relevant alternatives, and a wave of technological integration that is redefining what service providers can deliver. For executives planning capital allocation, partnership strategy, or R&D outsourcing through 2032, a granular understanding of this ecosystem is no longer optional—it is a strategic imperative.
This analysis draws on the latest PW Consulting market intelligence to frame the strategic contours of the animal model services landscape. What follows is not a mere data dump, but a decision-oriented perspective designed to help leadership teams ask the right questions, identify vulnerability, and position their organizations ahead of the curve.
Market Trajectory and the 2026 Decision Window
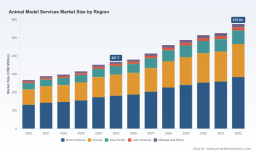
The animal model services market has demonstrated consistent expansion over the past half-decade, with revenue scaling from approximately 267.41 million USD in 2020 to an estimated 367.7 million USD in 2025. That trajectory reflects more than baseline demand; it signals structural investment in preclinical infrastructure by both contract research organizations and integrated pharmaceutical enterprises. Looking forward, the forecast period from 2026 through 2032 projects a compound annual growth rate of 6.75 percent, with market valuation expected to surpass 575.84 million USD by the close of the decade.
For strategic planners, the numbers themselves are only the starting point. The more valuable insight lies in the pacing and composition of growth. Historical momentum has been robust, but the 2026-2032 window introduces new variables—cost pressure, regulatory recalibration, and competitive consolidation—that will separate providers who merely supply models from those who deliver integrated, decision-ready preclinical platforms. The 2026 baseline, pegged at 380.12 million USD, represents the first full year in which several of these dynamics will be fully priced into procurement decisions, contract negotiations, and long-term capacity planning.
Executives should treat this forecast not as a guarantee of linear expansion, but as a map of where value will concentrate. Growth will not be uniform across applications, species, or geographies. Organizations that understand which segments will absorb incremental investment—and which will face margin compression—will be better equipped to structure partnerships, negotiate service-level agreements, and prioritize internal capabilities.
Regulatory Headwinds and the Reshaping of Demand
No discussion of the animal model services market in 2026 can bypass the regulatory environment. Two policy signals stand out. In July 2025, the National Institutes of Health announced that it would no longer issue Notices of Funding Opportunity exclusively supporting animal model systems, mandating instead that new funding mechanisms support human-focused approaches such as clinical trials or new approach methods (NAMs), while excluding animal-only proposals. Around the same period, in April 2025, the Food and Drug Administration outlined plans to phase out animal testing requirements for monoclonal antibodies and other drug classes, accelerating the adoption of organoids and human-relevant methodologies.
Worldwide Animal Workstation Market
These moves do not eliminate the need for animal models, but they reframe their role. Animal systems are increasingly positioned as one component within a broader evidence-generation toolkit, rather than the default pathway for every research question. For service providers, this means the value proposition must evolve from volume and availability toward translational relevance, data integration, and methodological flexibility. Sponsors, meanwhile, are scrutinizing which studies genuinely require in vivo models and which can be shifted to alternative platforms—creating both pressure and opportunity for those who can demonstrate rigorous justification and complementary capabilities.
Compounding the regulatory dynamic is the cost environment. Sector analysis from 2025 indicates that animal research costs have risen by 12 to 18 percent, driven by compliance requirements, environmental enrichment standards, and facility upgrades. Stricter animal welfare guidelines and 3Rs initiatives across the EU and US have further increased operational and validation expenses, even as they spur adoption of AI-assisted phenotyping and organoid alternatives. These cost pressures will influence which providers can sustain competitive pricing and which will need to differentiate through specialized expertise or technology-enabled efficiency.
It is worth noting that regulatory scrutiny also carries direct compliance implications. In October 2024, Inotiv agreed to pay more than 35 million USD to resolve Animal Welfare Act violations involving dog breeding, with ongoing compliance monitoring and public posting of USDA inspection reports. Such episodes underscore that operational integrity is now a competitive variable, not merely a back-office concern. Sponsors are increasingly factoring audit history, transparency practices, and welfare compliance into vendor selection, particularly for long-term or high-value programs.
Competitive Architecture and Strategic Positioning
The market is moderately concentrated, with the top three providers accounting for 46.3 percent of revenue and the top five capturing 65.8 percent. This concentration reflects the scale advantages of established players who can amortize the cost of genetically engineered model portfolios, breeding infrastructure, and quality systems across a broad client base. Yet the landscape is not static. Specialized firms are carving out defensible positions through technology depth, disease-area focus, or geographic proximity to emerging biopharmaceutical clusters.
Among the leaders, Charles River Laboratories operates as a global provider of research animal models, genetically engineered models, contract breeding, and preclinical services spanning basic research, drug discovery, and development. Its scale and breadth make it a default consideration for many sponsors, but the company is also investing in decision-support tools, including the September 2025 launch of the Patholytix Foresight AI-powered platform for toxicologic pathology. This type of integration—pairing traditional model supply with analytics that accelerate interpretation—illustrates the direction in which the market is moving.
Taconic Biosciences, headquartered in Germantown, New York, specializes in genetically engineered rodent models, humanized mice, microbiome-defined models, and integrated breeding and phenotyping services tailored to cell and gene therapy as well as immunotherapy research. The Jackson Laboratory, based in Bar Harbor, Maine, operates as a non-profit provider of genetically engineered mouse models, genomic resources, and services that support precision medicine and disease research, leveraging its academic pedigree and open-science orientation to serve both industry and research communities.
In Europe, genOway, based in Lyon, provides custom transgenic mouse, rat, and cell line models using CRISPR and homologous recombination technologies for pharmaceutical and academic research. Its February 2026 announcement of a novel mouse model for antibody therapy prediction in cancer and inflammatory diseases signals a focus on translational relevance in high-value therapeutic areas. Janvier Labs, located in Saint-Berthevin, France, supplies conventional, transgenic, and knockout rodent models under stringent health and genetic standards, complemented by breeding and maintenance services—an emphasis on quality and consistency that resonates with sponsors navigating rigorous regulatory expectations.
On the contract research side, Crown Bioscience, situated in San Diego, California, offers translational oncology and immuno-oncology platforms, in vivo models, and full-service preclinical development solutions. The firm has pursued a multi-pronged expansion strategy: opening a new model development center in Kannapolis, North Carolina in September 2025, securing CAP accreditation for its San Diego laboratory in January 2026 on top of existing CLIA certification, and earning recognition as the best preclinical oncology CRO in the Healthcare and Pharmaceutical Awards 2025. These moves reflect a deliberate effort to deepen capabilities and credentials in a segment where sponsors demand both scientific rigor and operational readiness.
Inotiv, headquartered in Lafayette, Indiana, provides comprehensive research models, genetically engineered models, contract breeding, surgical services, and health and genetic monitoring. Its June 2025 release of the 2025-2026 research models and services product guide, with updated pricing, illustrates the ongoing attention to catalog clarity and commercial transparency that sponsors rely on when comparing options. Harbour BioMed, based in Natick, Massachusetts, develops Harbour Mice transgenic models for antibody therapeutics and immune-oncology research, integrated with antibody discovery platforms—an example of a company aligning model supply with a specific therapeutic workflow. Hera BioLabs, operating in the United States, focuses on SRG rat models such as ImmunoRat and OncoRat for xenograft oncology and humanized models, leveraging gene-editing technologies to address niches where rat physiology offers advantages over murine systems.
The Asia-Pacific region contributes a growing set of capable providers. GemPharmatech, in Nanjing, China, supplies genetically engineered mouse models exceeding 25,000 lines, along with custom model generation, preclinical testing, and breeding services. Its March 2026 publication of new preclinical models and applications for ADC resistance, asthma, and heart failure research highlights a focus on expanding the translational utility of its portfolio. Shanghai Model Organisms Center, also based in Shanghai, offers lab animal models including development, breeding, phenotyping, and custom services with OLAW and NIH compliance, an important consideration for sponsors that need documentation standards aligned with US regulatory expectations. Pharmaron, headquartered in Beijing, operates as a global CRO providing medical device and in vivo pharmacology animal model services alongside drug discovery platforms, while Eurofins Scientific, based in Luxembourg, delivers an integrated preclinical CRO offering pharmacology, toxicology, and bioanalysis services using validated animal models for pharmaceutical and biotech clients.
For decision-makers, the competitive question is not simply who is largest, but who is aligned with the specific technical, regulatory, and timeline requirements of a given program. The concentration figures indicate that scale players command significant share, but the recent developments referenced above—accreditations, facility expansions, product launches, and publications—show that differentiation is accelerating. Providers are competing on more than model availability; they are competing on the speed, quality, and interpretive depth of the entire preclinical package.
Application Realities and the Evolution of Service Bundles
Demand across application areas is uneven, and that unevenness carries strategic implications. Drug discovery remains the dominant use case, reflecting the enduring need to evaluate target engagement, efficacy signals, and pharmacokinetic behavior in living systems before advancing candidates. Toxicology studies form the next major pillar, driven by regulatory expectations and the necessity of characterizing safety margins. Disease modeling and genetic research represent more specialized but high-value segments, often tied to precision medicine initiatives, mechanism-of-action studies, and the development of novel therapeutic modalities. Biomedical research, while smaller in relative terms, supports foundational work that can underpin long-term pipeline value.
What is changing is the way these applications are served. Sponsors increasingly expect providers to offer more than a catalog of models; they want integrated workflows that connect model selection, breeding, phenotyping, data capture, and interpretation. The rise of AI-assisted phenotyping, for instance, responds to both cost pressure and the need for higher-resolution readouts. At the same time, the availability of human-relevant alternatives is prompting sponsors to justify each animal study more rigorously, which in turn raises the bar for providers to demonstrate that their models are fit for purpose and that the data generated will withstand regulatory and internal scrutiny.
This environment rewards providers that can articulate clear scientific rationale, maintain robust quality systems, and adapt to evolving compliance expectations. It also rewards sponsors that take a portfolio approach—matching the right model to the right question, using alternatives where appropriate, and preserving in vivo capacity for studies where it adds irreplaceable value. The market is not contracting, but it is becoming more selective, and selectivity favors those who can make defensible, evidence-based choices.
Animal Model Services Market
What the Full Study Delivers for 2026 Planning
The PW Consulting Animal Model Services Market study is designed to translate these dynamics into actionable intelligence. Beyond the headline growth trajectory and the 2026 baseline, the report provides a detailed examination of segmentation logic, competitive moves, and the regulatory and cost factors that will shape procurement and partnership decisions over the forecast period. It maps the capabilities of key providers, tracks recent developments that signal strategic direction, and contextualizes the market within the broader shift toward human-relevant methods and technology-enabled preclinical workflows.
For teams preparing 2026 budgets, vendor evaluations, or R&D outsourcing strategies, the study offers a structured view of where concentration is high, where specialization creates leverage, and where regulatory and cost trends are likely to alter the economics of animal model services. It is built to support scenario planning—helping leadership teams anticipate how changes in funding policy, accreditation status, facility capacity, or model availability might affect program timelines and cost structures. The objective is to equip decision-makers with a precise, decision-grade understanding of the market so that they can negotiate from a position of knowledge rather than assumption.
Conclusion: Precision in a Transforming Preclinical Economy
The animal model services market will continue to grow through 2032, but growth alone will not define success. The organizations that thrive will be those that navigate regulatory recalibration, absorb cost pressure without sacrificing quality, and deliver preclinical value that is both scientifically rigorous and operationally transparent. For sponsors, the imperative is to select partners whose capabilities align with the specific demands of each program and whose track records demonstrate compliance, consistency, and interpretive depth. For providers, the imperative is to differentiate through technology integration, disease-area expertise, and the ability to justify the role of animal models within a broader, increasingly human-relevant evidence ecosystem.
The full PW Consulting report provides the detailed segmentation, competitive analysis, and forward-looking context needed to make those judgments with confidence. The strategic window for 2026 is open now, and the decisions made in the coming months will shape preclinical capacity, partnership economics, and pipeline velocity well into the next decade.
For detailed analysis of this topic, please visit the official page: Animal Model Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


