



PW Consulting: Parking Meter Market to Reach $7.64M by 2032, Growing at 3.76% CAGR

Navigating the 2026 Parking Meter Market: Strategic Intelligence for Long-Term Growth
The global parking infrastructure sector stands at a critical inflection point. Municipalities are no longer treating curb management as a static revenue function; they are redesigning it as a dynamic, data-driven component of urban mobility. For executives, procurement leaders, and investment committees operating in this space, the difference between reactive positioning and proactive strategy lies in the quality of intelligence available at the planning table. PW Consulting’s latest Parking Meter Market research was constructed precisely for that moment. It translates macro-level trajectory, competitive fragmentation, and operational shifts into an actionable framework for decisions that will shape portfolios through 2032 and beyond.
Why 2026 Demands a Refined View of the Curb Economy
Over the past half-decade, the market has moved from incremental hardware upgrades to systemic re-architecting. Historical revenue data from 2020 through 2025 illustrates a steady expansion, moving from a base of 4.87 million USD to 5.9 million USD by 2025. That progression reflects more than population growth or inflationary pass-through. It captures a concerted shift in how cities price access, how operators manage enforcement, and how payment ecosystems have migrated from isolated coin mechanisms to integrated, remotely managed platforms.
The forecast horizon through 2032 projects continued expansion, with the market anticipated to reach approximately 7.64 million USD by the close of the period. The implied compound annual growth rate of 3.76 percent may appear measured on the surface, yet in a capital-intensive, regulation-sensitive hardware and software market, that pace carries disproportionate strategic weight. It signals durable demand for modernized metering infrastructure, sustained municipal procurement cycles, and a widening aperture for smart-curb integrations that bridge on-street and off-street revenue streams. The real question for leadership teams is not whether the market will grow, but which segments, geographies, and operational models will capture the disproportionate share of that growth.
Structural Insights Embedded in the Research
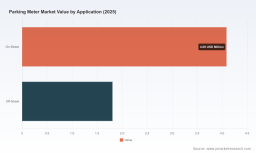
A market of this character cannot be navigated through aggregate headlines alone. The report dismantles the overall trajectory into the operational and commercial dimensions that actually drive procurement cycles, deployment priorities, and vendor selection. It examines how metering solutions are bifurcated between single-space and multi-space architectures, why the balance between those configurations is shifting as cities pursue centralized management and dynamic pricing, and how on-street versus off-street applications create distinct demand profiles for hardware durability, payment flexibility, and enforcement integration.
Regional dynamics receive dedicated scrutiny because municipal procurement, labor environments, and digital-payment maturity differ sharply across territories. The research maps how established markets with entrenched metering networks are approaching replacement cycles, while emerging municipal adoption patterns in other regions are reshaping the deployment pipeline. Rather than presenting static splits, the analysis ties geographic variation to underlying drivers—regulatory frameworks, municipal budgeting rhythms, national purchasing agreements, and the pace of cashless adoption—to help decision-makers anticipate where demand will concentrate and where competitive pressure will intensify.
Equally important, the report addresses market structure. With a CR3 concentration of 38.4 percent and a CR5 concentration of 55.2 percent, the competitive landscape is neither a monolithic oligopoly nor a purely fragmented field. That middle-ground structure matters. It indicates the presence of influential incumbents with differentiated smart-curb portfolios, alongside a set of regional and specialized players that compete on manufacturing provenance, contract accessibility, and integration depth. For organizations evaluating partnerships, tenders, or organic product roadmaps, understanding where concentration genuinely exerts pricing and distribution power—and where it does not—is essential to resource allocation.
Competitive Architecture: Who Shapes the Field and How
The strategic value of vendor intelligence lies in recognizing not only who competes, but how their offerings map to municipal requirements and end-user expectations. The report profiles a cross-section of companies whose portfolios define the current competitive frontier.
- IPS Group, headquartered in San Diego, California, anchors its position on single-space meters coupled with real-time data capture, remote management, and an integrated smart parking ecosystem. Its trajectory reflects a broader industry movement toward curb platforms that extend beyond the meter itself into centralized management and enforcement workflows.
- J.J. MacKay Canada Limited, based in Ajax, Ontario, emphasizes parking meter solutions supported by national purchasing contracts and a product catalog designed for both on-street and off-street applications. Its approach highlights how procurement leverage and catalog breadth can shape municipal buying patterns, particularly where coordinated purchasing frameworks reduce administrative friction.
- Parking BOXX Inc., operating from Beaverton, Oregon, focuses on parking control systems, pay stations, and equipment tailored to surface lots and garages, complemented by cloud management software. Its positioning underscores the continued relevance of off-street revenue environments and the importance of software layers that unify multi-site operations.
- POM Inc., headquartered in Russellville, Arkansas, manufactures electronic parking meters that integrate coin, smart card, and mobile payments within a USA-based production environment. For buyers where supply-chain provenance, certification rigor, and diversified payment acceptance are decisive, that combination carries strategic weight.
- METRIC Group Ltd, based in Swindon, United Kingdom, provides parking terminals, pay-and-display machines, and management systems for on-street and off-street use. Its product breadth reflects the European preference for versatile terminal architectures that can be configured across varied municipal contexts.
- LocoMobi Inc., located in Toronto, Ontario, advances smart transportation and parking management systems with mobile payments and an AI-powered cloud portal. Its recent activity demonstrates how cloud-first management, manufacturing localization, and city-wide deployments are becoming interlocking pillars of competitive differentiation.
- Ventek International, based in the United States, specializes in automated pay stations and digital parking meters oriented toward revenue collection and on-street enforcement. Its emphasis on automation and enforcement alignment speaks to the operational priorities of agencies seeking to protect revenue integrity.
- Hectronic GmbH, headquartered in Bonndorf, Germany, builds smart parking machines with smartphone-like touch interfaces and cashless payment solutions, reinforced by high-security bank authentication. That orientation highlights a market segment where payment trust, user experience, and compliance rigor converge.
- SKIDATA AG, from Sankt Johann im Pongau, Austria, delivers digital curbside parking solutions, including the Skiosk family and integrated mobility systems. Its approach illustrates how app-based payment flows and license-plate recognition enforcement can reduce hardware dependency while expanding the functional scope of curbside management.
These profiles are not isolated snapshots. The report contextualizes them against recent developments that signal where each organization is strengthening its competitive stance. IPS Group’s November 2025 website relaunch elevated its parking and curb management narrative around an integrated smart parking ecosystem. LocoMobi’s September 2025 announcement of full manufacturing relocation to Canada, followed by its April 2026 commissioning of city-wide meters and its WorldStream cloud portal in Barrie, Ontario, reflects a deliberate alignment of production geography, cloud infrastructure, and municipal-scale deployment. ParkChicago’s January 2026 launch of app and pay boxes for on-street parking with mobile pay options illustrates how municipal programs continue to push mobile payment adoption into the field. Together, these movements reveal a competitive environment where product launches, manufacturing decisions, and city-wide installations are being used to consolidate market presence rather than merely announce features.
Parking Meter Market
Operational and Regulatory Forces Reshaping Deployment Decisions
A forecasting model alone cannot capture the forces that alter procurement timing, vendor selection, and total cost of ownership. The research weaves in current operational realities that are actively shifting the decision calculus for municipalities and their suppliers.
Regulatory and procurement events are already redrawing local timelines. The closing of Boston’s parking meter implementation services bid in February 2026, for example, is a reminder that municipal tenders do not merely purchase hardware; they reset competitive access, define integration expectations, and influence regional demand pipelines. For organizations tracking pipeline visibility, such events are early indicators of where deployment capital will flow and which capabilities will be required to win.
Supply-chain provenance and purchasing structures are equally consequential. POM’s ISO 9001-certified USA manufacturing facility in Russellville, Arkansas, and MacKay Meters’ national purchasing contract via OMNIA Partners for US customers demonstrate two distinct routes to procurement advantage. One route competes on certified domestic production and quality assurance; the other competes on aggregated purchasing power and contract accessibility. Both matter because municipal buyers increasingly weigh operational continuity, compliance assurance, and administrative efficiency alongside unit pricing.
Water Meter Market
Payment security and enforcement technology are also redefining the value proposition of metering hardware. Hectronic’s emphasis on high-security bank authentication for cashless payments points to a segment where transaction trust and fraud resistance are becoming procurement criteria in their own right. Meanwhile, SKIDATA’s digital curbside approach, which leverages app payments and license-plate recognition enforcement to reduce hardware costs, illustrates an alternative trajectory in which software, enforcement, and mobile payment layers absorb functions traditionally assigned to physical meter arrays. For decision-makers, these are not merely product variations; they are competing philosophies about how revenue integrity and operational cost should be balanced.
Transforming Intelligence into 2026 Decision-Qualifying Action
Market research earns its place in executive planning only when it connects directly to the choices teams face in the near term. The Parking Meter Market report is structured to support that transition. It gives leadership a defensible basis for questions that determine pipeline quality, product-roadmap alignment, and risk exposure:
- Which application environments—on-street or off-street—are likely to command the most resilient demand under current municipal budgeting and enforcement priorities, and what capability gaps must be closed to compete in each?
- How should organizations interpret the balance between single-space and multi-space deployments as cities pursue centralized management, dynamic pricing, and integrated enforcement?
- Where does market concentration genuinely influence pricing, channel access, and replacement cycles, and where do regional and specialized players retain enough differentiation to compete on contract structure, manufacturing provenance, or integration depth?
- What do recent product launches, manufacturing relocations, and city-wide installations signal about the capabilities that will separate winning vendors from the rest of the field over the next several procurement cycles?
- How should teams weight payment flexibility, cloud management, enforcement integration, and security authentication when evaluating total cost of ownership rather than headline hardware price?
In a market where the average growth trajectory is steady but the underlying drivers are diverse, the organizations that outperform will be those that allocate capital and R&D against the most durable demand signals rather than the loudest product announcements. That requires visibility into how regional procurement patterns, application-level deployment needs, and competitive positioning interact across the forecast horizon. It also requires an honest appraisal of where concentration shapes the market and where fragmentation creates openings for differentiated offerings.
Accessing the Full Intelligence Architecture
Aggregate figures and company profiles provide the surface of the analysis, but the strategic granularity that supports tender strategy, product planning, and investment prioritization resides in the full report. The complete research offers a structured dissection of market size evolution across historical and forecast years, a deeper examination of how type, application, and regional dynamics interact to shape demand, and detailed competitive profiling that ties each company’s offering to the operational problems municipal buyers are actively trying to solve. It also connects recent product launches, manufacturing moves, and procurement events to the forward-looking implications they carry for pipeline visibility and competitive access.
For teams preparing 2026 decisions—whether those decisions involve vendor selection, geographic expansion, product roadmap adjustments, or partnership strategy—the full report functions as a decision-support backbone rather than a static market snapshot. It is designed to be referenced in planning cycles, procurement reviews, and investment committees where the cost of misreading the market is measured in lost contracts, misallocated development spend, or exposure to shifting regulatory expectations.
The Parking Meter Market is expanding with measured consistency, but the competitive and operational context surrounding that expansion is evolving rapidly. Municipalities are rethinking curb revenue as part of broader mobility strategies. Vendors are aligning manufacturing, cloud platforms, and enforcement integrations to capture that shift. Payment security, procurement contracts, and digital enforcement are becoming decisive evaluation criteria. In that environment, strategic advantage belongs to those who can see not only how large the market is, but how its structure, concentration, and dynamics are likely to behave across the 2026–2032 horizon. The full research delivers that view.
For detailed analysis of this topic, please visit the official page: Parking Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


