



PW Consulting Forecasts Cryogen Free Dilution Refrigerators Market to Hit $290M by 2032 at 8.5% CAGR

The Strategic Imperative: Navigating the Cryogen Free Dilution Refrigerators Market in 2026
In the rapidly evolving landscape of deep-tech infrastructure, the ability to maintain ultra-low temperatures without the logistical burden of liquid cryogens has shifted from a scientific aspiration to a commercial imperative. As we stand at the threshold of a new forecast period spanning 2026 to 2032, the demand for Cryogen Free Dilution Refrigerators is no longer niche. It is becoming a foundational element for industries pushing the boundaries of quantum mechanics, material science, and low-temperature detection.
This article serves as a strategic preview to our latest comprehensive market research. Our analysis is designed not merely to report numbers, but to equip enterprise leaders, investment strategists, and technology procurement officers with the intelligence required to make critical decisions in 2026. The transition toward cryogen-free systems represents a fundamental shift in operational expenditure, laboratory design, and scalability. Understanding the trajectory of this market is essential for any organization positioning itself within the quantum ecosystem or advanced research sectors.
Our recent market intelligence indicates a robust growth trajectory. The global market value, measured in USD Million, has demonstrated a consistent upward trend from a base valuation of 135.0 in 2020. By 2025, this figure has climbed to 182.0. Looking forward, the forecast suggests sustained momentum, with projections reaching 197.46 in 2026 and escalating toward 290.0 by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 8.5 percent over the forecast period. These figures are more than indicators of sales volume; they represent the increasing capital allocation toward technologies that eliminate the reliance on liquid helium, thereby reducing operational costs and environmental constraints.
The strategic value of this research lies in its granularity. While the top-line figures establish the market's vitality, the true decision-making power comes from dissecting the drivers behind this expansion. Enterprise leaders need to understand where the growth is concentrated, which technological specifications are driving procurement, and how the competitive landscape is solidifying. Our report delves into these layers, offering a roadmap for navigating the complexities of the supply chain and the technological requirements of end-users.
Market Dynamics and Growth Drivers
The expansion of the Cryogen Free Dilution Refrigerators market is inextricably linked to the broader advancements in quantum technologies. As quantum computing moves from experimental physics to engineering reality, the infrastructure supporting it must be reliable, scalable, and accessible. The shift away from liquid cryogen-dependent systems is driven by the need for continuous operation and reduced maintenance overhead. Laboratories and industrial facilities are increasingly prioritizing systems that offer stability without the logistical challenges of cryogen delivery and storage.
Our analysis highlights that the demand is not uniform across all temperature specifications. The market segmentation by base temperature reveals distinct preferences aligned with specific application needs. Systems capable of achieving base temperatures below 10mK dominate the current revenue landscape, reflecting the stringent requirements of high-fidelity quantum computing and sensitive qubit operations. However, there is significant traction in the segments covering base temperatures between 10-20mK and above 20mK. These ranges cater to a broader array of scientific instruments and material testing environments where ultimate cooling power is balanced against cooling capacity and system footprint.
Furthermore, the application landscape is diversifying. While quantum computing remains the primary catalyst for market value, material science research and low-temperature detection systems are significant contributors. The versatility of cryogen-free dilution refrigerators allows them to serve as multi-purpose platforms within advanced research facilities. This diversification mitigates risk for manufacturers and provides procurement officers with more options depending on their specific thermal and vibration requirements. The forecast period suggests that these applications will continue to mature, driving volume and encouraging further innovation in cooling power and integration capabilities.
Competitive Landscape and Strategic Positioning
The market structure for Cryogen Free Dilution Refrigerators is characterized by a mix of specialized innovators and established scientific instrument manufacturers. Our report provides an in-depth profiling of key companies that are defining the competitive standards. Understanding the positioning of these players is critical for enterprises evaluating supply chain resilience and technology partnerships.
Among the leaders is Bluefors Oy, headquartered in Helsinki, Finland. Bluefors has established a strong reputation for manufacturing measurement systems integrated with dilution refrigerators, including their LD and XLD series. Their focus on ultra-low temperature cooling to the millikelvin range makes them a pivotal partner for quantum computing initiatives requiring high stability. Similarly, Quantum Design Oxford, based in the United Kingdom, offers the Proteox series, which includes various models like ProteoxS and Proteox5mK. Their product line demonstrates a commitment to modular flexibility, catering to diverse experimental setups within the European and global markets.
Worldwide Wet Dilution Refrigerator Market
In the Netherlands, Leiden Cryogenics B.V. distinguishes itself through a specific engineering focus on low vibration and high cooling power. This specialization is crucial for experiments where mechanical noise can interfere with sensitive measurements, positioning Leiden as a provider for high-precision scientific applications. Meanwhile, Cryomech, Inc., operating out of Syracuse, New York, integrates dilution refrigerators with pulse tube and Gifford-McMahon cryocoolers. This integration capability highlights a trend toward compact, self-contained systems that minimize external dependency.
American manufacturers also play a significant role. Janis Research Company, located in Woburn, Massachusetts, focuses on scientific research applications, providing robust systems for academic and industrial labs. Montana Instruments Corporation, based in Bozeman, Montana, contributes to the market with He3/He4 systems, ensuring a breadth of technological approaches are available to consumers. The market concentration data indicates a competitive but not overly monopolized environment, with the top three players holding a significant yet balanced share of the market. This structure suggests opportunities for new entrants or niche players who can offer superior customization or specific performance metrics.
Operational Insights and Report Content
To support strategic decision-making, our comprehensive report goes beyond market sizing. It offers a detailed examination of the supply chain, regulatory environments, and technological barriers. Procurement leaders will find value in the comparative analysis of system integration costs versus long-term operational savings. The shift to cryogen-free technologies involves higher upfront capital investment but promises significant reductions in recurrent expenditure related to cryogen replenishment and logistics. Our financial models elucidate this break-even dynamic, helping CFOs and procurement officers build a business case for adoption.
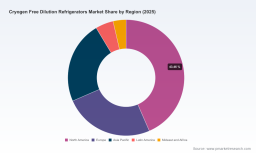
The report also addresses the geographical nuances of market adoption. While we maintain confidentiality on specific regional revenue splits in this summary, our full analysis maps the intensity of demand across key global hubs. This includes an assessment of the infrastructure readiness in North America, Europe, and the Asia Pacific region. Each region presents unique challenges regarding installation support, service networks, and local research funding priorities. Understanding these regional dynamics is essential for companies planning global expansion or supply chain localization.
Additionally, the research includes a detailed breakdown of the application-specific requirements. Whether the end-use is quantum computing, material science, or low-temperature detection, the thermal load profiles and vibration tolerance levels differ. Our report categorizes these needs, providing a matrix that matches system specifications to application demands. This allows technology managers to avoid over-specifying equipment, thereby optimizing budget allocation without compromising performance.
Strategic Recommendations for 2026
As enterprises prepare their strategies for 2026, several key actions emerge from our analysis. First, there is a clear imperative to prioritize partnerships with manufacturers who offer robust service and support networks. The complexity of dilution refrigerators means that downtime can be costly. Evaluating vendors based on their service reach and technical support capabilities is as important as evaluating the hardware specifications.
Second, organizations should consider the scalability of their cooling infrastructure. The forecast growth suggests that demand will not only increase in volume but also in complexity. Investing in systems that can be upgraded or integrated into larger modular setups will provide long-term flexibility. This is particularly relevant for quantum computing firms that anticipate scaling from prototype to production environments.
Third, monitoring the technological evolution in cooling power is essential. The market is seeing a push toward higher cooling powers at millikelvin temperatures. Systems that can handle higher thermal loads without sacrificing base temperature stability will become increasingly valuable. Our report identifies which companies are leading this technological charge and what timelines to expect for next-generation releases.
Conclusion and Call to Action
The Cryogen Free Dilution Refrigerators market is at a pivotal juncture. The convergence of quantum technology advancements, the need for sustainable laboratory operations, and the maturity of cryocooler technology is creating a fertile environment for growth. The projected increase from 197.46 million in 2026 to nearly 290.0 million by 2032 underscores the significance of this sector in the broader high-tech economy.
However, capitalizing on this opportunity requires more than a superficial understanding of market trends. It demands deep intelligence into competitive moves, segmentation nuances, and regional dynamics. Our full report provides the complete dataset, including detailed segmentation splits, regional revenue analysis, and comprehensive company profiles that are not fully disclosed in this overview. For decision-makers committed to securing a competitive advantage in 2026 and beyond, accessing the complete intelligence is a strategic necessity.
Cryogen Free Dilution Refrigerators Market
We invite you to explore the full study to gain the granular insights needed to navigate this complex market. The detailed breakdown of segmentation by region, type, and application, along with the proprietary analysis of market concentration and future outlook, is available in our complete publication. Equip your organization with the knowledge to make informed investments and strategic partnerships in the evolving world of ultra-low temperature infrastructure.
For detailed analysis of this topic, please visit the official page: Cryogen Free Dilution Refrigerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


