



PW Consulting: Potentiometer Market Hits $215M in 2025, Forecasts $317.4M by 2032 at 5.81% CAGR

Navigate the Potentiometer Market in 2026: Strategic Intelligence for Decision Makers
Executive Summary
As global industries pivot toward higher precision, greater connectivity, and tighter supply chain resilience, the potentiometer market stands at a critical inflection point. What was once a mature passive-component segment is now being reshaped by digital integration, material constraints, and application-specific engineering demands. For executives, procurement leaders, and R&D directors, understanding where this market has been and where it is heading is no longer optional. It is a prerequisite for informed capital allocation, product roadmapping, and supplier negotiation in 2026 and beyond.
This strategic overview distills the core findings of our latest Potentiometer Market research into an actionable executive briefing. It traces the market trajectory from historical momentum through the forecast horizon ending in 2032, assesses the competitive architecture, and examines the structural dynamics that will define the next phase of growth. The goal is simple: give you enough depth to build confidence in the analysis, while preserving the granular intelligence that powers precise go-to-market and sourcing decisions.
Historical Context and Growth Trajectory
The potentiometer market has demonstrated consistent expansion over the past half-decade, building on steady unit demand across industrial control, automotive electronics, and consumer device platforms. Revenue measured in United States dollars reached approximately 163.15 million in 2020, climbed to 166.6 million in 2021, and continued its upward path to 181.6 million in 2022. By 2023, the figure moved to 193.17 million, followed by 203.39 million in 2024. The most recent full-year baseline sits at 215.0 million in 2025, reflecting a market that has broadened its addressable scope as digitization and automation penetrate deeper into end-use systems.
Looking forward, the forecast window from 2026 through 2032 maps a measured but unmistakable growth arc. The market is projected to reach 232.85 million in 2026, advance to 245.1 million in 2027, and approach 246.57 million in 2028. Momentum then accelerates through 2029 at 260.5 million, moves to 289.06 million in 2030, and continues to 290.69 million in 2031 before closing the period at 317.4 million in 2032. These top-line projections are aligned with a compound annual growth rate of 5.81 percent. While the percentage may appear moderate at first glance, it reflects a mature component category that is being selectively expanded by technology transition rather than broad-based volume boom. That distinction matters. Growth in this market is not uniform across product families or customer segments; it is concentrated where engineering requirements favor precision, reliability, and integrated sensing capabilities.
Potentiometer Market
For leadership teams planning 2026 budgets and beyond, this trajectory signals three operational realities. First, demand is not disappearing from traditional industrial and automotive control loops; it is evolving. Second, differentiation is moving up the value chain as customers ask for tighter tolerances, longer service life, and compatibility with higher-level control architectures. Third, the forecast suggests that market participants who can align product roadmaps with the fastest-growing application and regional pockets will capture disproportionate share, even in a category where overall growth stays in the mid-single digits.
Why This Research Matters for 2026 Decision-Making
Market studies are only as useful as the decisions they inform. Our Potentiometer Market research is designed to turn a broad industry narrative into a structured decision framework. Rather than offering a single aggregated number and a generic growth statement, the report decomposes the landscape into the dimensions that actually move business outcomes: product architecture, end-use application behavior, geographic demand distribution, competitive positioning, and the external forces that can compress margins or accelerate substitution.
Executives evaluating 2026 planning cycles need answers to questions that surface-level summaries cannot resolve. Which product architectures are preferred in new designs versus legacy retrofits. Where demand is expanding fastest and where it is plateauing. Which suppliers are building meaningful advantages through technology, scale, or regional presence. What external constraints are likely to influence cost structures and supply continuity. The report addresses each of these areas with a methodology built for operational use: it defines the scope clearly, quantifies the addressable universe in a consistent currency and unit framework, and maps the forward path with a rigorous forecast period that extends well beyond the immediate budget year.
A central reason this research carries strategic weight in 2026 is the concentration profile of the market. With the three largest competitors accounting for approximately 24.6 percent of revenue and the five largest reaching about 26.2 percent, the category is neither fragmented nor tightly consolidated. That middle ground creates both opportunity and risk. Buyers can access a meaningful range of suppliers, yet the competitive center of gravity still rests with a handful of established players who can influence pricing norms, technology adoption, and channel expectations. Understanding who occupies that center, and how the broader field is positioning around them, is essential for sourcing strategy, partnership selection, and new product introduction timing.
The report also treats the forecast not as a single line but as a navigational tool. The years between 2026 and 2032 include moments where growth visibly changes pace. Recognizing those inflection intervals matters when organizations are deciding whether to invest in additional capacity, sign long-term supply agreements, enter new application verticals, or phase out older product lines. With historical data spanning 2020 through 2025 and a forecast extending to 2032, the research gives decision makers a continuous timeline to test assumptions against, instead of forcing them to extrapolate from a single snapshot.
Inside the Report: What You Will Find
The full study is organized to move from macro structure to actionable detail. It begins with a comprehensive market definition and scope framework, establishing the product categories, revenue conventions, and geographic boundaries used throughout the analysis. From there, the report builds a quantified historical view that supports the forecast and provides context for year-over-year shifts. Rather than leaving readers with a single composite figure, it frames the market in terms of its major structural dimensions so that strategy teams can map the data back to their own portfolio, customer base, and supply footprint.
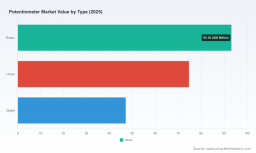
Multi Turn Potentiometer Market
A substantial portion of the report focuses on segmentation logic that mirrors how buyers and engineers evaluate potentiometer solutions in practice. This includes a product architecture perspective covering the families that shape design choices, an application view that connects demand patterns to end-use requirements, and a regional breakdown that highlights where volume and growth are concentrated. These views are arranged to help teams answer practical questions: which product types are most relevant to your target applications, which applications are expanding most rapidly, and how regional demand differs enough to warrant distinct sourcing or go-to-market approaches.
The competitive section profiles the principal players shaping the market today. Each company profile emphasizes the capabilities and offerings most relevant to potentiometer demand, including precision trimmers, rotary and linear variants, digital variants, industrial and high-reliability grades, and integration with sensors and connector systems. The research also tracks recent commercial activity that signals where each company is placing its bets. For example, in November 2025, Bourns Inc. introduced a new high-resolution digital potentiometer series optimized for IoT and automotive applications. This launch illustrates a broader industry trend in which analog essentials are being augmented by digitally enabled variants designed for tighter control loops and connected equipment. The report places developments like this within the larger competitive context so that readers can interpret product announcements as strategic signals rather than isolated events.
How the report supports different functions
- Executive planning teams can use the forecast horizon and structural segmentation to stress-test revenue assumptions, prioritize regions, and identify where portfolio adjustment is most valuable.
- Procurement and supply chain leaders can benchmark the competitive field, evaluate concentration risk, and align contracting strategy with the reality of a market that is moderately concentrated but still supplied by a broad field of capable manufacturers.
- Product and engineering leaders can connect application-level demand patterns to design choices, particularly where digital integration, precision requirements, and reliability expectations are reshaping specification behavior.
- Strategy and M&A teams can use the competitive profiles and regional dynamics to identify adjacent capabilities, partner candidates, and segments where consolidation or capability investment may create durable advantage.
Competitive Landscape: Who Shapes the Market and How
The potentiometer market is defined by a set of established manufacturers that combine component engineering depth with broad distribution reach and application-specific development capability. The competitive picture is not dominated by a single architecture or geography. Instead, it reflects multiple centers of strength: American firms with strong precision and industrial heritage, Japanese manufacturers with deep consumer and automotive electronics experience, and globally integrated suppliers that tie potentiometers into broader sensor and connectivity ecosystems.
Bourns, Inc., based in Riverside, California, continues to stand out for its leadership in trimmers, precision potentiometers, and specialized electronic components serving industrial, automotive, and IoT applications. Its positioning is especially relevant for design teams that need repeatable precision and a product set aligned with both traditional control tasks and newer connected requirements. The company's late-2025 digital potentiometer launch underscores a focus on higher-resolution control and compatibility with automotive and IoT use cases, signaling that its roadmap is actively extending into digitally assisted sensing and adjustment functions.
Vishay Intertechnology, Inc., headquartered in Malvern, Pennsylvania, offers a strong portfolio of single-turn trimpots and precision analog potentiometers built on wire-wound and cermet technologies. Its emphasis on industrial and high-reliability segments makes it a notable reference point for applications where stability, durability, and controlled tolerance matter more than unit cost alone. In a market where some demand is moving toward digital alternatives, Vishay's analog strength remains important for end-uses that still rely on proven resistor-based adjustment and feedback elements.
Honeywell International Inc., based in Charlotte, North Carolina, brings a broader sensing and control identity to the market. Alongside potentiometer-based solutions, Honeywell provides Hall-effect and position sensors for industrial automation and aerospace. This mix matters because many engineering teams evaluate potentiometers not in isolation but as one option within a larger sensing architecture. A supplier that can address both contact-based adjustment and non-contact sensing can influence specification choices at the system level.
Nidec Copal Electronics, located in Tokyo, Japan, specializes in rotary and trimmable potentiometers for consumer electronics and automotive control systems. Its relevance reflects the continued importance of compact, application-tight components for control interfaces and adjustment functions where size, consistency, and integration ease are priorities. Alps Alpine Co., Ltd., also based in Tokyo, manufactures robust rotary and linear potentiometers for automotive and industrial control applications, reinforcing the role of Japanese manufacturers in segments where mechanical robustness and steady performance under demanding conditions are critical.
TE Connectivity, headquartered in Schaffhausen, Switzerland, supplies precision potentiometers integrated into connectors and sensors for electronics and semiconductor-adjacent systems. Its value proposition is rooted in integration and system-level compatibility, which matters as design teams increasingly look for components that reduce assembly complexity and align with broader interconnect and sensing strategies. CTS Corporation, based in Westlake Village, California, produces industrial-grade rotary potentiometers for transportation, medical, and heavy-duty equipment. Its profile highlights demand in sectors where equipment uptime, certification expectations, and long service life shape purchasing decisions more than short-term price variance.
What this competitive structure means for buyers and investors
- The field includes firms with specialty strength in analog precision, digital transition, automotive-grade robustness, and sensor integration, so procurement choices should be tied to application requirements rather than brand familiarity alone.
- Competitive advantage is increasingly defined by the ability to serve demanding end-use environments while also supporting design trends toward higher resolution and digital compatibility.
- Moderate market concentration means credible alternatives exist, but the strongest suppliers still influence expectations on technology roadmaps, qualification cycles, and channel support.
- Recent new-product activity suggests that competitive differentiation will continue to hinge on how well suppliers bridge traditional potentiometer functions with the needs of connected, automated, and high-reliability systems.
Market Dynamics: Materials, Regulation, and Strategic Pressure
Pricing, sourcing, and availability in the potentiometer market do not exist in isolation. They are shaped by material flows, regulatory actions, and the broader electronics supply environment. One of the most significant external factors currently reshaping input-cost expectations is the evolving rare earth export environment linked to China. In April 2025, China imposed expanded export controls on medium- and heavy-rare-earth materials. According to reporting attributed to the Ministry of Commerce of China, the move had the potential to reduce exports dramatically and double global prices for affected elements within weeks. That kind of shock does not remain confined to raw material markets; it filters into component manufacturing, especially where rare-earth-dependent materials contribute to magnetic, sensor-adjacent, or performance-critical subsystems.
The pressure intensified later in the year. The Chinese Ministry of Commerce announced further export controls on rare earth elements and related products effective 8 November 2025, requiring licenses for products containing 0.1 percent or more of Chinese-origin rare earths or manufactured with Chinese equipment. A related assessment from the International Energy Agency in October 2025 noted that China's export controls on heavy rare earth elements introduced in April 2025 had driven European prices up to roughly six times those in China, constraining competitiveness for rare-earth-dependent electronic components.
These developments matter for the potentiometer market because the category does not operate in a vacuum. Even when a component is not itself a rare-earth product, its manufacturing ecosystem, adjacent sensors, and the broader electronic assembly environment can be affected by material constraints and licensing complexity. For sourcing leaders and finance teams, the strategic implication is not simply that costs may rise, but that supply continuity and regional cost structures may diverge more sharply than historical norms suggest. Companies that rely on single-source dependencies or that do not model regulatory risk into their procurement assumptions may face margin compression or schedule disruption.
Operational implications for 2026 planning
- Build rare-earth exposure and material dependency into supplier evaluation criteria, especially for high-reliability and automotive-grade programs where qualification lead times make rapid switching difficult.
- Pressure-test cost models against regional price divergence, particularly if your design or manufacturing footprint depends on components or subsystems sensitive to rare-earth input constraints.
- Use the forecast window to plan flexibility into contracts and inventory strategy, recognizing that regulatory-triggered cost movements can alter the economics of long-term commitments.
- Monitor substitution and design-adaptation trends, since material constraints often accelerate engineering efforts to reduce dependency on constrained inputs or to shift specifications toward alternative technologies.
What Comes Next for Strategy and Sourcing
The potentiometer market is moving through a phase where growth is dependable but uneven, and where competitive advantage is increasingly tied to technology transition, reliability assurance, and supply resilience. The top-line forecast points to a market that will continue expanding through 2032, but the real strategic work lies in understanding where that expansion concentrates, which product approaches win new specifications, and how external constraints alter the economics of supply.
For 2026 decision makers, the highest-value questions are practical. Which applications are pulling demand upward most strongly in your portfolio. Which product architectures best match the precision and integration requirements of your customers. How exposed your sourcing strategy is to material and regulatory volatility. Which competitors are shaping expectations through product launches, integration offerings, and application-specific development. The full Potentiometer Market research is built to help answer those questions with the level of detail that planning committees, procurement teams, and engineering leaders need to act with confidence.
This briefing has outlined the trajectory, structure, competitive landscape, and external pressures that define the market today. The complete report goes further, offering the segment-level analysis, regional views, application breakdowns, and company-level insights necessary to turn strategic awareness into concrete decisions. For organizations preparing for 2026 and the forecast years that follow, that deeper intelligence is where the real advantage lies.
For detailed analysis of this topic, please visit the official page: Potentiometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


