



PW Consulting Report: Marine Fleet Management Market Hits $1.04B in 2025, Projects 10.8% CAGR to $2.12B by 2032

Navigating the Digital Seas: Strategic Intelligence for the Marine Fleet Management Software Market
The maritime industry stands at a critical inflection point. As vessels grow smarter and supply chains demand greater transparency, the marine fleet management software market has evolved from a back-office utility into a strategic command center for shipping operators worldwide. Our latest market research delivers a comprehensive, data-driven assessment of this landscape, offering decision-makers the clarity required to navigate investment, procurement, and competitive positioning through 2032.
This analysis is not merely a snapshot of current valuations. It is a forward-looking strategic instrument designed to help executives anticipate regulatory shifts, evaluate technological migration paths, and align fleet digitalization roadmaps with measurable operational outcomes. Below, we outline the structural forces shaping the market and demonstrate how our research framework translates complex maritime dynamics into actionable intelligence.
Market Trajectory and Structural Expansion
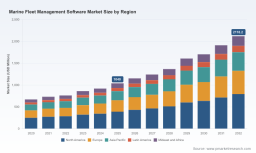
Over the past half-decade, the marine fleet management software sector has demonstrated consistent, compounding growth. Revenue expanded from approximately 670.0 million USD in 2020 to an estimated 1040.0 million USD by 2025, reflecting sustained enterprise adoption, rising compliance mandates, and the gradual phasing out of legacy spreadsheet-driven workflows. The trajectory forward indicates continued acceleration, with the market projected to surpass 1153.18 million USD in 2026 and approach 2118.2 million USD by 2032.
At the core of this expansion lies a compound annual growth rate of 10.8 percent across the forecast horizon. This rate is not an abstract figure; it represents the cumulative effect of cloud migration, remote vessel monitoring requirements, and the operational necessity of integrating maintenance, crewing, and compliance into unified digital platforms. Organizations that treat fleet software as a capital allocation priority rather than a discretionary upgrade will be best positioned to leverage this growth cycle.
The historical baseline from 2020 through 2025 reveals a market that has already weathered early adoption friction and emerged with clearer procurement standards. Enterprises now evaluate solutions based on interoperability, data sovereignty, and total cost of ownership across vessel lifecycles. These evaluation criteria are reshaping vendor selection and influencing the pace at which digital transformation initiatives advance across fleets of varying sizes.
Core Segmentation Drivers Shaping Investment Decisions
The market does not expand uniformly. Growth is concentrated where operational pain points intersect with regulatory pressure and technological feasibility. Enterprise buyers are increasingly prioritizing deployment models that balance scalability with control, while application-specific requirements continue to differentiate procurement strategies across shipping operations, terminal infrastructure, and freight forwarding networks.
Deployment architecture remains a defining strategic variable. Cloud-native solutions have captured the majority of recent commercial momentum, driven by the demand for real-time synchronization across dispersed fleets, reduced on-site infrastructure overhead, and continuous feature iteration. At the same time, on-premises deployment retains a meaningful footprint among operators with strict data residency mandates, legacy integration dependencies, or specialized onboard connectivity constraints. Evaluating the appropriate architecture requires a nuanced understanding of vessel connectivity profiles, cybersecurity posture, and long-term total cost of ownership rather than a one-size-fits-all preference.
Application adoption patterns further illustrate how fleet software is being deployed across the maritime value chain. Shipping operators continue to represent the largest demand pool, leveraging integrated platforms to coordinate maintenance scheduling, regulatory compliance, and voyage optimization. Ports and terminals are expanding their software footprints to improve berth coordination, asset utilization, and cross-functional data exchange. Maritime freight forwarders are adopting fleet-adjacent modules to enhance shipment visibility, carrier coordination, and operational reporting. These application-level dynamics influence not only vendor positioning but also the scope of enterprise negotiations and integration roadmaps.
Regional demand patterns also reflect divergent maturity curves and regulatory environments. Certain markets exhibit advanced digitalization baselines and strong vendor ecosystems, while others are in earlier stages of fleet standardization and cloud adoption. Understanding where demand is consolidating versus where it is emerging enables procurement leaders to calibrate rollout strategies, prioritize regional support capabilities, and anticipate competitive intensity in local market segments.
Competitive Landscape and Strategic Positioning
The vendor ecosystem reflects a mix of established classification-linked platforms, specialized maritime software providers, and broader marine technology companies extending into digital fleet operations. Strategic buyers must evaluate not only product functionality but also ecosystem reach, integration depth, and the ability to maintain continuity across vessel classes and regulatory regimes.
DNV continues to reinforce its position through ShipManager, a solution engineered to support vessels and fleets across technical, operational, and compliance dimensions. Its alignment with class and regulatory expertise gives it particular resonance among operators seeking to embed compliance workflows directly into daily fleet management routines. BASS Software Ltd competes with BASSnet, a native cloud maritime ERP platform that unifies maintenance, HSEQ, payroll, crewing, and financial functions within a single operational framework. This breadth appeals to organizations pursuing end-to-end digitization rather than point solutions.
Marine Fleet Management Software Market
SERTICA by RINA delivers fleet management capabilities centered on planned maintenance, procurement, HSQE, and operational optimization, positioning itself as a practical operational efficiency platform for fleets that require disciplined maintenance planning and procurement visibility. ABS Group of Companies Inc provides the ABS Wavesight platform, which has scaled across more than 5,000 vessels and combines fleet management with classification integration for compliance assurance. This scale and class linkage create a distinctive value proposition for operators prioritizing standardized compliance reporting and broad fleet coverage.
TIMEZERO has strengthened its relevance in navigation and fleet tracking through cloud-based AIS, real-time positioning, and chart-based operational awareness. Its April 2025 transition to a fully cloud-based product line introduced automatic software updates, community maps, extended-range online AIS, premium weather with real-time Doppler radar, text-based weather alerts, and enhanced fleet tracking. This migration signals a broader industry shift toward continuously updated cloud services and away from isolated, manually maintained navigation tools.
IoT Fleet Management Market
Additional participants such as SpecTec, Shipnet AS, PRIME Marine, and Kongsberg contribute further specialization across ship operations, fleet tracking, maintenance efficiency, and digital optimization. Their presence underscores a fragmented but increasingly integrated competitive field where differentiation is determined by workflow coverage, interoperability, and the ability to support both operational and compliance objectives simultaneously.
Market concentration remains meaningful. The top three players account for approximately 50.3 percent of market revenue, while the top five collectively represent about 68.2 percent. This concentration indicates established incumbency advantages, but it also signals room for specialized challengers that can win on deployment flexibility, regional support, or application-specific optimization. Enterprise buyers should interpret concentration not as a barrier to choice but as a framework for evaluating ecosystem reliability, negotiated value, and long-term vendor stability.
Dynamics, Risks, and Technology Migration Realities
Fleet management software adoption does not occur in a vacuum. It intersects with cybersecurity expectations, data governance requirements, connectivity limitations, and the operational realities of managing vessels across multiple jurisdictions. Decision-makers must assess platforms not only for feature depth but also for resilience, certification alignment, and the capacity to safeguard vessel tracking and fleet operations against evolving threat vectors.
Cybersecurity has become a defining procurement consideration. Maritime software platforms increasingly operate under infrastructure certifications such as SOC 2 Type 2 and ISO 27001:2022, which provide structured assurance for organizations managing sensitive operational data, crew information, and compliance reporting. These frameworks are not optional garnish; they are becoming baseline expectations for operators that rely on digital platforms for vessel tracking, remote monitoring, and fleet-wide coordination. Evaluating a vendor's security posture alongside its functional capabilities is now a necessary component of procurement due diligence.
Connectivity and data latency further complicate deployment strategy. Vessels operating in remote routes or with intermittent bandwidth face different adoption constraints than those in regions with robust maritime connectivity. Cloud migration can deliver rapid updates, centralized data, and improved cross-fleet visibility, but it must be balanced against crew training requirements, onboard hardware compatibility, and fallback operational procedures. Successful transformation programs recognize these constraints and sequence implementation in ways that preserve operational continuity while capturing digital benefits.
Regulatory complexity continues to elevate the strategic importance of fleet software. Compliance documentation, emissions-related reporting, safety management integration, and class-related workflows are increasingly expected to flow through unified digital environments rather than fragmented manual processes. Software that can standardize these workflows while maintaining auditable records offers tangible operational and risk-management value. Enterprises that delay this integration may face rising administrative overhead and greater exposure to documentation gaps as regulatory scrutiny intensifies.
What the Research Delivers
This market study translates broad industry momentum into a structured, decision-ready intelligence framework. Rather than offering surface-level descriptors, the report maps the commercial architecture of the marine fleet management software market across multiple dimensions that matter to enterprise strategy.
- Historical revenue progression and forward-looking projections that frame the scale and pace of market expansion across the forecast horizon
- Deployment-level analysis that clarifies where cloud momentum is strongest and how on-premises demand persists under specific operational and regulatory conditions
- Application-level demand characterization that distinguishes adoption patterns across shipping operations, ports and terminals, and maritime freight forwarding contexts
- Regional demand mapping that identifies where maturity, competition, and procurement dynamics differ across major commercial zones
- Competitive profiling of core vendors, including solution scope, deployment emphasis, and strategic differentiation relevant to fleet operators
- Market concentration measurement that informs vendor benchmarking, negotiation strategy, and ecosystem stability assessment
- Operational and regulatory dynamics that connect cybersecurity expectations, compliance workflows, and connectivity realities to procurement and implementation decisions
Each section is designed to support concrete corporate actions: prioritizing software investment, evaluating vendor shortlists, sequencing digital rollout across fleets, and anticipating where competitive pressure is likely to intensify. The analysis emphasizes not just what the market is doing, but why it is doing it, and what that implies for capital allocation, vendor selection, and operational planning.
Strategic Implications for 2026 Decision-Making
For executives planning 2026 initiatives, the strategic question is no longer whether fleet management software matters, but how to deploy it in a way that compounds operational resilience and commercial advantage. Organizations that align procurement with deployment reality, compliance trajectory, and cybersecurity expectations will extract more value from their digital investments than those that evaluate solutions in isolation.
Procurement teams should assess platforms against the full operational lifecycle: maintenance coordination, compliance documentation, crew and payroll integration, financial reporting, and real-time fleet visibility. Technology leaders should weigh cloud migration benefits against connectivity constraints and data governance requirements. Commercial leaders should interpret market concentration and regional demand divergence as signals for where vendor leverage, support capability, and implementation risk are likely to differ.
The market's growth rate, structural segmentation, and evolving competitive dynamics all point to a single conclusion: fleet management software is becoming a core operational asset rather than a peripheral IT purchase. Companies that approach it with the appropriate strategic rigor will be better equipped to manage compliance exposure, improve vessel and terminal utilization, and support the broader digitalization of maritime operations.
Accessing the Full Intelligence Framework
The insights summarized here represent the strategic surface of a much deeper analytical structure. The complete report contains the segmentation detail, vendor comparison framework, deployment and application demand breakdowns, regional demand mapping, and concentration analysis required to convert market awareness into procurement and investment decisions.
For executives who need to benchmark vendors, prioritize deployment paths, or evaluate regional rollout timing, the full dataset provides the granularity necessary to move from directional understanding to executable planning. We invite decision-makers to access the complete research directly through our source page, where the full segmentation logic, competitive profiles, and forecast structures are available for internal review and strategic application.
In a market expanding at a double-digit pace and increasingly defined by cloud adoption, compliance integration, and cybersecurity expectations, incomplete information is a strategic liability. The full report is designed to remove that liability and replace it with a structured basis for confident, evidence-based decision-making.
For detailed analysis of this topic, please visit the official page: Marine Fleet Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


