



PW Consulting: Wind Turbine Installation Vessel Market to Hit $10.5B by 2032 at 11% CAGR

Strategic Imperatives in the Wind Turbine Installation Vessel Market: A 2026 Outlook
The global offshore wind sector has entered a decisive phase of industrial scaling, and the capital assets required to execute this expansion—Wind Turbine Installation Vessels (WTIVs)—are at the center of a rapidly intensifying market dynamic. As policymakers, developers, and marine contractors navigate the complex intersection of technological evolution, regulatory shifts, and supply chain constraints, access to precise, forward-looking intelligence is no longer a luxury; it is a foundational requirement for strategic planning. Our latest market research on the Wind Turbine Installation Vessel Market provides a comprehensive, data-driven blueprint of the industry landscape, engineered specifically to inform high-stakes corporate decisions throughout 2026 and beyond.
Between 2020 and 2025, the market experienced a sustained trajectory of revenue growth, expanding from 3.0 billion USD to 5.06 billion USD. This historical performance reflects a sector transitioning from early-stage pilot deployments to industrialized, utility-scale installation campaigns. Moving forward, our forecast model projects that the market will continue its robust expansion, reaching approximately 5.51 billion USD in 2026 and scaling steadily toward 10.5 billion USD by 2032. This growth is underpinned by a compound annual growth rate of 11.0 percent over the forecast period, signaling a structural acceleration rather than a cyclical fluctuation. For executive teams, financial planners, and maritime asset managers, these macroeconomic signals establish a clear mandate: capacity allocation, fleet modernization, and partnership strategy must be recalibrated to capture value in a market that is fundamentally outpacing historical benchmarks.
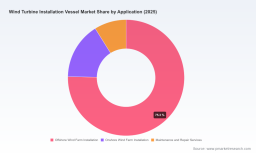
However, aggregate figures only tell part of the story. The real strategic leverage lies in understanding how growth distributes across vessel architectures, service models, and geographic deployment corridors. Our full report deliberately segments these dimensions, revealing where capital efficiency is being maximized, which application verticals are driving sustained utilization rates, and how regional project pipelines are reshaping vessel routing and charter economics. While we reserve the granular regional and application-level breakdowns for our comprehensive publication, it is already evident that the installation of offshore wind farms remains the dominant revenue driver, while onshore deployment and specialized maintenance and repair services contribute distinct, complementary revenue streams that require differentiated operational playbooks.
Decoding the Competitive Architecture
The WTIV market is characterized by a notably concentrated competitive structure. Our analysis indicates that the top three operators collectively command approximately 58.0 percent of market revenue, while the top five players extend their combined share to roughly 65.0 percent. This concentration is not merely a statistical observation; it reflects a strategic reality where scale, vessel capability, and long-term charter commitments create formidable barriers to entry. For incumbent operators, this landscape presents an opportunity to solidify pricing power and secure preferential access to high-value project slots. For new entrants, joint ventures, asset leasing models, or niche specialization in emerging deployment zones may offer more viable pathways to market participation.
Several industry leaders have already positioned themselves at the forefront of this evolution. Cadeler, headquartered in Copenhagen, Denmark, continues to expand its operational footprint as the owner and operator of the largest fleet of jack-up offshore wind turbine installation vessels, including next-generation assets such as Wind Mover, Wind Ally, and Wind Ace. The company’s 2025 annual report, published in March 2026, confirmed the doubling of its WTIV fleet capacity through the delivery of five vessels, underscoring a deliberate strategy to capture a growing share of large-scale installation contracts. In the Netherlands, Van Oord operates specialized marine installation platforms, including Boreas and Aeolus, which are engineered for heavy-lift foundation work and turbine deployment in demanding offshore environments. Meanwhile, DEME Group, based in Beveren, Belgium, has aggressively advanced its next-generation fleet with vessels such as Norse Wind and Norse Energi, both designed to install 15+ MW turbines and handle XXL monopiles in deepwater settings. DEME Group formally named Norse Wind at the Port of Oslo in April 2026, and earlier that year announced the delivery of Norse Energi at CIMC Raffles Shipyard, with the sister vessel entering service in the first half of 2026.
Wind Turbine Installation Vessel Market
Additional players are reinforcing the industry’s operational diversity and geographic reach. A2SEA, headquartered in Fredericia, Denmark, remains a specialized provider of offshore wind turbine installation services and vessels tailored for wind farm construction. Eneti Inc., operating from Monaco, manages self-elevating platform vessels through its Seajacks fleet, delivering targeted installation capabilities for offshore wind projects. In the United Kingdom, MPI Offshore deploys the MPI Resolution and MPI Adventure specifically for turbine and foundation installation tasks. Jack-Up Barge, based in Oosterhout, Netherlands, supports the sector with jack-up barges and accommodation vessels that enable both installation and ongoing maintenance operations. Fred. Olsen Windcarrier, operating out of Oslo, Norway, focuses on global energy security and large wind farm projects through its dedicated installation fleet. On the shipbuilding and integrated delivery side, Seatrium in Singapore has emerged as a critical enabler, handing over a next-generation WTIV to Maersk Offshore Wind in February 2026 for deployment on the Empire Wind 1 project, a milestone that highlights the growing synergy between Asian shipyards and Western offshore wind developers. Swire Blue Ocean, also headquartered in Copenhagen, continues to provide fleet services for major wind farm installations, reinforcing the sector’s reliance on experienced, project-proven operators.
Operational Realities Shaping 2026 Decision-Making
The strategic calculus for any organization operating in this market is increasingly defined by capital intensity, operational expenditure dynamics, and regulatory friction. Newbuild prices for modern, large-scale WTIVs now exceed 400 million USD, and industry benchmarks suggest that five-year-old vessels will command valuations approaching 275 million USD by 2030. These asset valuations are driven by multiple reinforcing cost factors: steel procurement, specialized marine equipment, and the integration of high-capacity crane systems and dynamic positioning technologies all contribute to substantial upfront capital requirements. Equally important, daily operational expenses—encompassing fuel, crew, maintenance, and port logistics—represent a persistent pressure point on project economics. Organizations that fail to model these operational cost structures with precision risk underpricing charter engagements or overestimating net utilization returns.
At the same time, regulatory frameworks and jurisdictional requirements are introducing new variables into fleet planning. In the United States, emerging Jones Act-compliant WTIV conversion concepts are being evaluated as a cost-mitigation pathway, targeting conversion expenditures that represent roughly one-third to one-half the cost of constructing a new US-built vessel. This development is particularly relevant for stakeholders aligned with domestic offshore wind capacity goals, as it may unlock a more cost-effective route to meeting localized installation demands while navigating maritime compliance mandates. On the technology frontier, vessels capable of installing 15+ MW turbines with 180-metre hook height cranes have already been delivered to Maersk Offshore Wind in early 2026 for the Empire Wind 1 project, demonstrating that the industry’s capability threshold is rising in lockstep with turbine scale.
These operational and regulatory dynamics do not exist in isolation. They intersect with project scheduling, feed-in tariffs, monopile and foundation supply chains, port infrastructure availability, and seasonal weather windows. Our full report maps these interdependencies systematically, enabling decision-makers to stress-test scenarios, identify bottlenecks before they become capital traps, and align fleet deployment strategies with real-world execution constraints.
What the Full Report Delivers
Designed for executive leadership, corporate development teams, maritime investors, and policy-aligned strategists, our comprehensive Wind Turbine Installation Vessel Market research goes far beyond headline figures. The publication delivers an integrated analytical framework that connects market sizing with actionable operational intelligence. Key components include:
- Historical performance tracking from 2020 through 2025, establishing a verified baseline against which forward projections can be benchmarked.
- A detailed forecast architecture spanning 2026 to 2032, with scenario-sensitive modeling that accounts for vessel delivery timelines, turbine size progression, and regional project pipeline variability.
- Deep-dive segmentation that isolates growth contributions by vessel type, application vertical, and geographic deployment pattern, allowing teams to pinpoint where marginal revenue opportunities are concentrated.
- A structured competitive landscape assessment that evaluates fleet capacity, vessel specifications, strategic positioning, and recent operational milestones for leading market participants.
- Analysis of capital cost trajectories, daily operational expense drivers, and regulatory developments that directly influence charter pricing, asset valuation, and project feasibility.
- Integration of recent industry developments, including major vessel deliveries, fleet expansion announcements, and naming ceremonies that signal near-term capacity shifts and deployment priorities.
- Strategic implications for market entry, partnership structuring, vessel chartering, and capital allocation, presented with the granularity required for board-level planning.
Rather than offering generic commentary, the report synthesizes proprietary data, industry market intelligence, and verified corporate announcements into a single, decision-ready reference. The objective is to equip organizations with the clarity needed to act confidently in a market where timing, capability alignment, and cost discipline determine competitive advantage.
Why 2026 Demands a Disciplined Intelligence Advantage
The current moment represents a critical inflection point for the WTIV sector. On one side, demand is being propelled by accelerating offshore wind capacity targets, larger turbine ratings, and increasingly complex foundation designs that require more capable, more expensive vessels. On the other side, capital markets, supply chain latency, and operational cost inflation are raising the stakes for every investment decision. Organizations that approach this environment with fragmented data or reactive planning will find themselves either overcommitting to underutilized assets or missing high-probability deployment windows. Conversely, those that integrate rigorous market sizing, segmentation intelligence, and competitive benchmarking into their planning cycles will be better positioned to negotiate favorable charter terms, sequence fleet upgrades efficiently, and align strategic partnerships with verified project pipelines.
Our research is built to serve as that strategic anchor. By synthesizing historical performance, forward-looking projections, and granular breakdowns of market structure, the report enables leaders to move from intuition to evidence-based action. The concentration of revenue among a handful of major operators, the escalating cost of next-generation vessel assets, and the rapid pace of recent deliveries all point to a market where information asymmetry carries real financial consequences. Access to comprehensive, verified intelligence is the most reliable countermeasure.
Moving Forward with Confidence
The Wind Turbine Installation Vessel Market is not simply growing; it is reconfiguring around higher technical thresholds, stronger competitive moats, and more demanding operational economics. Success in 2026 and the years that follow will depend on the ability to interpret macro growth signals, navigate vessel capability requirements, and align capital deployment with realistic utilization expectations. Our full market research report provides the structural insight, segmented detail, and competitive context required to make those decisions with precision. We invite executive teams, investors, and maritime strategists to access the complete publication, where the full segmentation breakdowns, regional deployment patterns, application-level revenue distributions, and actionable strategic recommendations are presented in depth. In a market that rewards speed, accuracy, and disciplined planning, comprehensive intelligence is not an optional resource—it is the foundation of durable competitive advantage.
Offshore Wind Turbine Installation Vessel Market
For detailed analysis of this topic, please visit the official page: Wind Turbine Installation Vessel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


