



PW Consulting: Centrifugal Chiller Market to Grow at 6.21% CAGR, Reaching $483.9M by 2032

Navigating the Next Decade: Strategic Intelligence in the Global Centrifugal Chiller Market
The commercial and industrial HVAC landscape is undergoing a structural transformation driven by stringent energy codes, the explosive growth of digital infrastructure, and a regulatory pivot toward low-global-warming-potential (GWP) refrigerants. For executives, facility owners, and engineering leaders, understanding the centrifugal chiller segment is no longer a technical afterthought—it is a capital allocation imperative. At PW Consulting, we have synthesized a multi-year historical record and a forward-looking forecast to illuminate where value will accrue between 2026 and 2032. This research is designed not as a static snapshot, but as a decision-grade instrument for portfolio planning, infrastructure investment, and competitive positioning.
Our baseline analysis anchors on a measured historical trajectory from 2020 through 2025, capturing the market's recovery and maturation phases. The global revenue base expanded from approximately 263.05 million USD in 2020 to 319.5 million USD by 2025, reflecting resilient demand across commercial campuses, heavy industrial processes, and the rapid densification of cooling requirements in technology-driven environments. Looking ahead, the forecast period to 2032 maps a sustained upward curve, with compounded annual growth projected at 6.21 percent. This trajectory signals more than incremental expansion; it indicates a market structurally re-rating around efficiency, refrigerant compliance, and application-specific engineering. Decision-makers who internalize these macro signals early will be better positioned to align procurement cycles, capacity planning, and technology roadmaps with the market's directional momentum.
The Architecture of the Study: From Macro Signals to Operational Playbooks
A credible market study must bridge the gap between aggregate forecasting and the granular realities of engineering, procurement, and operations. Our Centrifugal Chiller Market research is organized to support that translation. Rather than presenting a single headline number, the report decomposes the market along dimensions that matter to buying committees and capital planners: technology architecture, application contexts, and regional deployment patterns. These lenses allow readers to test assumptions about where capacity is being installed, which operating profiles dominate spend, and how regional regulatory climates influence product specification.
The study's operational value lies in its scaffold of decision-support content. Each section is constructed to answer a concrete planning question:
- Where does historical volatility end and structurally driven growth begin, enabling more reliable budgeting for multi-year capital programs?
- Which technology pathways—air-cooled versus water-cooled configurations—carry distinct risk-return profiles under evolving ambient conditions and efficiency mandates?
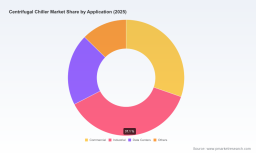
- How do application contexts such as commercial facilities, industrial operations, and data center environments shape load profiles, redundancy requirements, and lifecycle cost calculus?
- What regional dynamics influence project timing, specification preferences, and supply chain readiness across major demand centers?
By integrating these dimensions, the report gives stakeholders a structured way to compare scenarios rather than a single deterministic path. That distinction matters in a market where project lead times, refrigerant transitions, and efficiency targets can shift procurement economics within a single budget cycle.
Competitive Intensity and the Battle for Specification
The centrifugal chiller segment features a concentrated set of global manufacturers, each competing on thermodynamic performance, refrigerant readiness, and application-specific engineering. Our market concentration analysis indicates that the top three firms collectively account for roughly 60 percent of revenue, while the top five capture approximately 75 percent. This concentration reflects both the technical barriers to entry in large-capacity, high-efficiency chiller design and the importance of service networks, certification track records, and long-term operational credibility in winning institutional assignments.
Centrifugal Compressors Market
Within this landscape, several established players continue to advance product portfolios that directly address efficiency mandates and refrigerant compliance. Johnson Controls has emphasized its YK, YZ, YMC2, and YK-HT magnetic bearing centrifugal chillers, engineered for energy savings, low-GWP refrigerant compatibility, and large-capacity data center applications. Carrier has focused on the AquaEdge 19DV and AquaForce series, pairing variable-speed drives with sustainability-oriented features for commercial and industrial use. Trane Technologies offers CenTraVac and Series R magnetic bearing units positioned for high efficiency and space savings across commercial, industrial, and data center applications. Daikin Applied promotes its Magnitude WMT, WME-D, and WME series oil-free magnetic bearing chillers with two-stage compressors and low-GWP refrigerants. Mitsubishi Heavy Industries contributes efficient centrifugal platforms for energy saving and environmental protection in large commercial and industrial installations. LG Electronics brings its H Series 2-stage centrifugal chillers with inverter technology and AHRI 550/590 certified performance to the equation. In parallel, regional and specialized manufacturers extend the competitive field: Ecochillers from Guadalajara offers oil-free centrifugal chillers using low-GWP refrigerants and custom magnetic-bearing models for industrial and commercial applications, while Smardt Chiller Group from Dorval provides oil-free centrifugal units designed for laboratories, food, and pharmaceutical environments with ISO 9001 certification.
The strategic implication for buyers is that specification competition is intensifying at the edges of performance, refrigerant compliance, and application fit. For vendors, differentiation increasingly depends on demonstrating measurable lifecycle advantages under real operating conditions rather than headline capacity claims alone. Our report situates each company's positioning within the broader demand structure, helping readers interpret where competitive pressure is likely to influence pricing, service models, and technology roadmaps over the forecast period.
Latest Market Movements: Product Innovation Meets Regulatory Realities
Recent developments in the segment underscore how quickly product roadmaps and compliance requirements are converging. In February 2026, Johnson Controls previewed the high-density compact YORK YK-HT two-stage economized centrifugal chiller at the AHR Expo, highlighting a wide operating range from a single driveline, zero water consumption capability, and lift performance up to 110°F for data centers and large campuses. Announced in October 2024, Daikin Applied introduced the Magnitude WME-D magnetic bearing oil-free centrifugal chiller with a two-stage compressor and low-GWP R-515B refrigerant. These milestones are not isolated product launches; they are signals of how manufacturers are adapting to denser load profiles, water availability constraints, and refrigerant phase-down expectations.
These product movements intersect with a hardening regulatory and technical environment that shapes procurement specifications and performance validation. ASHRAE 90.1-2022 requires non-standard rating condition adjustments for water-cooled centrifugal chiller packages using the K adj equation to meet minimum full-load kW/ton and IPLV efficiencies. AHRI 550/590 certification is mandatory for all listed centrifugal chiller performance ratings, including full-load and integrated part-load values. In the United States, low-GWP refrigerants are mandated for new centrifugal chillers beginning January 2025, prompting manufacturers to expand compliant model lines; Johnson Controls, for example, extended YVAM air-cooled models to support compliance. At the technology level, magnetic bearing architectures in centrifugal chillers eliminate oil lubrication, reducing maintenance costs and enabling operation at condenser temperatures up to 30°F below chilled water setpoint.
Together, these forces create a market environment in which efficiency targets, refrigerant readiness, and certified performance documentation are becoming baseline expectations rather than premium differentiators. Organizations that anticipate these requirements in their specification language and vendor evaluation criteria will encounter fewer delays and lower residual compliance risk during project execution.
Where Decision-Makers Gain Edge: How to Use This Research
The strategic value of this study is highest when it is used to inform multi-layered decisions rather than a single purchase event. For capital planners and facility executives, the forecast structure supports capacity planning by clarifying the pace and shape of market growth across the 2026–2032 window. For engineering and specification teams, the segmentation framework provides a structured way to align chiller type and application context with operating goals, redundancy needs, and environmental constraints. For competitive strategy and sourcing functions, the company profiles and concentration metrics offer a lens into where market power resides and how vendor portfolios are evolving in response to regulatory and performance pressures.
Because the segment is moving on multiple vectors simultaneously—technology advancement, refrigerant compliance, certification rigor, and application growth—decision-makers benefit from a research asset that connects these vectors rather than treating them separately. The report is designed to support that integrative view. It helps teams frame questions such as whether a project's load profile favors a magnetic bearing platform, how regional specification norms affect product selection, and which company portfolios are most aligned with an organization's compliance timeline and operational priorities.
What Is Inside and How to Access the Full Intelligence
The complete study delivers a comprehensive map of the centrifugal chiller market across the 2020–2032 horizon, combining historical revenue context with a detailed forward forecast. It examines market size and growth trajectories, breaks down demand by technology type and application context, and reviews regional dynamics that influence deployment patterns and specification preferences. It further profiles leading manufacturers, evaluates recent product and compliance-driven developments, and integrates the regulatory and technical standards that shape performance validation. Market concentration metrics provide additional context on competitive structure and supplier power.
To preserve the analytical integrity of the forecast model and protect the proprietary structure of our segmentation work, certain detailed split values and regional or application-level breakdowns are reserved for the full report. The summary presented here is intended to demonstrate methodological rigor and strategic relevance while encouraging deeper engagement with the complete dataset. Readers who require precise segment sizing, regional distribution details, application-level revenue context, and company-level positioning data will find those capabilities fully developed in the final document.
Centrifugal Chiller Market
For teams tasked with navigating 2026 planning cycles, the Centrifugal Chiller Market research offers a structured baseline for scenario testing, procurement timing, specification alignment, and competitive benchmarking. By combining macro growth signals with practical decision frameworks, it helps organizations move from general market awareness to targeted action. To access the full report, including detailed segmentation figures, complete company profiles, and the underlying forecast methodology, please visit the source page to retrieve the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Centrifugal Chiller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


