



PW Consulting: Industrial Shredder Market Hits $1.27B in 2025, Projected to Reach $1.77B by 2032 at 4.9% CAGR

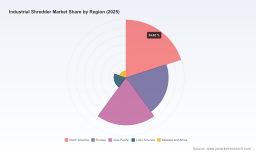
Industrial Shredder Market Outlook 2026: Strategic Intelligence for Capital Allocation and Competitive Positioning
Executive Summary
The industrial shredder sector is entering a phase of disciplined, technology-led expansion. As organizations across recycling, waste management, and secure destruction verticals navigate tightening compliance mandates, input cost volatility, and accelerating decarbonization requirements, capital deployment decisions require more than top-line growth projections. They demand granular visibility into demand drivers, equipment segmentation, regional adoption patterns, and the competitive maneuvers shaping pricing and innovation velocity. Our latest Industrial Shredder Market study delivers that visibility, mapping the trajectory from 2020 through 2032 with a forecasting architecture calibrated to the operational realities of procurement cycles, plant retrofits, and OEM capacity planning.
For decision-makers operating on a 2026 timeline, this research functions as a strategic filter. It separates structural growth from cyclical noise, identifies where margin expansion is realistically achievable, and highlights the operational and regulatory variables that will determine whether a capital investment translates into long-term competitive advantage. Below, we outline the scope of the analysis, the market architecture it reveals, and the actionable intelligence it provides for enterprise strategy teams, equipment procurement leaders, and investment stakeholders.
Market Trajectory: A Multi-Year Expansion Built on Structural Demand
Over the historical window from 2020 to 2025, the industrial shredder market established a consistent upward arc, reflecting sustained investment in material recovery infrastructure, confidential waste processing, and volume-reduction systems across industrial and municipal environments. The base year closes at a revenue level of approximately 1,268 million USD, representing a meaningful step beyond the pre-2023 baseline. That momentum carries into 2026, with the market positioned at roughly 1,295 million USD as operational budgets normalize, replacement cycles accelerate, and new compliance-driven procurement enters the pipeline.
Looking ahead across the 2026–2032 forecast window, the trajectory compounds at a steady pace. The overall market is projected to reach close to 1,773 million USD by 2032, translating to a forecast-period CAGR of 4.9 percent. This growth profile does not suggest a speculative surge; rather, it reflects compounding demand from end-use sectors that depend on size-reduction equipment as core operational infrastructure. For strategic planners, the implication is clear: industrial shredders are no longer peripheral tools but critical assets whose selection, procurement timing, and technology configuration have direct consequences for throughput efficiency, total cost of ownership, and downstream compliance performance.
The research emphasizes that the growth curve will not be uniform across all equipment classes or end-use categories. Instead, it is being shaped by diverging requirements around material hardness, particle-size outcomes, energy intensity, and regulatory documentation standards. As a result, the strategic question for 2026 is not simply where the market is heading, but which segments are best positioned to capture disproportionate value and which operational parameters should govern capital allocation.
Strategic Segmentation: Why Configuration and Application Matter More Than Ever
A central contribution of this study is its detailed breakdown of demand by equipment configuration and application context. These dimensions matter because they directly influence capacity selection, maintenance intensity, throughput consistency, and return-on-investment timelines. The findings show that double-shaft systems have emerged as a dominant configuration within the overall equipment base, reflecting their widespread applicability for metals, plastics, wood, tires, and mixed waste streams. Single-shaft and three-shaft designs continue to play specialized roles where controlled particle sizing, material separation, or operational flexibility is prioritized. Four-shaft configurations occupy a narrower but strategically important niche where high consistency and intensive volume reduction are required.
On the application side, the market is shaped by several core demand streams. Scrap metal recycling remains the largest end-use driver, underpinned by the ongoing need for efficient downsizing of ferrous and non-ferrous scrap prior to melting and reprocessing. WEEE recycling represents a significant and expanding application, reflecting both regulatory pressure and the materials recovery value embedded in electronic and electrical waste. Wood waste recycling, paper waste recycling, and a range of additional applications round out the demand base, each with distinct operational requirements around output grading, contamination handling, and equipment wear.
What this segmentation reveals for 2026 strategy is that purchasing decisions cannot be made on a single specification sheet. A facility prioritizing high-volume scrap processing may benefit from robust multi-shaft configurations with high wear-resistance characteristics, while an operation focused on confidential document destruction or specialized material recovery may need different installation profiles, control architectures, and documentation-capable output standards. The study quantifies these dynamics and links them to demand share, equipment value distribution, and the practical implications for capacity planning—details that procurement teams can translate directly into specification requirements and vendor evaluation criteria.
Competitive Dynamics and the Battle for Differentiation
The industrial shredder landscape is moderately concentrated, with the leading firms commanding a meaningful share of total revenue and leveraging established engineering capabilities, service networks, and regional presence. The report profiles a competitive set that includes Shred-Tech, Vecoplan, SSI Shredding Systems, Franklin Miller, UNTHA, BCA Industries, Zato North America, Williams Patent Crusher & Pulverizer Co., SatrindTech Srl, and Allegheny Shredders. These organizations are not competing on price alone; they are contesting the market through product architecture, application specialization, service responsiveness, and the ability to align equipment performance with the operational constraints of each end-use segment.
Recent developments make the competitive rhythm especially visible. In 2025, SSI Shredding Systems introduced a new SR900F shredder designed for high-volume RDF production, reinforcing the continued link between shredding capacity and alternative fuel feedstock preparation. That same year, SSI exhibited at PPRC 2025 in Chicago, underscoring the importance of trade channels in shaping buyer expectations and technology diffusion. In 2026, UNTHA showcased two new machine designs alongside the latest evolution of its XR series at IFAT Munich, signaling continued investment in design refinement and application versatility. Meanwhile, Franklin Miller completed a notable TASKMASTER TM4000 shredder installation, highlighting the operational relevance of high-capacity systems in real-world processing environments.
Industrial Shredder Market
Worldwide kitchen Waste Shredder Market
These events are more than product announcements; they are indicators of where the market is moving. OEMs are increasingly orienting development toward energy efficiency, material compatibility, throughput reliability, and ease of integration into broader recycling or destruction workflows. For enterprises evaluating suppliers, that shift changes the evaluation framework. Technical specifications still matter, but so do control-system intelligence, service accessibility, parts availability, and the vendor’s ability to support compliance documentation and long-term operating efficiency. The study examines these competitive levers in detail, connecting them to pricing posture, installed-base considerations, and the strategic positioning of each major player.
Operational Realities Shaping Demand and Procurement Decisions
Behind the headline growth figures lies a set of operational variables that directly influence equipment selection and total cost of ownership. One of the most practical considerations is cutter and blade material performance. High-wear alloy cutters used in industrial shredder blades typically cost 15–30 percent more than baseline D2 steel, but they deliver materially longer service life in impact-prone applications. For facilities running mixed loads, abrasive waste streams, or high-throughput metal processing, that upfront premium can substantially reduce downtime and maintenance frequency. The report assesses when such premium components are strategically justified and how they affect lifecycle cost modeling.
Energy performance is another increasingly decisive factor. New industrial shredder models are delivering up to 15 percent energy savings through smart control technologies, a substantial improvement for installations where power intensity and operating hours drive recurring costs. As organizations face both economic and sustainability targets, control-system intelligence, load optimization, and process automation are becoming key differentiators in vendor selection. The study analyzes how these efficiency gains influence operating economics and whether they are sufficient to alter the evaluation calculus for new installations versus retrofits.
Safety and compliance also remain critical inputs to procurement strategy. OSHA incident records underscore the operational risk environment, documenting an amputation of an employee’s hand caused by an industrial shredder. That kind of incident reinforces the importance of engineered safeguards, operator training, interlock design, and site-specific risk management protocols. At the same time, confidentiality and destruction standards are tightening in specific application areas. The UNE EN 15713 standard establishes recommendations for the management and control of confidential document destruction processes using industrial shredders, while UNE 15713 provides post-destruction information confirming the type of industrial shredder used to divide documents into portions barely containing two letters. These standards matter not only for compliance teams but also for equipment specification, because they influence output requirements, traceability expectations, and the documentation capabilities buyers demand from their shredding systems.
Taken together, these dynamics mean that the 2026 procurement process is increasingly multidisciplinary. Engineering teams must consider wear performance and energy optimization; environmental and compliance teams must factor in destruction documentation and recycling output requirements; and operations leaders must integrate safety, maintenance access, and service reliability into the final selection. The report is structured to support that cross-functional decision-making by aligning equipment analysis with the operational realities buyers face on the plant floor.
What the Study Delivers: Practical Intelligence for 2026 Decision-Making
This Industrial Shredder Market research is designed to convert macroeconomic and competitive signals into a usable decision framework. Rather than offering a single aggregate number, it builds a layered picture of demand, equipment configuration, application distribution, regional structure, and competitive performance. The analytical scope includes historical size evolution, forecast modeling through 2032, and segmentation that shows how value and volume are distributed across equipment types and end-use applications.
Key practical outputs include:
- A structured view of market size progression from 2020 through the 2026–2032 forecast horizon, enabling planners to benchmark internal expectations against the broader industry trajectory.
- Segment-level demand architecture across equipment configurations and application categories, helping procurement teams match specifications to actual operating conditions rather than generic requirements.
- Competitive profiles and recent development tracking for major OEMs, giving strategy and sourcing teams context on product evolution, installation activity, trade-show presence, and technology direction.
- Operational and regulatory context that influences equipment performance, maintenance, safety, and compliance documentation, supporting more realistic total cost of ownership models.
- Insights into efficiency trends, material-handling requirements, and the cost-performance trade-offs that affect whether a buyer should prioritize throughput, particle-size control, energy savings, or wear resistance.
Importantly, the study is built to support scenario planning. Because market growth is shaped by multiple variables—material recovery demand, regulatory tightening, energy and input cost dynamics, and technology adoption—decision-makers need the ability to test assumptions against different operational contexts. The report provides that flexibility by connecting aggregate market structure to the practical choices that determine project success, whether the priority is secure destruction, scrap preparation, WEEE processing, wood waste reduction, paper recovery, or broader mixed-waste downsizing.
How to Use This Research in 2026 Planning Cycles
For executives and analysts entering 2026 planning, this study is useful in several concrete ways. It supports capital budgeting by clarifying where demand is structurally strongest and how equipment classes align with those demand centers. It strengthens vendor evaluation by situating supplier activity within a competitive landscape defined by recent launches, installations, and application-specific development. It improves risk management by integrating safety incidents, compliance standards, wear-material economics, and energy-efficiency improvements into the equipment selection conversation. And it sharpens strategic positioning by revealing where concentration, specialization, and technology differentiation are likely to influence pricing and service competitiveness over the forecast period.
The full analysis contains the detailed segmentation structures, regional breakdowns, application-level market values, and competitive assessments needed to convert strategic objectives into procurement, investment, and sourcing decisions. Because the granular figures, subsegment allocations, and proprietary interpretations are central to the report’s value proposition, this preview intentionally highlights the analytical framework and the decision-relevant themes without reproducing the full dataset.
Whether your objective is to evaluate new equipment investment, reassess existing shredding capacity, benchmark supplier options, or align sustainability and compliance targets with operational realities, the complete study provides the depth required to move from market awareness to informed action.
Next Steps
To access the full market sizing, segmentation detail, competitive analysis, and forecast interpretation, readers are encouraged to explore the complete Industrial Shredder Market report. The complete version delivers the underlying figures, regional and application-level intelligence, and strategic context needed to support 2026–2032 planning with precision.
For detailed analysis of this topic, please visit the official page: Industrial Shredder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


