



PW Consulting: Commercial Ice Machine Market to Hit $332M by 2032 on 7.45% CAGR

Beyond Thermal Output: Strategic Intelligence for the 2026 Commercial Ice Machine Market
The commercial ice machine sector has quietly transitioned from a commoditized utility play to a capital-intensive, regulation-sensitive infrastructure decision. Across foodservice, healthcare, and retail environments, ice systems are no longer evaluated solely on daily production capacity. Facility managers, procurement officers, and capital equipment planners now weigh energy compliance, refrigerant transitions, sanitation certification, and total cost of ownership against volatile supply chain conditions. As we move deeper into the 2026–2032 forecast window, the organizations that will secure margin protection and operational continuity are those making their ice equipment decisions with granular, forward-looking intelligence rather than historical benchmarks.
PW Consulting’s newly released Commercial Ice Machine Market research is structured as a decision-grade intelligence asset. It moves past surface-level market commentary to deliver executable procurement roadmaps, competitive positioning frameworks, and regulatory readiness checklists. The following overview outlines what the study covers, why the 2026 decision window is structurally distinct, and how leadership teams can translate market velocity into risk-adjusted capex and opex strategy. The core segment valuations, regional breakouts, and proprietary forecasting layers are reserved for the full report, where the complete analytical architecture can be navigated without dilution.
A Market in Structural Expansion: Why 2026 Is a Pivotal Inflection Point
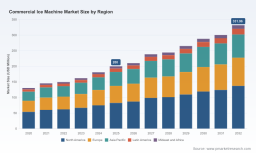
The commercial ice machine market has demonstrated consistent expansion over the past half-decade, with revenue compounding from approximately USD 130.5 million in 2020 to an estimated USD 200.0 million in 2025. The trajectory reflects more than post-pandemic normalization. It signals a durable alignment between hospitality recovery, healthcare sanitation mandates, retail cold-chain sophistication, and industrial cold processing requirements. Looking forward, the forecast period extends through 2032, with market revenue projected to surpass the USD 330 million threshold by the close of the outlook window. This expansion is supported by a CAGR of 7.45 percent, a pace that places ice equipment alongside other commercial kitchen and facility infrastructure categories experiencing sustained institutional demand.
Commercial Ice Machine Market
Ice Cream Machine Market
For enterprise planners, a double-digit compound growth trajectory carries a specific strategic implication: delay is expensive. Capacities installed in 2026 will remain in operation well into the next decade, and the operating environment those machines face will be shaped by tightening energy expectations, evolving refrigerant policy, and heightened sanitation enforcement. The report uses the full 2020–2032 timeline to frame not just where the market has been, but which cohorts of demand are structurally permanent versus which are cyclical. Decision-makers are given a calibrated view of how near-term procurement cycles interact with long-lived asset exposure, enabling more disciplined budgeting across multi-year capex programs.
Competitive Architecture: Concentration, Positioning, and the Strategic Playbook
The commercial ice equipment landscape is not a fragmented free-for-all. Market concentration metrics underscore a consolidated environment in which a relatively small group of manufacturers commands the majority of share. The report examines this structure through the lens of competitive moats, channel leverage, and innovation cadence rather than simple shipment rankings. With CR3 levels at 65.0 percent and CR5 levels at 85.0 percent, competitive dynamics are defined by brand trust in sanitation-critical environments, dealer and service network density, and the ability to deliver certified, energy-optimized platforms across multiple ice formats.
Several established players anchor this ecosystem. Hoshizaki America, headquartered in Fayetteville, Georgia, manufactures commercial ice machines across flaker, nugget, and cube configurations, with a consistent emphasis on NSF-listed models and energy-efficient options. The company’s recent 2026 product calendar reinforces this positioning: an updated commercial product brochure released in April highlighted improved energy efficiency and hygiene options across 2026 model years, followed in May by an expanded cube ice portfolio under the new IM CUBE series, which incorporates UV sanitization alongside energy and water savings. Such moves illustrate a broader industry pattern in which premium differentiation is increasingly tied to integrated sanitation and resource efficiency rather than production volume alone.
Manitowoc Ice, based in Manitowoc, Wisconsin, focuses on engineered commercial ice machines for foodservice, hospital environments, and high-volume applications, supported by dealer networks that extend service reach and installation fidelity. In May 2026, the company continued its refrigerant transition toward R290 while advancing supply chain optimizations designed to enhance commercial ice machine performance. This trajectory reflects the operational reality that after-sales reliability, parts availability, and service responsiveness often matter as much as the hardware specification itself.
Scotsman Ice Systems, operating from South Carolina, is recognized globally as a leading manufacturer of commercial ice machines, offering modular and countertop models with a clear focus on foodservice reliability. Ice-O-Matic, also U.S.-based, specializes in commercial ice machines and dispensers built around modular designs tailored to restaurants and institutions. Grant Ice Systems manufactures industrial and commercial units, including nugget and flake types designed for high-capacity requirements. Follett Ice delivers commercial ice machines and dispensers with integrated technology aimed at foodservice operations, while Maxx Ice offers self-contained and premium indoor/outdoor commercial ice machines, several with Energy Star listings. Summit Appliance produces commercial ice makers certified to NSF-12, with production ranges spanning from 55 lb to 210 lb. Outside the U.S. incumbent core, Naixer Ice, based in China, serves as a global supplier of commercial ice makers with NSF certification and product catalogs designed for international distribution. Morris Thermal rounds out the competitive field by producing custom industrial ice makers with Tube-Cube and Nugget technologies suited to food processing and high-volume use.
The report does not stop at company profiles. It maps how these players compete across product families, service architectures, and compliance readiness, and it highlights where concentration creates pricing discipline versus where niche innovation can still open addressable pockets. This structure is especially valuable for procurement teams evaluating not only unit cost but the strategic risk of vendor lock-in, parts dependency, and long-term service support across dispersed locations.
Regulatory Dynamics, Certification Realities, and the 2026 Compliance Landscape
One of the most consequential layers of the 2026 decision environment is regulatory and certification pressure. Commercial ice machines sit at the intersection of energy policy, refrigerant mandates, and food safety standards, making compliance a design constraint rather than an optional add-on. As of May 2026, commercial ice machines must meet ENERGY STAR performance specifications or equivalent performance thresholds if not labeled as such. In parallel, Florida Water Star has required these standards for appliances, tying water and energy efficiency into broader building and equipment approval frameworks. For multi-site operators with exposure to these jurisdictions, the implication is straightforward: efficiency performance is becoming a purchasing prerequisite, not merely a sustainability talking point.
Refrigerant transitions are equally influential. In November 2025, Hoshizaki transitioned 66 of its ice maker models to R-600a and R-290 refrigerants, achieving over a 99 percent reduction in global warming potential. This shift reflects a wider industry migration toward lower-GWP alternatives and demonstrates how OEMs are redesigning platforms to align with both federal direction and customer expectations around environmental footprint. The EPA SNAP rule further shapes the market by allowing specific refrigerants, including HFC-32, R-454A, R-454B, R-454C, R-455A, R-457A, and R-516A, for use in new commercial ice machines under defined conditions. Compliance with these pathways requires vendors and buyers alike to track approval conditions and equipment eligibility, especially as state-level timelines and federal requirements interact.
Certifying bodies add another layer of non-negotiable scrutiny. NSF/ANSI Standard 12 certification is mandatory for all U.S. commercial ice machines sold in foodservice to ensure sanitation and food safety compliance. This requirement creates a structural barrier to entry for unverified equipment and makes certification status a baseline procurement filter. On the regulatory timing side, the Washington Department of Ecology issued an interpretive statement in December 2024 delaying the HFC prohibition effective date for automatic commercial ice machines to align with federal 2026–2027 requirements. The interplay of federal and state regulatory calendars means that what appears to be a single compliance decision often requires multi-jurisdiction validation. The report organizes these dynamics into actionable categories so that facility and procurement leaders can map equipment selection to the specific standards that govern their locations and use cases.
What the Report Delivers: An Operational Intelligence Framework
PW Consulting’s Commercial Ice Machine Market study is designed for teams that need more than directional market commentary. The deliverable combines macroeconomic trajectory, product-form dynamics, application-driven demand behavior, regional performance context, and competitive profiling into a coherent planning tool. The research architecture is built around several practical components.
- Historical baseline and forecast modeling spanning 2020 through 2032, providing a continuous revenue view that supports budgeting, capacity planning, and trend validation across multiple forecast vintages.
- Product-form analysis across cube, flake, nugget, and other configurations, examining how production footprint, ice characteristics, and operational use cases drive adoption across foodservice, healthcare, retail, and industrial settings.
- Application-based demand mapping that distinguishes between high-volume commercial foodservice requirements, healthcare sanitation-sensitive environments, retail point-of-use needs, and broader institutional or industrial deployments.
- Regional context that situates market performance across major geographies without forcing simplistic generalizations, helping multinational operators and domestic chains calibrate rollout priorities based on infrastructure maturity, regulatory exposure, and demand density.
- Competitive profiling of leading manufacturers and emerging suppliers, including product positioning, certification posture, and recent innovation or catalog activity, enabling side-by-side evaluation of vendor options and service implications.
- Regulatory and certification tracking that consolidates ENERGY STAR expectations, SNAP-listed refrigerant pathways, state-level interpretive actions, and NSF/ANSI Standard 12 requirements into a usable compliance overview for procurement teams.
- Decision-support frameworks that translate market information into purchasing criteria, replacement-cycle logic, and vendor-selection checklists aligned to operational continuity and total cost of ownership.
This structure is intentionally practical. It is not a static market snapshot but a tool that supports recurring decisions: whether to replace aging units now or stage the transition; how to weigh efficiency-certified platforms against upfront cost; which product formats align with specific site profiles; and how to interpret competitive moves such as refrigerant migrations, UV sanitization integration, and modular design refinements. By tying these considerations to a single research baseline, the report reduces the risk of fragmented decision-making across departments that often evaluate equipment from different angles.
Why the Full Intelligence Set Matters for 2026 Procurement and Planning
Strategic procurement in a market growing at a mid-to-high single-digit CAGR is not simply a matter of identifying the cheapest compliant unit. The real decision space includes service network coverage, spare-parts availability, energy-cost exposure over the machine’s service life, regulatory drift, and the operational consequences of choosing a platform that may not align with future certification or efficiency expectations. In a market where a concentrated group of manufacturers controls a substantial share, vendor selection also carries concentration risk and dependency considerations that should be weighed explicitly rather than inferred from spec sheets alone.
The report is built to support that level of evaluation. It gives teams a structured way to interpret market momentum, segment behavior, competitive responses, and compliance shifts without relying on fragmented sources or outdated assumptions. The full study preserves the detailed segment valuations, regional performance context, application-level demand breakdowns, and forward forecasting layers that enable scenario-based planning. Those components are essential for organizations that need to justify capex against auditable market evidence, compare vendors on a consistent basis, and anticipate how regulation and technology will reshape operating economics through 2032.
Navigating the Market with Proven Strategic Intelligence
The commercial ice machine market in 2026 rewards teams that plan with precision. Growth is real, concentration is high, and the regulatory environment is actively reshaping product design and procurement criteria. In that context, the difference between reactive replacement and strategic deployment is information quality. PW Consulting’s Commercial Ice Machine Market research is intended to provide that information in a form that procurement, operations, and finance leaders can use immediately.
The complete report includes the full market sizing arc, segment-level insight, regional performance context, competitive analysis, and the compliance and certification frameworks that define viable equipment selection in the current period. For organizations preparing multi-site deployments, lifecycle replacements, or technology refresh cycles, the full intelligence set offers the depth required to make decisions with confidence rather than approximation. The core data, scenario-ready forecasts, and category-specific evaluations are available through the complete study, where the analytical detail and proprietary market architecture can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Commercial Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


