



PW Consulting Report: Packaged Substation Market to Reach $338M by 2032 with 6.5% CAGR

Executive Summary: Navigating the Packaged Substation Market Opportunity
The global energy landscape is undergoing a structural transformation. As electrification accelerates across industrial, infrastructure, and utility sectors, the demand for reliable, scalable, and rapidly deployable power distribution solutions has never been more critical. At PW Consulting, we recognize that the packaged substation market represents a pivotal intersection of grid modernization, smart infrastructure development, and operational efficiency. Our latest market research report on the Packaged Substation Market delivers a comprehensive, data-driven analysis designed to equip executive teams, investors, and strategic planners with the intelligence required to navigate this evolving landscape through 2032 and beyond.
This report is not merely a retrospective of historical performance. It is a forward-looking strategic instrument built on rigorous quantitative modeling, primary research validation, and deep competitive intelligence. Drawing on historical tracking from 2020 through the base year of 2025, and extending our forecasts across an eight-year period from 2026 to 2032, the study captures both the trajectory that has shaped the market and the inflection points that will define its next phase of growth. The overarching narrative is one of sustained expansion, where market valuation has demonstrated consistent upward momentum and is projected to reach new milestones as deployment cycles accelerate across multiple geographies and application verticals.
What sets this analysis apart is its emphasis on actionable strategic insight. We do not simply report numbers; we contextualize them within operational realities, regulatory shifts, supply chain dynamics, and technological adoption curves. The following sections outline the core components of the research, the competitive forces at play, the regulatory and macro-environmental drivers reshaping procurement and deployment strategies, and the strategic decisions that industry leaders must address in 2026 and beyond.
Market Trajectory and Structural Growth Dynamics
The packaged substation sector has transitioned from a niche, project-driven segment to a mainstream component of modern power distribution architecture. Historical tracking over the past half-decade reveals a market that has steadily expanded in both volume and strategic importance, reflecting broader electrification trends, grid reliability mandates, and the growing preference for prefabricated, modular deployment models over traditional on-site construction approaches. Our baseline assessments place the market at a substantial valuation in the base year, with continuous year-over-year progression underscoring the durability of underlying demand drivers.
The growth trajectory extends well beyond short-term cyclical recovery. Forecast modeling across the 2026–2032 horizon indicates a compound annual growth rate that reflects sustained momentum rather than a temporary surge. This expansion is not evenly distributed; it is shaped by differentiated adoption curves across regional markets, varying procurement timelines in industrial and infrastructure development programs, and the phased integration of new substation technologies into legacy grid architectures. Early forecast years already demonstrate incremental value gains, with growth compounding as manufacturing scale, supply chain localization, and deployment experience reduce lead times and improve project economics.
Packaged Substation Market
A critical element of the forecast methodology is its sensitivity to real-world constraints. Material cost fluctuations, labor availability, permitting frameworks, and the pace of renewable integration all exert measurable influence on deployment pacing and value realization. By incorporating these variables into scenario-based modeling, the report equips stakeholders with a realistic framework for capital allocation, inventory planning, and partnership positioning. The result is a market outlook that balances optimism with operational pragmatism, enabling decision-makers to plan for both baseline growth and upside opportunities tied to accelerated infrastructure programs and technology adoption.
Competitive Landscape and Strategic Positioning
The competitive architecture of the packaged substation market is defined by a blend of global technology leaders, specialized electrical equipment manufacturers, and regional players with deep integration into local infrastructure and utility ecosystems. Market concentration metrics indicate a moderately fragmented environment, where the top three and top five players collectively hold meaningful but not dominating shares, leaving substantial room for differentiated positioning through technology, service models, and regional execution capability.
At the forefront of the market are organizations that have aligned their product portfolios with broader grid modernization priorities. ABB Ltd, headquartered in Zurich, has positioned itself around advanced compact and modular substation designs engineered for smart grid applications, high-reliability power distribution, and optimized operational performance across diverse electrical networks. Siemens Energy AG, based in Munich, has developed prefabricated substation solutions tailored for metro rail, EV charging, and renewable energy integration, aligning its offerings with mobility electrification and clean energy transitions. Schneider Electric SE, operating from Rueil-Malmaison, focuses on medium-voltage and low-voltage package substations designed for industrial and utility distribution, emphasizing integration, protection, and control architectures that support distributed energy resources.
Eaton Corporation, headquartered in Dublin, brings electrical distribution solutions that span package substations for industrial facilities and infrastructure, with an emphasis on operational resilience and system-level efficiency. In Asia, a strong cohort of manufacturers has expanded its footprint through integrated electrical solutions and scaled production. Larsen & Toubro Ltd, Kirloskar Electric Company Ltd, CG Power and Industrial Solutions Ltd, and C&S Electric Limited each contribute distinct capabilities across power distribution, industrial projects, and utility applications, reinforcing the region's role as both a major demand center and an increasingly competitive manufacturing base.
Global technology and heavy electrical players also maintain significant relevance. Hyundai Electric, Toshiba Corporation, and Hitachi Energy Ltd offer medium-voltage and low-voltage packaged substations, transmission and distribution equipment, and eco-efficient modular products that support renewable integration and higher-voltage applications. CHINT Group, based in Ningbo, has emerged with modular prefabricated substations featuring integrated components designed for rapid deployment and reliability, while Lucy Electric contributes switchgear and packaged substation solutions for power distribution networks.
Recent corporate and project activity illustrates how competitive differentiation is being executed in practice. In mid-2025, State Grid Anyang Power Supply Company commissioned Linzhou's first 110 kV mobile substation, a 50 MVA prefabricated unit installed within a ten-day window and deployed to supply industrial load alongside new-energy charging stations. That same year, CHINT Group introduced modular prefabricated substations emphasizing factory assembly, third-party type testing, and customized designs for extreme environments, followed by a later delivery of an integrated MV skid solution for the MASDAR Bukhara 250 MW Solar PV Plant in Uzbekistan. Hitachi Energy announced plans to deliver the world's first SF6-free 550 kV GIS, signaling a broader shift toward eco-efficient substation advancements, while Schneider Electric initiated localization of modular substation production in Asia to strengthen supply chain reliability and reduce lead times. These developments underscore a competitive environment in which speed, certification, environmental performance, and regional manufacturing capability are becoming decisive advantages.
Technological, Regulatory, and Macroeconomic Drivers
The packaged substation market does not evolve in isolation. Its growth profile is closely tied to a cluster of technological, regulatory, and macroeconomic forces that are reshaping how power is generated, transmitted, distributed, and consumed. Understanding these drivers is essential for mapping both near-term procurement behavior and longer-term portfolio strategy.
From a technological standpoint, modularization and factory-based fabrication have become central value propositions. Prefabricated, box-type, and skid-mounted substation designs offer measurable reductions in overall project cost and installation time compared with traditional brick-and-mortar construction approaches. Factory-built configurations also reduce on-site labor requirements by substantial margins through pre-testing and modular assembly, which is particularly relevant in markets experiencing skilled labor constraints or where rapid commissioning is required to support industrial expansion and infrastructure timelines. In parallel, the push toward eco-efficient substation technologies is accelerating, with high-voltage gas-insulated switchgear innovations and SF6-free agendas moving from research emphasis to commercial readiness.
Regulatory frameworks are exerting both standardizing and enabling effects. International standards such as IEC 62271-202:2022 define service conditions, rated characteristics, general structural requirements, and test methods for enclosed high-voltage prefabricated substations, providing a common technical baseline that supports cross-border procurement, interoperability, and quality assurance. On the policy front, European Commission guidance issued in mid-2025 emphasizes ensuring electricity grids are fit for the future, offering incentives for anticipatory investments in grid reinforcements and substation capacity. In the United States, executive action from mid-2025 prioritizes accelerating federal permitting for data center infrastructure, including substations and switchgear, directly linking substation deployment to the rapid expansion of digital infrastructure and computational load.
Emergency Mobile Substation Market
Material and labor economics further influence adoption decisions. The financial case for packaged substations is strengthened by demonstrable cost avoidance in site construction, shortened deployment schedules, and reduced exposure to on-site execution risk. These advantages are especially pronounced in industrial and infrastructure applications where downtime minimization, spatial constraints, and schedule certainty carry significant operational and financial implications. As a result, procurement strategies are increasingly shifting from lowest-unit-price evaluations toward total-lifecycle and total-project-value assessments, in which reliability, lead time, commissioning speed, and environmental compliance all contribute to the final decision calculus.
Core Report Framework and Strategic Deliverables
The Packaged Substation Market report is structured to translate complex market data into clear strategic guidance. It is designed for executives who require both breadth and precision without being overwhelmed by undifferentiated data tables. The report integrates historical analysis, forward-looking forecasts, segmentation insights, competitive profiling, and scenario-based interpretation into a cohesive analytical framework.
At the core of the study is a detailed market size and growth analysis anchored in historical performance from 2020 through 2025 and extended across the forecast period to 2032. Revenue trends are examined in a standardized global currency, enabling consistent comparison across periods and supporting financial planning, demand forecasting, and investment scenario modeling. The analysis captures how value has accumulated over time and how it is expected to compound as deployment activity broadens across regions and end-use environments.
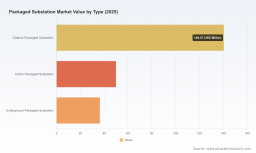
Segmentation is treated as a strategic lens rather than a static taxonomy. The report examines the market across multiple dimensions that matter to procurement, manufacturing, and distribution planning. This includes an evaluation of deployment configurations and engineering forms, reflecting the differing requirements of outdoor, indoor, and underground applications; a geographic breakdown that illuminates relative market weight and growth pacing across major regions; and an application-level analysis that differentiates demand patterns across industrial environments, infrastructure programs, and power generation and utility operations. Each segmentation view is contextualized with demand drivers, adoption constraints, and strategic implications, allowing readers to identify where opportunity is concentrated and where execution risk may be elevated.
Competitive intelligence is developed through company-level profiling that goes beyond headline positioning. Profiles capture each organization's specific offering logic, technological emphasis, and application focus, providing a basis for benchmarking, partnership evaluation, and threat assessment. The report also incorporates recent developments that illustrate how companies are translating strategy into action through product launches, project deliveries, supply chain localization, and technology announcements. This dynamic view of competition helps stakeholders anticipate vendor behavior, pricing pressure, and differentiation trends rather than reacting to them after the fact.
Beyond structure and segmentation, the report includes practical tools for strategic planning. These encompass demand-side interpretation for capital and capacity planning, supply-side considerations for manufacturing and sourcing strategy, and environmental and regulatory mapping for compliance and ESG alignment. Scenario framing supports sensitivity analysis around lead times, cost structures, and deployment pacing, giving decision-makers a way to test assumptions before committing resources.
Strategic Implications for 2026 Decision-Making
As organizations enter 2026, the packaged substation market presents a set of strategic choices that extend well beyond traditional procurement considerations. The convergence of grid modernization mandates, renewable integration requirements, digital infrastructure expansion, and modular deployment economics is reshaping how value is created and captured across the value chain. Companies that approach this environment with a clear strategic posture will be better positioned to convert market growth into durable advantage.
One immediate implication concerns portfolio and capacity alignment. With growth forecasts indicating steady expansion over the forecast horizon, organizations must evaluate whether current production capacity, sourcing arrangements, and service capabilities are sufficient to meet accelerating demand without compromising reliability or margin. For manufacturers, this raises questions about factory throughput, component standardization, certification pathways, and regional localization. For distributors and system integrators, it raises questions about inventory positioning, lead-time management, and the ability to offer integrated solutions rather than standalone equipment.
A second implication relates to competitive differentiation. In a market where top-tier concentration remains moderate, differentiation increasingly depends on technology integration, deployment speed, environmental performance, and regional execution quality. Firms that can demonstrate credible advantages in factory-based testing, modular configuration, rapid commissioning, and eco-efficient design are better placed to compete on total project value rather than price alone. Recent moves toward localized production and advanced substation technologies illustrate how manufacturers are attempting to secure both cost and credibility advantages simultaneously.
A third implication centers on demand-side planning. Industrial operators, infrastructure developers, and utility organizations must assess how substation deployment timing interacts with broader project schedules, permitting pathways, and load growth expectations. The availability of prefabricated options that reduce on-site labor, accelerate installation, and align with recognized international standards can materially affect project feasibility and risk profiles. Decision-makers should therefore evaluate substation sourcing not merely as an equipment purchase but as a schedule, reliability, and compliance decision that influences downstream operational outcomes.
Finally, regulatory and environmental trends warrant proactive strategy development. Standards development, incentives for grid reinforcement, permitting acceleration for critical infrastructure, and the broader transition toward lower-impact substation technologies are all shaping future procurement requirements. Organizations that integrate these considerations into product roadmaps, sourcing strategies, and project planning will be better prepared to navigate compliance expectations and capture incentives tied to anticipatory investment.
Conclusion and Call to Action
The packaged substation market is at a point where structural demand, technological maturation, and policy support are aligning to sustain a multi-year growth trajectory. Historical performance establishes a credible foundation, and forward-looking modeling suggests that the momentum will continue as deployment models become more efficient, regional manufacturing expands, and grid modernization priorities intensify. Yet the strategic value of this market lies not only in its size and growth rate but in the way it intersects with broader energy, industrial, and infrastructure decisions.
PW Consulting's Packaged Substation Market report is designed to help leaders navigate that complexity with confidence. It combines rigorous quantitative analysis with practical competitive and regulatory context, enabling organizations to identify where to invest, how to differentiate, and which risks to manage proactively. The full report provides detailed segmentation interpretation, competitive benchmarking, scenario analysis, and development tracking that go beyond the executive overview presented here.
For executives, investors, and strategy teams seeking a complete view of market sizing, segmentation dynamics, competitive positioning, and forward-looking implications through 2032, we invite you to access the full research on our website. The complete intelligence package is structured to support capital planning, market entry evaluation, partnership strategy, and operational decision-making with the depth and precision required for high-stakes 2026 planning.
For detailed analysis of this topic, please visit the official page: Packaged Substation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


