



PW Consulting: Raised Access Floor Market Hits $1.66B in 2025, Projected to Reach $2.4B by 2032

Strategic Foundations Beneath the Surface: Why the Raised Access Floor Market Demands Executive Attention in 2026
Modern enterprise infrastructure is undergoing a quiet but irreversible transformation. As data centers scale to accommodate artificial intelligence workloads, commercial offices reconfigure around hybrid work models, and clean room facilities tighten environmental controls, the raised access floor has evolved from a passive architectural element into a critical enabler of operational resilience. At PW Consulting, we recognize that leaders who understand the structural shifts in this market gain a decisive advantage in capital allocation, vendor selection, and long-term facility planning. This introduction to our newly released Raised Access Floor Market research study outlines the strategic rationale behind our analysis, previews the actionable intelligence embedded in the full report, and explains why 2026 represents a pivotal inflection point for stakeholders across real estate, IT infrastructure, and construction sectors.
The Macro Trajectory: A Market Built on Sustained Expansion
The raised access floor sector has demonstrated remarkable consistency through cycles of supply chain volatility, shifting construction demand, and evolving technical specifications. Historical tracking from 2020 through 2025 reveals a steady revenue progression, moving from just over USD 1.27 billion to approximately USD 1.66 billion by the base year. This trajectory reflects more than incremental growth; it signals a structural recalibration of how organizations design indoor environments to support power distribution, airflow management, and modular reconfiguration. Looking forward, our forecast model projects the market to surpass USD 1.8 billion in 2026 and continue its upward path toward USD 2.4 billion by 2032. The compound annual growth rate of 5.41 percent underscores a mid-to-high single-digit expansion phase that is neither speculative nor overly aggressive, but rather anchored in tangible facility modernization requirements and sustained commercial construction activity.
For decision-makers, this growth pattern carries immediate implications. It suggests that demand is not concentrated in a single vertical or geography, but rather distributed across multiple end-use environments that are simultaneously upgrading their physical infrastructure. It also indicates that procurement strategies relying on short-term price optimization may overlook the broader value of system longevity, maintainability, and compatibility with next-generation cooling and networking architectures. Our analysis is designed to help executives distinguish between temporary market fluctuations and durable investment themes.
What the Full Study Delivers: Operational Intelligence, Not Just Headlines
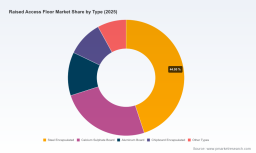
Market summaries often stop at top-line figures, but effective strategy requires granular visibility into how value is created, captured, and contested. The complete PW Consulting report is structured to provide exactly that depth. Readers will find a methodical dissection of product architectures, including steel encapsulated platforms, calcium sulphate board systems, aluminum variants, chipboard encapsulated options, and other specialized constructions. Each material pathway presents distinct trade-offs in load capacity, acoustic performance, moisture resistance, and installation logistics. The study maps these characteristics against real-world deployment scenarios so that procurement leaders and facility architects can align specification choices with operational priorities rather than defaulting to legacy standards.
Equally critical is the application-layer analysis. Data centers, commercial offices, clean rooms, institutional buildings, and other use cases each impose unique performance thresholds. Our research evaluates how raised access flooring systems are specified, tested, and maintained across these environments, highlighting where design flexibility matters most and where standardization yields measurable cost efficiencies. Regional demand patterns are examined through the lens of construction pipelines, regulatory environments, and local supply chain maturity, enabling multinational corporations and regional developers alike to calibrate their market entry or expansion strategies with precision. The report also integrates competitive benchmarking, pricing architecture reviews, and supply chain sensitivity assessments that translate directly into tender preparation, vendor negotiations, and lifecycle cost modeling.
Competitive Posture: How Leading Players Are Shaping the Landscape
The raised access floor market is characterized by a balanced concentration structure, with the top three participants accounting for approximately forty percent of revenue and the top five collectively holding around half of total market share. This dispersion signals a competitive arena where scale, technical differentiation, and regional execution capability all matter. Several established and emerging players have carved out recognizable positions by emphasizing distinct value propositions, and our study tracks how these strategic postures are evolving in response to customer demands and macroeconomic pressures.
Tate Global, headquartered in the United Kingdom, has built recognition around innovative raised access flooring solutions tailored for commercial offices and data centers, emphasizing configuration adaptability and integration with modern workplace layouts. DIRTT, based in Canada, addresses the growing need for low-profile access floors with integrated power and data distribution, effectively converging flooring infrastructure with structured cabling and power management. In the high-load segment, Rhino Technologies Co., Ltd. of the United States has focused on engineered steel panel systems designed specifically for demanding data center environments, where structural integrity and load distribution are non-negotiable. Across the Asia-Pacific manufacturing base, Polygroup has emphasized adjustable pedestal systems that streamline installation and enable precise height calibration, while Titanflor has positioned its offerings for broader industrial and commercial projects that require durable, repeatable floor systems. Huilian Flooring, also based in China, has pursued a differentiated path by combining raised access flooring systems with ceramic finishes, targeting environments where surface durability and cleanability are paramount. Meanwhile, Access Floors Distribution in the United Kingdom continues to serve specification-driven projects with a focus on raised floor tiles and integrated systems that align with architectural and engineering workflows.
Raised Access Floor Market
Strategic momentum in this sector is not static. Recent developments illustrate how competition is intensifying through both product innovation and service model expansion. In January 2026, Huilian highlighted its R&D commitment by showcasing more than seventy patents, including ten invention patents focused on raised access flooring systems. This level of intellectual property activity suggests a deliberate push toward proprietary design features that can create specification lock-in and improve margin resilience. In November 2025, The Access Flooring Company introduced an AI-powered chatbot service intended to provide immediate expert assistance on raised access flooring systems, reflecting a wider industry trend toward digital support channels that reduce specification friction and accelerate project decision cycles. On the project delivery side, Strut Systems Installation carried out a custom Unistrut framing support system for raised access floors at a major university in May 2025, illustrating how specialized framing solutions are being deployed to increase load capacity in high-traffic institutional settings. These examples are not isolated news items; they are indicators of how companies are competing on engineering depth, service accessibility, and application-specific performance.
Market Dynamics: Raw Material Economics and Regulatory Tailwinds
Infrastructure markets rarely move in isolation from input costs and standards evolution, and the raised access floor sector is no exception. Steel pricing, a fundamental driver of material economics for encapsulated and structural panel systems, has shown notable regional divergence. In May 2026, steel plate prices in Northeast Asia reached approximately USD 1.83 per kilogram, representing an 8.3 percent increase from the prior month, while North American prices stood at roughly USD 2.74 per kilogram, down 7.4 percent over the same period. This divergence matters because it influences regional manufacturing cost structures, export competitiveness, and the relative attractiveness of locally sourced versus imported components. Procurement leaders who monitor these shifts can time commitments more effectively, structure contracts with appropriate escalators, and evaluate supplier stability with greater foresight.
On the regulatory and standards front, recent updates to ASHRAE Standard 62.1 have explicitly referenced underfloor air distribution as a best-practice ventilation strategy, reinforcing the specification of raised access floors in new commercial construction projects. This kind of standards-level recognition does more than validate an existing technology; it shapes designer behavior, influences building certification pathways, and creates a durable preference signal for systems that support controlled air movement and energy-efficient ventilation. As sustainability mandates and indoor environmental quality requirements continue to tighten, specification advantages tied to recognized standards can meaningfully affect tender outcomes and architectural preference. Our report weaves these dynamics into a broader framework, helping readers understand not only what is happening, but why it matters for specification strategy, cost planning, and long-term asset performance.
Worldwide Reinforced Concrete Floor Market
Why This Research Is Positioned for 2026 Decision-Making
The 2026 planning cycle presents a convergence of operational pressures and strategic opportunities. Organizations are simultaneously managing data center expansion, office space realignment, and stricter environmental and safety expectations. In that environment, raised access flooring is no longer a commoditized line item; it is a design decision that affects airflow performance, cabling flexibility, maintenance access, load resilience, and future retrofit costs. Executives who treat it as a strategic variable rather than a passive procurement category will be better positioned to control total cost of ownership and reduce specification risk.
The full PW Consulting study is built to support that shift in mindset. It provides a clear analytical bridge from macro growth patterns to segment-level decision logic, from competitive positioning to supplier evaluation criteria, and from raw material volatility to contracting strategy. Readers will find frameworks that can be applied directly to capital planning, vendor shortlisting, specification development, and regional market assessment. The report is also structured to help leadership teams ask sharper questions: Which material and construction types align with anticipated load and environmental requirements? Where do integration benefits justify premium specifications? How do regional cost structures and standards environments shape supplier selection? What early indicators suggest shifts in competitive advantage or pricing power?
Accessing the Complete Intelligence
This article is intended as a strategic prelude rather than a standalone briefing. The growth trajectory, competitive behaviors, and market dynamics described here reflect the analytical foundation of our broader study, but the full report contains the detailed segmentation logic, company evaluations, specification guidance, and forward-looking scenario analysis needed to translate insight into action. For executives, project leaders, and investment planners navigating infrastructure decisions in 2026 and beyond, the complete PW Consulting Raised Access Floor Market research offers a structured, evidence-based pathway to more confident decision-making. We invite you to explore the full study for the comprehensive data, segmentation depth, and competitive intelligence that will support your next planning cycle.
For detailed analysis of this topic, please visit the official page: Raised Access Floor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


